Dow Theory and the Unemployment Rate

For some, the economy has not fully recovered until the unemployment rate is “back where it was” when the economy was booming.  Unfortunately, there are key issues with this notion. Continue reading

Review: Baidu on Pace to Meet Upside Target

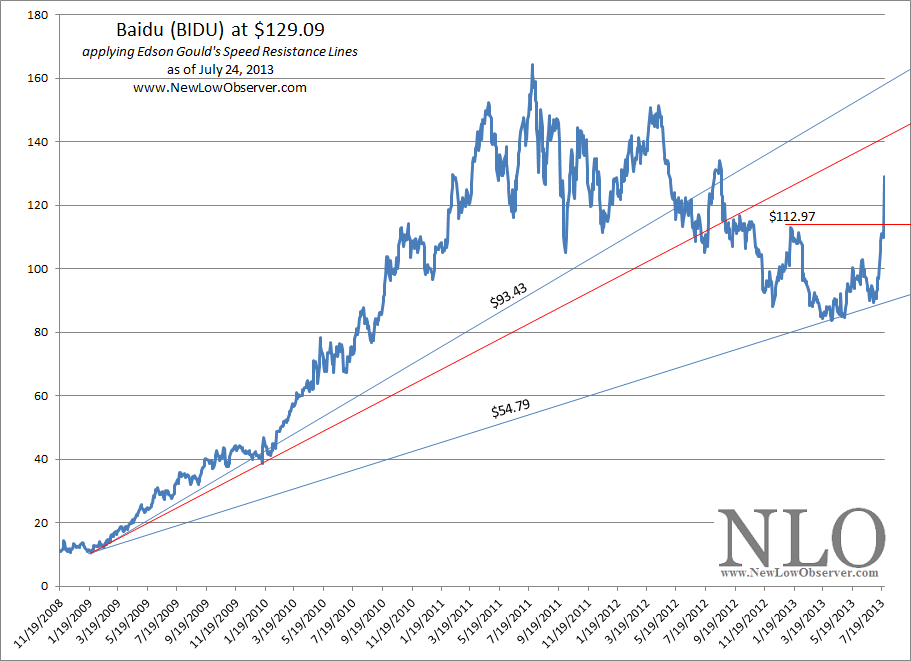
On July 24, 2013, Baidu (BIDU) announced that earnings and revenue beat expectations while raising their 3rd quarter expectations above current analyst estimates.  We had previously said that Baidu needed to exceed the $112.97 level before being able to achieve our next upside target.  In two trading sessions since or recommendation of the stock on April 26, 2013 at $85 (found here), Baidu struggled to exceed $111 (July 18th and 19th).

However, at the end of trading during the regular session on July 24th, Baidu closed at $113.37.  As the news came out about earnings and revenue, the stock catapulted to close at $129.09 in after-hour trading.  at this point, we firmly believe that Baidu is set to achieve our previously indicated upside target of $140.  A doubling of the stock price since our recommendation of BIDU is not out of the question (within the year from the $85 price).  Get your sell orders ready (principal only), no use getting greedy on gains of +50% in 3 months.  Below is the updated SRL for BIDU.

image

Transaction Alert

Continue reading

Canadian Dividend Watch List: July 19, 2013

This is a list of Canadian dividend stocks that currently, or in the past, had a history of consecutive dividend increases. For those wishing to find the most complete fundamental information on these companies, we recommend visiting one of Canada’s leading financial websites, the Financial Post (found here). However, Yahoo!Finance probably has the better long-term charts and historical dividend data.

Continue reading

Gold Stock Indicator

Continue reading

Intuitive Surgical Downside Targets

Continue reading

Review: Apple’s Altimeter

Continue reading

Review: Baidu Trending Higher

Continue reading

Nasdaq 100 Watch List: July 12, 2013

Below are the Nasdaq 100 companies that are within 11% of their respective 52-week lows. Stocks that appear on our watch lists are not recommendations to buy. Instead, they are the starting point for doing your research and determining the best company to buy. Ideally, a stock that is purchased from this list is done after a considerable decline in the price and rigorous due diligence. Continue reading

Dividend Watch List: July 12, 2013

Below are the 9 companies on our U.S. Dividend Watch List that are within 11% of their respective 52-week lows. Stocks that appear on our watch lists are not recommendations to buy. Instead, they are the starting point for doing your research and determining the best company to buy. Ideally, a stock that is purchased from this list is done after a considerable decline in the price and rigorous due diligence.

Continue reading

Gold Stock Indicator

Continue reading

Review: XAU Speed Resistance Lines

In our very first attempt at understanding Edson Gould’s Speed Resistance Lines, when the Philadelphia Gold and Silver Stock Index (XAU) was within 6 trading days of the top (found here), we said the following: Continue reading

Review: Royal Gold (RGLD) Speed Resistance Lines

On October 12, 2012 (found here), when Royal Gold (RGLD) was within 11 trading days of the all-time high at $89.27, we said the following: Continue reading

Tesla Motors Added to Nasdaq 100, The Countdown Begins

On July 8, 2013, it was announced that Tesla Motors (TSLA) would join the Nasdaq 100 starting on July 15, 2013 (PR here).  Our analysis of Tesla will follow the review and performance of additions and deletions to the NASDAQ 100 Index.

As has been well documented on our site, the Nasdaq OMX has a history of adding and deleting companies on the Nasdaq 100 Index in a manner that is consistent with a money losing speculator.  The most recent example of the NASDAQ OMX follies, prior to TSLA, was when Netflix (NFLX) was added to the index after the stock price rose +141.32%…after being dropped from the index on December 24, 2012 (PR here).  Not to be outdone by itself, the NASDAQ OMX team previously added NFLX to the Nasdaq 100 on December 20, 2010 (PR here).

Our NASDAQ OMX debrief on NFLX additions and deletion:

  • Added to Nasdaq 100 on 12/20/2010: stock declines –49.32%
  • Dropped from Nasdaq 100 on 12/24/2012: stock gains +141.32%
  • Added to Nasdaq 100 on 6/6/2013: to be determined; up +11.98% so far

In our annual Nasdaq 100 Re-Rank Review in December 2012 (found here; includes 2010 and 2011 reviews), we pointed out that the stocks being dropped from the index typically outperform the stocks that are added to the index within the first year (our minimum benchmark).  Below is the performance of the stocks that were added or dropped since the Nasdaq 100 changes on December 24, 2012:

Symbol
Name 12/24/2012 7/10/2013 % change
ADI Analog Devices, Inc. 41.35 46.73 13.01% added
CTRX Catamaran Corporation 49.2 47.31 -3.84% added
DISCA Discovery Comm. 60.82 82.86 36.24% added
EQIX Equinix, Inc. 198.56 190.84 -3.89% added
LBTYA Liberty Global Inc. 60.31 77.42 28.37% added
LMCA Liberty Media Corporation 110.5 135.06 22.23% added
REGN Regeneron Pharmaceuticals 179.71 236.7 31.71% added
SBAC SBA Communications Corp. 69.62 75.94 9.08% added
VRSK Verisk Analytics, Inc. 48.84 61.67 26.27% added
WDC Western Digital Corporation 37.78 67.23 77.95% added
Average +23.71%
Symbol
Name 12/24/2012 7/10/2013 % change
APOL Apollo Group Inc. 21.02 17.89 -14.89% dropped
EA Electronic Arts Inc. 15.3 23.9 56.21% dropped
FLEX Flextronics International 6.09 7.86 29.06% dropped
GMCR Green Mountain Coffee 40.32 70.09 73.83% dropped
LRCX Lam Research Corporation 36.37 49.52 36.16% dropped
MRVL Marvell Technology Group 8.21 11.71 42.63% dropped
NFLX Netflix, Inc. 93.3 243.82 161.33% dropped
RIMM Research In Motion Limited 14.04 9.28 -33.90% dropped
VRSN VeriSign, Inc. 35.9 45.66 27.19% dropped
WCRX Warner Chilcott plc 11.7 19.53 66.92% dropped
Average +44.45%

As can be seen in the table above, on average, the stocks that were “added” underperformed the stocks that were “dropped” by 87%.  To be fair, if we exclude the gains of Netflix (NFLX), then the gains of the stocks “dropped” from the index would fall to +31.47%.  However, this is still nearly 33% greater than the gains achieved by the stocks that were “added” to the Nasdaq 100 Index.  Alternatively, if the highest performing stocks were deleted from each group, then the gains would be +17.69% for “added” versus +31.47% for “dropped”.

We understand that the parameters for addition and deletion of companies to the Nasdaq 100 are mechanical and therefore cannot discern qualitative aspects of the stocks being included in the index.  However, individual investors should strategize around some of the demonstrated weakness and strengths of companies added to and dropped from the Nasdaq 100 Index.

Tesla Downside Targets

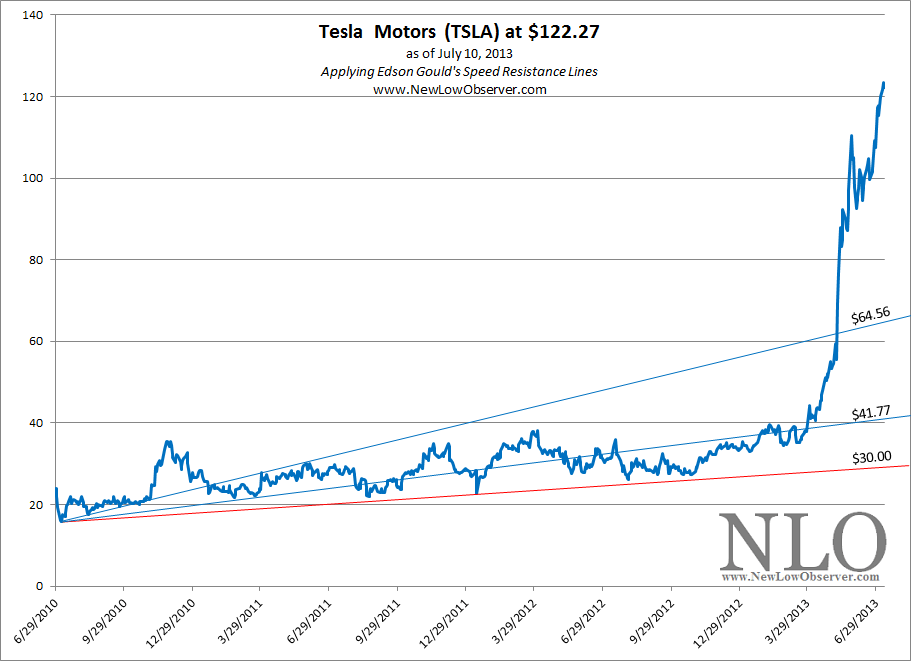
With Tesla being added to the Nasdaq 100 after the stock has climbed a parabolic wall of worry, it seems fitting that we are now able to project downside targets for the stock applying Edson Gould’s Speed Resistance Lines (SRL).  Below is the SRL for Tesla Motors as of July 10, 2013:

image

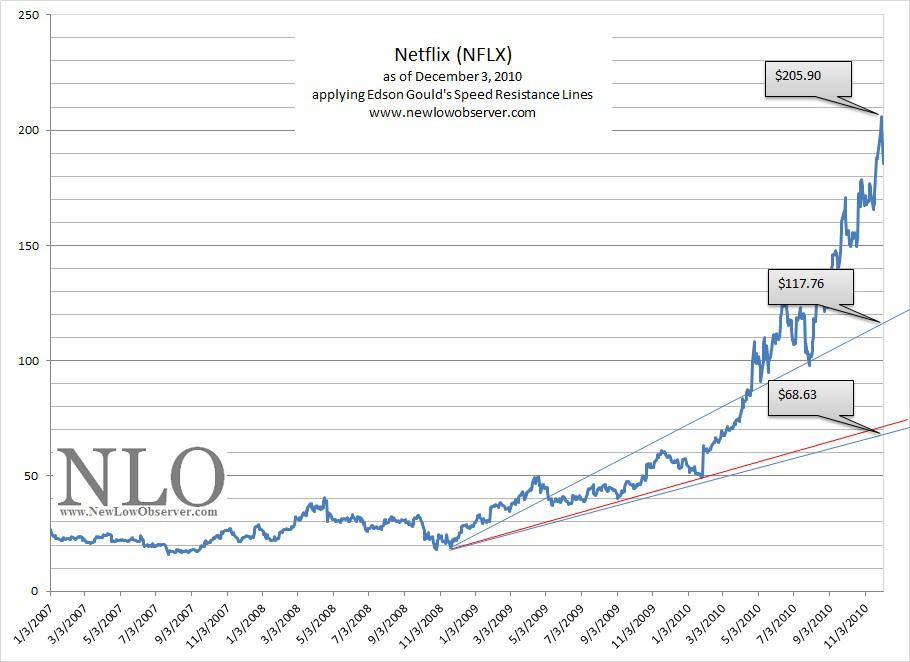
Few stocks that we have run the SRL on had such an extraordinary climb in price.  Even our Netflix SRL (found here) from December 3, 2010 had a more gradual rate of increase.  Based on Edson Gould’s SRL, TSLA has a conservative downside target of $64.56 while the extreme downside target is set at $41.77.  There is the off-chance that TSLA could go as low as $30.  However, this interpretation cannot be taken into consideration until TSLA reaches the $41 level.

Keep in mind that falling by half is not an easy task.  As was the case with our Netflix SRL from December 3, 2010, NFLX climbed +61.08% before falling below both our conservative and extreme downside targets.  We don’t short stocks based on SRL.  Instead, we consider buying stocks once they achieve our downside targets.

With Tesla Motors being added to the Nasdaq 100 Index after having an increase in price by +264% in the last six months, there will be plenty of action for this stock in the short and long-term.
Gold Price: Affected by Gold ETF Outflows?

Subscriber F.H. brings our attention to a comment made by a gold fund manager.  The manager suggested that the reason for gold’s weakness is primarily due to the liquidation occurring in gold ETFs.  This implies that if there weren’t gold ETFs, then the price of gold would not decline as much as it already has (possibly not at all).  However, our work on this topic is to check the data and show how easily this can be proven an incorrect analysis.

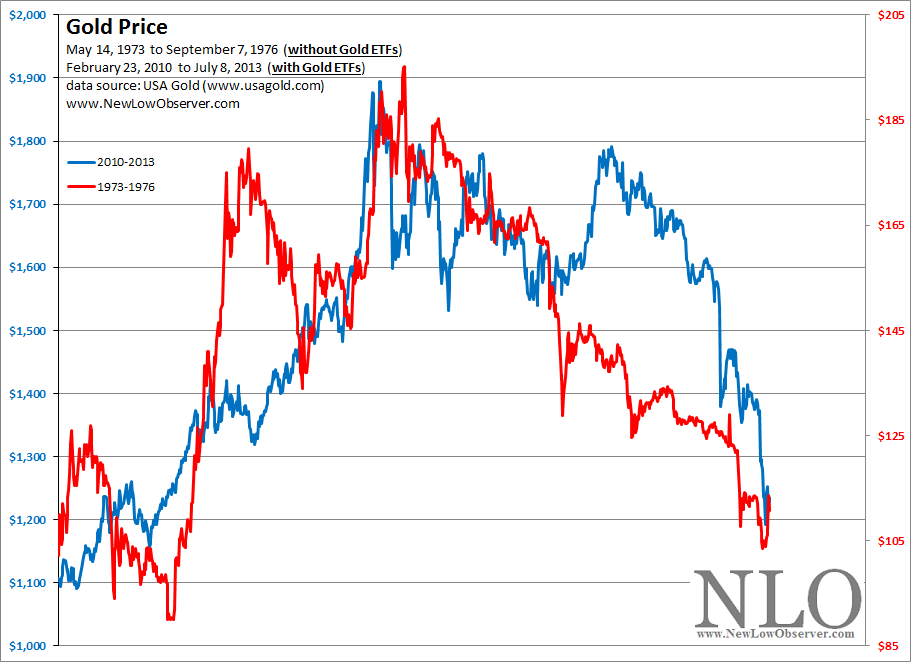
The chart below quickly demonstrates that gold outflows from ETFs is a symptom and not the cause in the decline of gold.

image

What did we do to arrive at the outcome above?  First, we already knew that the price of gold declined -50% from the 1974 peak to the 1976 trough.  This simple fact, within what is widely accepted as the last secular bull market for gold (1971-1980), acted as our starting point.  In our myopic view, when comparing data, you must compare like to like, bull market to bull market and bear market to bear market.  Therefore, selecting a set of data from the secular bear market in gold from 1980 to 1999 would result in flawed analysis.

Second, we took the period when gold went from $100 to its respective peak in 1974 and trough in 1976 then compared that period (in trading days; 833 days) to the current period going backwards 833 trading days.

Finally, we noted the fact that each period was with and without gold ETFs.

  • Please note that when we analyze any data, we only seek the “big picture” view, something akin to the horseshoes and hand grenades analogy.

What is our interpretation based on this rudimentary and potentially flawed approach?

First, gold ETF outflows are not the reason why gold is declining.  Instead, gold ETF outflows are a mirror of the price of gold, albeit a somewhat distorted mirror.

Second, the decline in the price of gold has been normal within what we believe to be a secular bull market in gold.  So far, gold has declined “only” –35% from the 2011 peak.  This is contrasted with the aforementioned decline of –50% from the 1974 peak to the 1976 trough.  What would change our view that we are no longer in a secular bull market in gold?  Our highly biased view is that a bear market begins when gold and silver declines below our 1996 purchase price of the respective metals.  However, the real world analysis says that a secular bear market is confirmed when gold attempts to go above the $1,895 price but fails.  Lacking a qualified retest of the prior high, we will infer that we’re still within a secular bull market for precious metals.

Third, our view is that when a gold fund manager speaks they have only one message, gold related investments are always good and never bad.  This opinion is the same for technology, biotechnology, small cap, large cap and international fund managers.  There will never be a day when a fund manager says, “My fund is [I’m] not needed for the next several months or years.”

Our final interpretation is that when a gold fund manager uses the explanation that the outflow of funds from gold ETFs is the predominate reason for the price decline in gold, it demonstrates a significant lapse of analysis.