Category Archives: Dow Theory

Dow Theory on Marvell Technology Buyout Rumors

Today the price of Marvell Technology increased +8.49% after news of KKR & Co. having acquired 5% of the chipmaker.  According to Bloomberg News:

“KKR & Co. (KKR) has acquired almost 5 percent of computer chipmaker Marvell Technology Group Ltd. (MRVL), two people with knowledge of the matter said.

KKR sees the Hamilton, Bermuda-based company as undervalued and has discussed its holding with the company’s co-founders, Chief Executive Officer Sehat Sutardja and his brother Pantas, said one person, who asked not to be identified as the information is private. One scenario New York-based KKR is considering is a leveraged buyout of Marvell, though no such deal is imminent, the person said (source link).”

On our Nasdaq 100 watchlist dated June 20, 2012, we had the following to say about Marvell Technology (found here):

“Dow Theory suggests that the following are the downside targets for Marvell:

  • $10.61
  • $7.54
  • $4.47

So far, Marvell has fallen within 6% of the $10.61 target, however, it has not breached that point thus far.  We’d be buyers of the stock at $8.25 with little regard for downside risk at that point in time.”

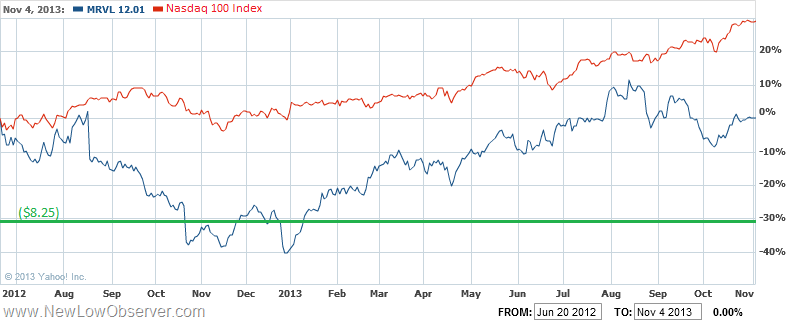
Since June 20, 2012, Marvell has had the following price performance:

image

If measured by the very first day that Marvell fell below $8.25, the stock has increased +66.18% in just over one year ($7.57-$13.03).  However, if Marvell were measured based on the price before the announcement of KKR’s interest in the stock, the increase in the stock has been +45.57%. 

From our perspective, considering Marvell undervalued after a +45% run up in the price is a stretch.  However, we suspect that KKR will try to squeeze out as much of this stock as possible.  Charles H. Dow, co-founder of the Wall Street Journal, has the following to say on this particular topic:

“It is a matter of comparative indifference with a large operator whether the stock which he is handling is a point or two higher or lower.  The thing which is important is whether the public follows up the advances so that he can sell (Dow, Charles H. Review and Outlook. Wall Street Journal. June 29, 1899.)”

In this case, the large operator is KKR & Co.  Their goal is to see that Marvell rises as much as possible after they have taken a sizable position.  One method to do this is to announce, through major channels of communication with unnamed sources, that they have taken a sizable position.  What should happen next is continued speculation of whether or not Marvell is acquired by a competitor or another private equity firm, ultimately pushing the stock price higher.  Unfortunately, those relying on such information may be caught holding the bag if all the rumors are proven to be just that.

It is Dow Theory that has pointed us in the direction of when to look to acquire or accumulate stocks and it is also Dow’s theory that suggests when to be cautious and possibly sell.  For now, Dow Theory indicates that the fair value of Marvell is $14.58.  Exceeding the fair value target offers up significant opportunity.  Remember, a large operator like KKR isn’t aiming for a “point or two higher.”  If the rumors are true, KKR probably has their sights set on $22 or above. However, any price above $14.58 should be considered speculation, at best.

“Affairs are easier of entrance than of exit; and it is but common prudence to see our way out before we venture in.” –Aesop

Dow Theory

Continue reading →

Dow Theory: Buying in Scales

Reader J.P. asks:

“What is your recommendation for taking a position.  All in, or 1/2 in and average up or down. I can't find anything on this on the website.”

Our Response:

Continue reading →

Dow Theory: Secondary Reactions

Continue reading →

Gold Stock Indicator: September 18, 2013

Continue reading →

Dow Jones Industrial Average Additions and Deletions 1884-2013

image

Silver: Downside Targets Met

As early as May 5, 2011, when silver was trading at $35 an ounce, we’ve maintained the view that the prospect of silver, in the form of the exchange traded fund iShares Silver Trust (SLV), falling below $20 was well within the realm of possibility (article here).  At the time, we said the following: Continue reading →

Precious Metal Stocks: September 7, 2013

Below is a list of gold and silver stocks that are ranked based on their upside potential according to Dow Theory estimates of fair value.  As with any investment consideration, the stocks that have the highest percentage upside potential should be considered the highest risk with the most volatility.   We believe that stocks with upside potential below +143% are the most likely to achieve their Dow Theory fair value targets. Continue reading →

Dow Theory and the Unemployment Rate

For some, the economy has not fully recovered until the unemployment rate is “back where it was” when the economy was booming.  Unfortunately, there are key issues with this notion. Continue reading →

Investing in Foreign & Emerging Stock Markets

Subscriber R.G. asks:

“If emerging markets possess such a gambit due to their lack of similar history in the past how can we analyze the markets in order to capitalize on their surges of demand which quickly taper[s] off?”

Our general view on foreign and emerging markets is similar to that of Warren Buffett’s when he said:

“'If I can't make money in the $4 trillion US market, I shouldn't be in this business. I get $150 million earnings pass-through from the operations of Gillette and Coca-Cola. That's my international portfolio’ (source: Ellis, Charles D. Wall Street People. page 56. link here.)”

There seems to be little need to invest in foreign or emerging markets.  However, if there is a desire to invest in foreign markets then Dow Theory provides a reasonable template for how to approach investing in such a market.  In a section titled “Dow's Theory True of Any Stock Market,” William Peter Hamilton says the following:

“The law which governs the movement of the stock market, formulated here, would be equally true of the London Stock Exchange, the Paris Bourse or even the Berlin Boerse. But we may go further. The principles underlying that law would be true if those Stock Exchanges and ours were wiped out of existence. They would come into operation again, automatically and inevitably, with the re-establishment of a free market in securities in any great capital. So far as, I know, there has not been a record corresponding to the Dow-Jones averages kept by any of the London financial publications. But the stock market there would have the same quality of forecast which the New York market has if similar data were available. (source: Hamilton, William Peter. Stock Market Barometer. Harper & Brothers Publishers, New York. page 14. link here.)”

When we speak of Dow Theory, we are referring to the emphasis of values, fundamentals in relation to price as they pertain to individual stocks and the stock market.  We are putting less emphasis on the strict technical analysis of the equivalent industrial and transportation indexes. 

To be clear, because we live in the United States we emphasize investing in the U.S.  However, according to Hamilton, it does not matter which country that you’re in, investors should embrace the comparative advantage of living in a country other than the United States and should become experts of value opportunities in that region.

Dow Theory

Continue reading →

Dow Theory: Downside Targets

It has been almost two months since our last Dow Theory posting.  This is as it should be, since Dow Theory does not require a daily accounting of changes to the market.   As indicated in Robert Rhea’s The Dow Theory:

“There are three movements of the averages, all of which may be in progress at one and the same time.  The first, and most important, is the primary trend: the broad upward or downward movements known as bull or bear markets, which may be of several years’ duration.  The second, and most deceptive movement, is the secondary reaction: an important decline in a primary bull market or rally in a primary bear market.  These reactions usually last from three weeks to as many months.  The third, and usually unimportant, movement is the daily fluctuation.” (source: Rhea, Robert. The Dow Theory. Barron’s, New York. 1932. Page 32.)

Continue reading →

Dow Theory Q&A

Reader BlueIce comments (found here):

“So for the past four years, the NYSE is up but volume down…What is the root cause, if any? Bank Bernankski ?”

Our Response:

While there is considerable belief that the Federal Reserve has been the main driver in the financial markets since the March 2009 low, we believe that the Fed’s activity has NOT YET been felt in the stock market.  First we’ll explain the two primary reasons we believe this. Afterwards, we’ll explain what we believe are the possible outcomes to the Fed’s current policies.

First, in our January 19, 2011 article titled “Federal Reserve Isn’t to Blame for the Current Market Run” (found here), we concluded with the following thought:

“A cursory review of market data during the periods from 1860 to 1914 makes it clear that declines of nearly -50% or more are likely to retrace +66% to +100% of prior declines. This pattern has been easily demonstrated in the periods after 1914. However, we’re only trying to illustrate that the acceptance of the Federal Reserve’s role as the leading cause of the current +69% retracement of the prior decline (2007-2009) is false.”

We’ve maintained the view that the Federal Reserve’s impact on the stock market has been muted so far. 

Second, regarding the issue of manipulation of the markets, which is implicit in the discussion of the Federal Reserve’s involvement in the rise of the stock market, we take the Dow Theory view on the topic. Charles H. Dow was very specific about market manipulators and manipulation. Dow has said that manipulation is a factor of the market in the day-to-day movement. However, the long-term trend of the market cannot be manipulated as demonstrated in detail from the writings of William Peter Hamilton, former editor of the Wall Street Journal.

Hamilton says of manipulation:

“The market is always under more or less manipulation.”

“Even with manipulation, embracing not one but several leading stocks, the market is saying the same thing, and is bigger than the manipulation”

“Major Movements Are Unmanipulated-One of the greatest of misconceptions, that which has militated most against the usefulness of the stock market barometer, is the belief that manipulation can falsify stock market movements otherwise authoritative and instructive”

“These discussions [of manipulation] have been made in vain if they have failed to show that all the primary bull markets and every primary bear market have been vindicated, in the course of their development and before their close, by the facts of general business, however much over speculation or over-liquidation may have tended to excess, as they always do, in the last stage of the primary swing”

“It has been shown that, for all practical purposes, manipulation has, and can have, no real effect in the main or primary movement of the stock market, as reflected in the averages. In a primary bull or bear market the actuating forces are above and beyond manipulation. But in the other movements of Dow’s theory, a secondary reaction in a bull market or the corresponding secondary rally in a bear market, or in the third movement (the daily fluctuation) which goes on all the time, there is room for manipulation, but only in individual stocks, or in small groups, with a well-recognized leading issue”

(Source: Hamilton, William Peter, The Stock Market Barometer, Wiley & Sons, New York, 1922.)

The Fed and world central bank manipulation has an impact on the day-to-day and maybe the medium-term, however, the long term will exert itself regardless of the manipulation.

Finally, while we are skeptical about the Dow Theory secular bull market indication, we have to accept that it is real. As with most economic policy, the impact is felt long after the implementation. Dow Theory might be saying that we’re about to enter a phase hyper-activity in the stock market. If this is the case, then we just might see the impact of the Federal Reserve’s stimulus of the last several years finally kick in, catapulting the stock market to unbelievable heights.

The lack of trading volume in the stock market since 2009 reflects little or no participation on the part of the public.  If this is true, then any meaningful rise in trading volume (on the buying side) due  to added participation from the public could result in tremendous gains.  This thought sits in the back of our mind as we strategize the best way to take advantage while not being over exposed.

When we say that the public hasn’t participated in the stock market’s rise, who cares?  The answer is the very financial institutions that required bailouts in 2008.  They have been trading amongst each other in a game of hot potato.  If the public doesn’t jump in soon there could be major fireworks to the downside.

Again, if the Dow Theory bull market indication isn’t real then we’ll see another round of “too big to fail” institutions coming with hat in hand to the U.S. government.  The most vulnerable institutions could be those that were forced to merge with companies like Bank of America/Merrill, Wells Fargo/Wachovia and JPMorgan/Bear Stearns.  From our research on this topic, we’ve seen what happens when a sizable failed institution is forcibly merged with an ailing but salvageable company (i.e. our article on CreditAnstalt).

Apple’s Pain May Be a Warning for the Dow Indices

Since the bull market run began in 2009, Apple (AAPL) analysts have been making persuasive arguments for the stock.  The fundamental case for Apple includes price-to-earnings, price-to-sales, cash reserves, China as an untapped market, etc.  However, as investors have found out, it is the price that matters most as Apple’s stock has taken a hit from the high of $702 on September 19, 2012 to the current price of $443 (March 18, 2013).  While fundamentals are important, there is one obvious problem and that is the trading volume.

In the section on Dow Theory, in the Edwards and Magee book Technical Analysis of Stock Trends, volume is interpreted in the following manner:

“…in a Bull Market, volume increases when prices rise and dwindles as prices decline; in Bear Markets, turnover [volume] increases when prices drop and [volume] dries up as they [prices] recover (33).”

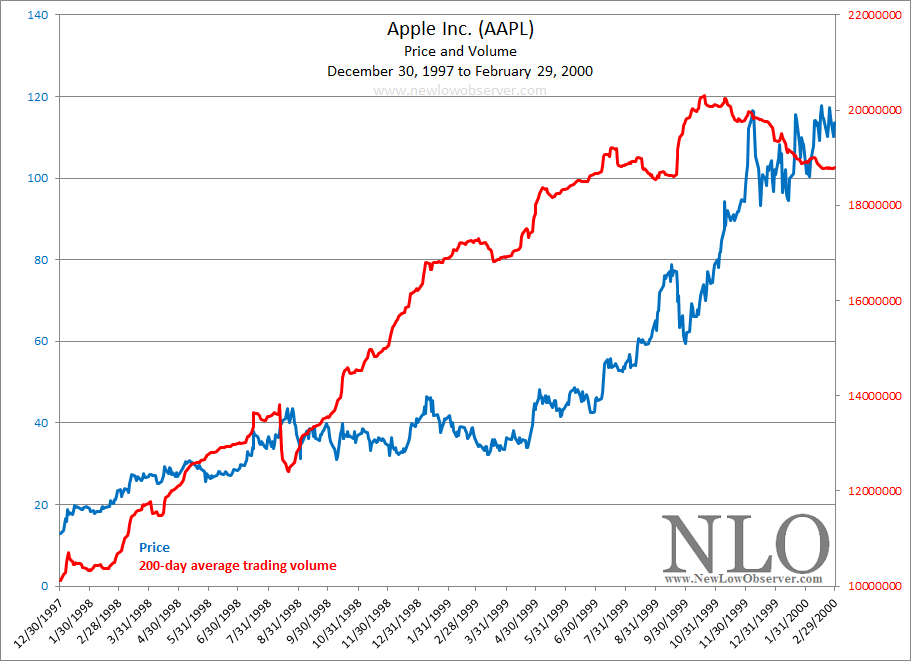
When we compare the previous bullish moves in Apple’s stock price, we find that the most recent run-up stands out as trading volume has not only failed to increase with the stock price, it has been on a divergent path by declining.  However, we need to see how different this most recent rise in the stock price is in contrast with the previous bullish moves.

In the bull market run of Apple from December 30, 1997 to February 29, 2000, the stock price rose +900% while average trading volume increased +1,000%.

image

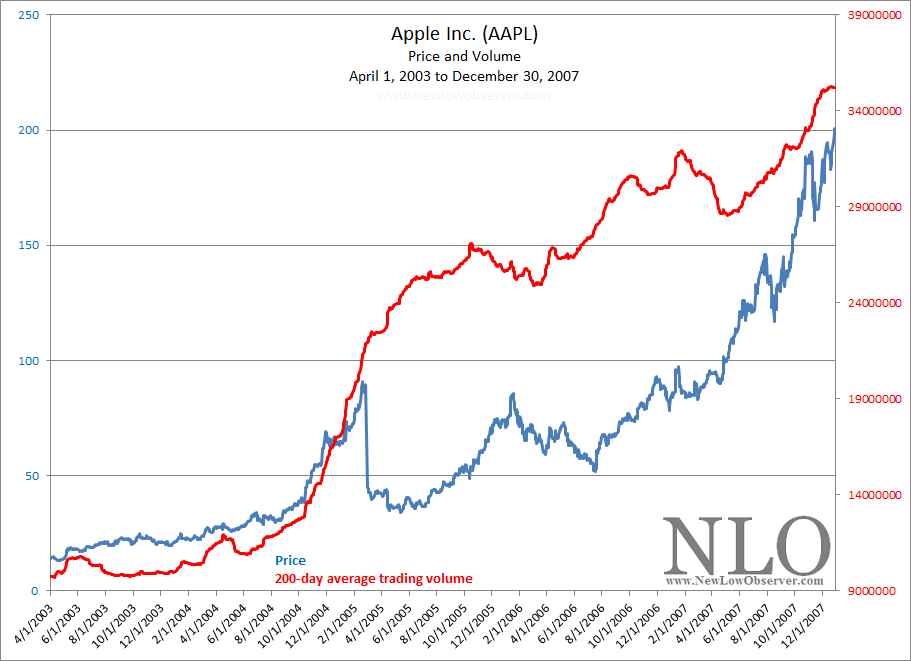
In the bull market run of Apple from April 1, 2003 to December 30, 2007, the stock price rose over +1,400% while average trading volume increased +1,000%.

image

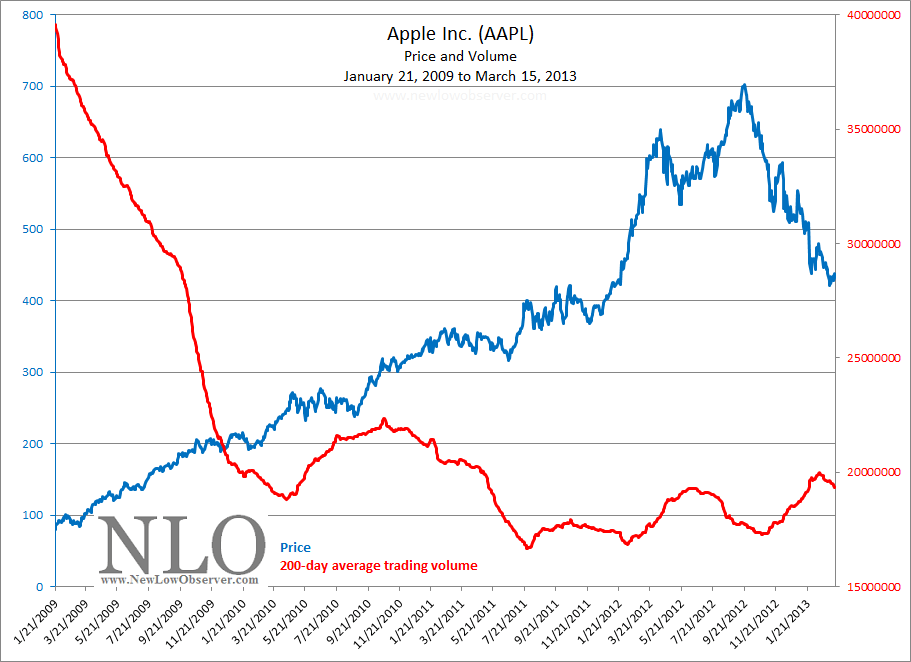
In the bull market run of Apple from January 21, 2009 to the present, the stock price rose nearly +900% while average trading volume decreased -51%.

image

The obvious problem with the current rise in the price of Apple from the January 21, 2009 low to the September 19, 2012 high is that while the stock price has increased dramatically, the trading volume has fallen precipitously. Already, Apple has inexplicably declined –36% from the high. There is little in the way to indicated that the blood-letting is over.

According to Robert Rhea, in his book The Dow Theory, “…the volume of trading has proved to be such a useful guide in attaining proficiency in the art of forecasting market trends that it is necessary to urge all students to study intently the relation of volume to price movement (88).”

It would be foolish for us to think that the decline in volume, from 2009 to the present, while the stock price increased wasn’t a warning sign. It is suggestive of the fact that all was not well and therefore the party had to end at some point in time.  This is despite the otherwise glowing fundamentals that are associated with Apple.

Now, if the almighty Apple can decline –36% in spite of the glowing fundamentals as the Dow Industrials and Dow Transports keep going higher, then what is the fate of two main components of Dow Theory?  By all indications, we should be considered to be in a bear market based on the fact that the price of the Industrials and Transports is increasing as the trading volume dries up.

From our vantage point, there are two distinct outcomes possible for the stock market, based on the above quoted sources.  Either the stock market explodes higher than anyone has ever imagined possible or the stock market declines, –20% to –30% from the current level, as average trading volume skyrockets.  However, our experience so far has been for volume to decrease as the price increased.  Therefore, by our logic, when and if volume starts to increase it will be because institutions will be selling instead of buying the market.

While we have constructed two possibilities, the probabilities are something else altogether.  We think that the fact that volume has been in a clear declining trend, the probabilities favor a decline of the stock market over a sustained increase.  To put this idea into perspective, when we wrote our April 14, 2012 article titled “Consider the Downside Prospects for Apple,” we said that Apple would decline to $424 (found here).  After the article was written, Apple increased by +11%.   However, after Apple peaked, the stock declined –30% from the price where our article was written.  Our only question is, was it worth seeing a rise of +11% only to realize a loss of –30%?

Notes:

  • Because we have a substantial amount in cash and a majority of our holdings that are the profit portion intended to compound over time, we are only compelled to sell those positions that are recent short-term purchases that are more than 5% of our existing portfolio.
  • Our Canadian Dividend Watch List should be coming out this week

Dow Theory: The Beginning of a Cyclical and Secular Bull Market?

The world of Dow Theory was abuzz after the Dow Jones Industrial Average and the Dow Jones Transportation Average charged to all-time highs on March 5, 2013 (found here).  At the time, the Dow Jones Industrial Average had finally capitulated to the inexorable forces that had long since propelled the Dow Jones Transportation Average above the 2011 all-time high.  The confirmation of a Dow Theory bull market came when the Dow Jones Industrial Average finally exceeded the all-time high of 14,164 set in October 2007.

The action of the Dow Industrials and Transports has been so compelling that Dow Theorist Richard Russell acquiesced to the strength of the market on March 11, 2013 by saying the following:

“Yes, I know that this market is uncorrected during its long rise from the 2009 low, and I know that there are risks in buying an uncorrected advance that is becoming uncomfortably long in the tooth, but my suggestion is that my subscribers should take a chance (after all, Columbus took a chance) and take a position in the DIAs.”

In the same posting, Russell later punctuates the point by saying:

“I really believe that subscribers should take a flyer on this market. After all, after weeks of flirting with a new high in the Industrial Average, the Dow finally confirmed the previous record high of the Transportation Average. With the Industrials and the Transports both in record high territory, I think being in the market is justified under Dow Theory.”

By all indications, this Dow Theory bull market indication is the real deal, especially when it is endorsed by Russell’s 55 years of experience on the topic.  The implications of this signal are significant for one very important reason, this time we’ve achieved a secular bull market indication (learn about cyclical and secular trends).

Throughout stock market history, cyclical primary bull markets tend to last 2-4 years.  These bull markets require rapt attention to the nuances and vagaries of changes in the trend.  The last indication of a cyclical primary bull market was on July 23, 2009, when the Dow Industrials traded at 9,069.29.  Based on our interpretation of Dow Theory, we received a cyclical primary bear market indication on August 2, 2011 when the Dow Jones Industrial Average was at 11,866.62.

Secular bull markets, on the other hand, require very little attention and have typically lasted between 15 and 18 years.  Secular bull markets are the proverbial sweet spot of investing with the trend, where “buy-and-hold” is the rule. The two most prominent secular bull markets resulted in the Dow Jones Industrial Average increasing by 10-fold or more. From 1942 to 1966, the Dow rose from 100 to 1000 and in the period from 1982 to 2000, the Dow went from 1,000 to 11,722. If the current implications are correct, we could be on the cusp of a run to Dow 100,000.

Volume: The Lone Holdout

The three major components of Dow Theory are the Industrials, Transports and trading volume.  As described above, the Industrials and Transports have achieved the required all-time highs at (or near) the same time which would indicated that we are in a new cyclical AND secular bull market.  However, volume has been the holdout in the current move higher.

In the seminal book on Dow Theory titled The Stock Market Barometer, written by William Peter Hamilton, it says the following about trading volume, “It is worth while to note here that the volume of trading is always larger in a bull market than in a bear market. It expands as prices go up and contracts as they decline.”

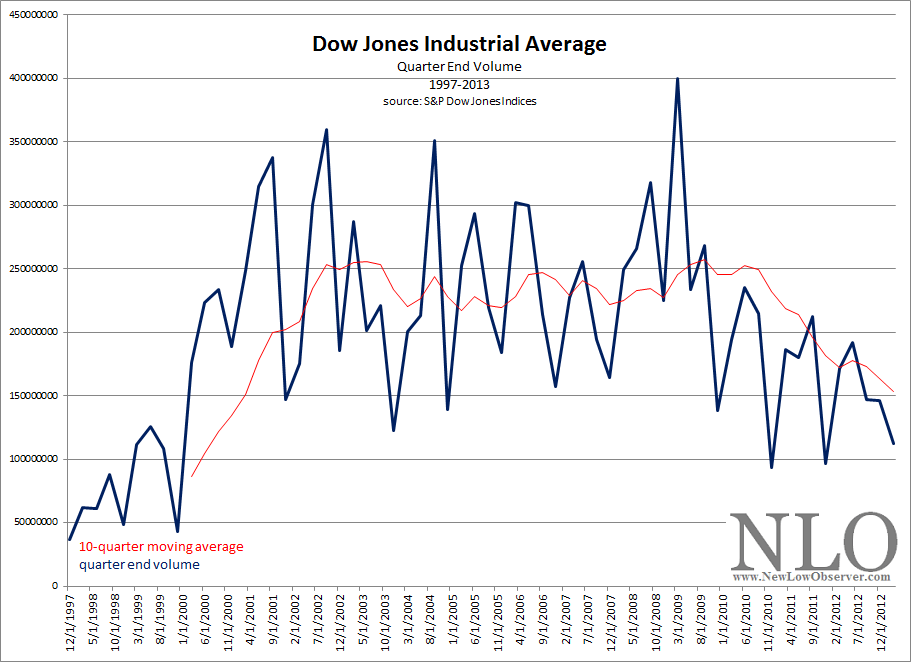
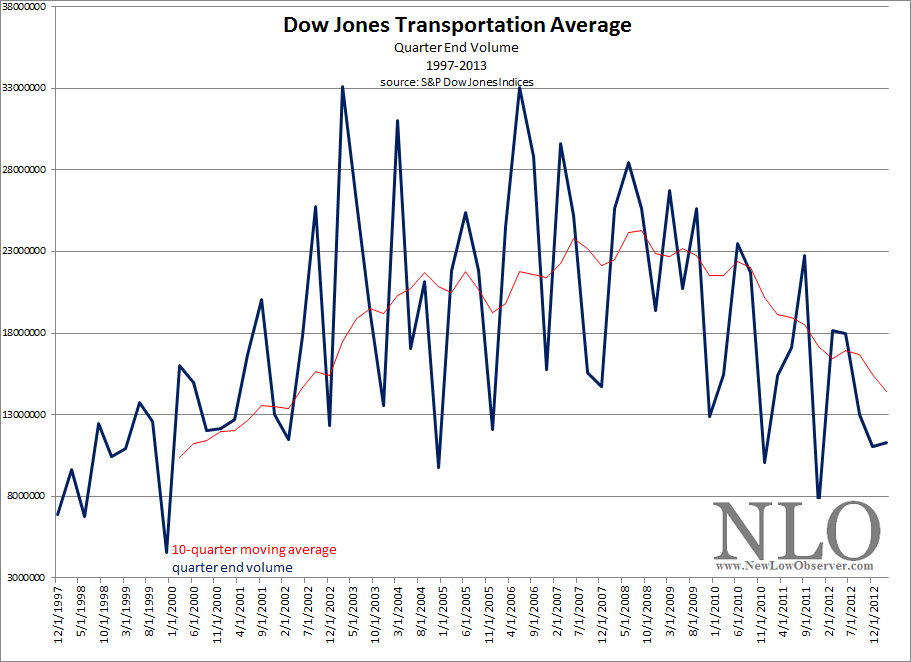
The average trading volume for the Industrials and Transports has been in a declining trend (contracting) since the 2009 low, as seen in the charts below.

image

image

In order for Dow Theory to have relevance, increasing volume needs to accompany the rise of the stock market to ensure that there is sufficient participation and interest.  Unfortunately, average trading volume, as indicated in the above charts for the respective indexes, has been trending lower since 2009.  This suggests that we could only be in an extended  cyclical bull market, within a secular bear market, rather than at the beginning of a cyclical and secular bull market.  The key to understanding trading volume and its interpretation are found in the table below.

volume price interpretation
decrease decrease positive
decrease increase negative
increase decrease negative
increase increase positive

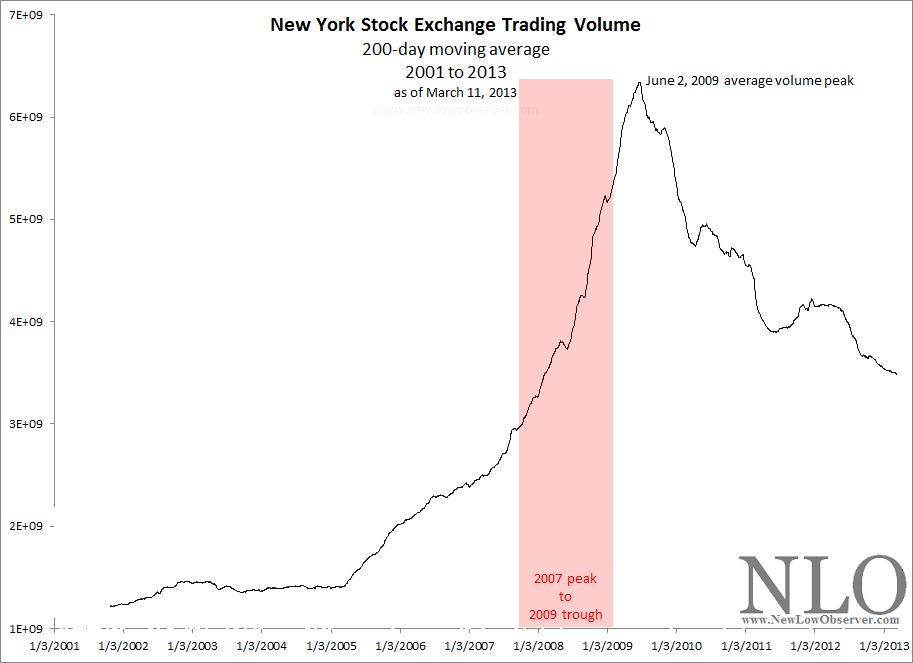
In the days before volume was tabulated for the individual Dow indexes, the New York Stock Exchange trading volume was the proxy for the market trend in conjunction with the Industrials and Transports.  Below is the  200-day average trading volume of the NYSE since 2001.

image

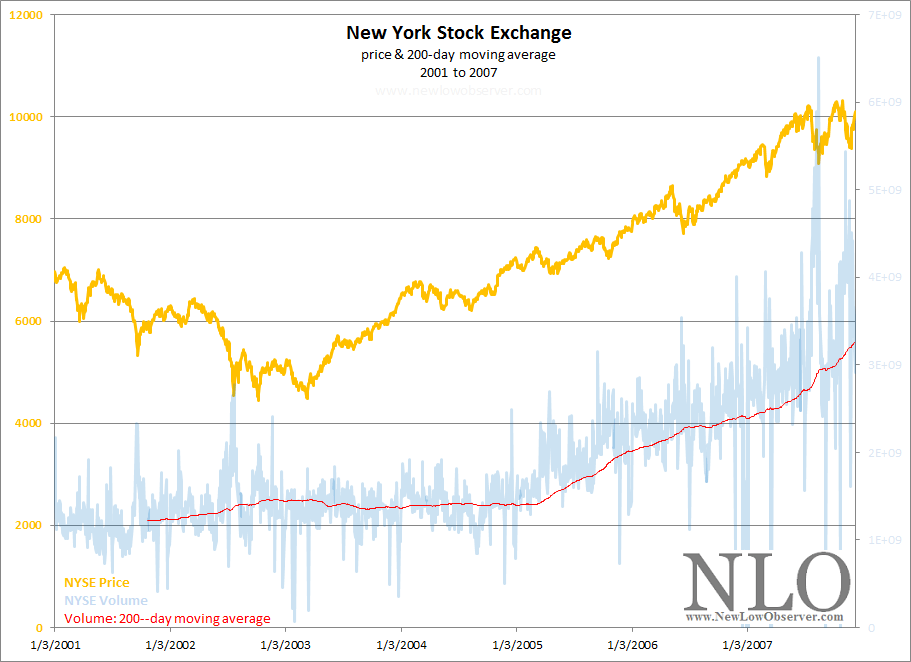
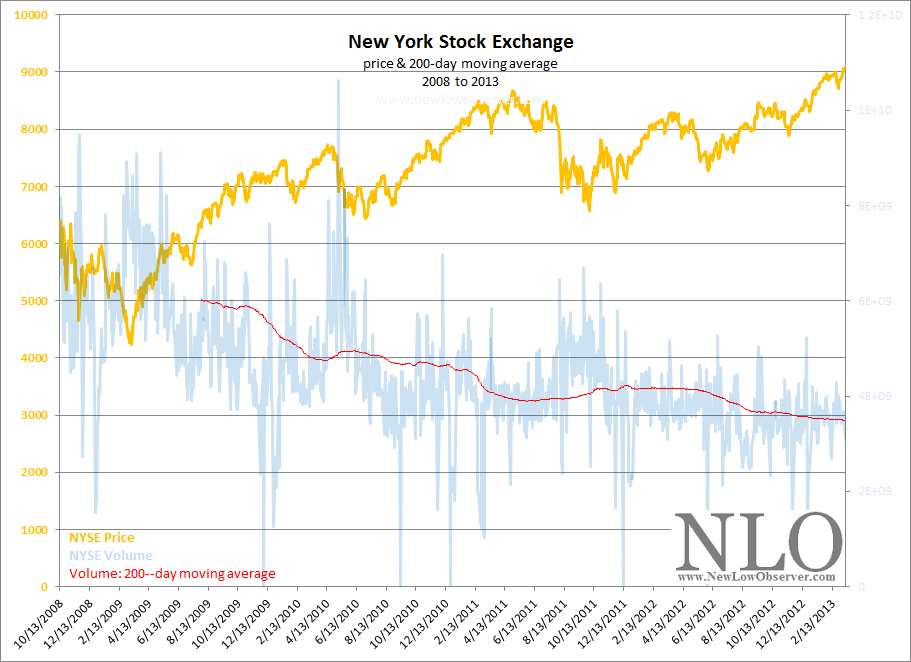
What is evident is the dramatic rise and peak of average trading volume during the decline of the stock market from the peak in 2007 to the bottom in 2009.  However, once the market started taking off, the trading volume uncharacteristically plunged.  To emphasis the point, below we have included the charts for the cyclical bull markets from 2001-2007 and 2009 to the present.

image

In the chart from 2001, we can see that NYSE average trading volume hit a peak in 2002 and then flat-lined for a couple of years until 2005.   However, as the strength in the stock market grew, the trading volume accelerated to new highs.  This was the hallmark of a true bull market run, rising prices and rising volume.

image

In the chart from 2008, the average trading volume for the NYSE has had a declining trend throughout the whole bull market run from 2009 to the present.  As indicated in the table above, declining volume with increasing prices should be interpreted as a negative.  After volume has been in a declining trend for so long, the only alternative is for a dramatic increase.

When the increase in volume arrives, the question then becomes, will there be a dramatic increase or decrease in stock market price?  Will the general public’s lack of participation be the catalyst that charges the market to move higher?  This situation has to be resolved at some point.

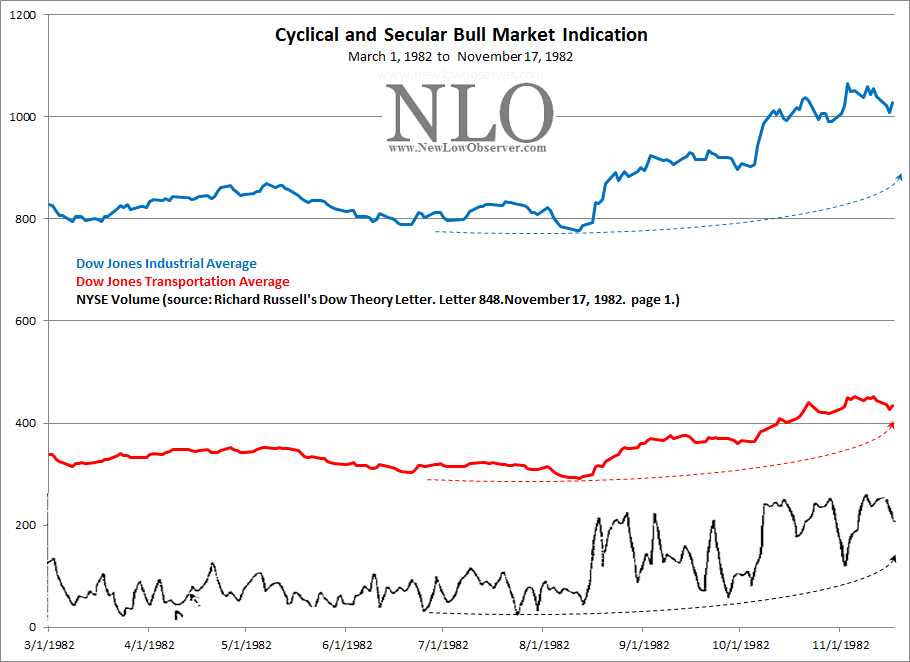
To round out our thoughts on the potential secular bull market signal that we recently received, we thought we would compare it to the last secular bull market change in trend.  In the period from 1966 to 1982, the Dow Industrials never traded significantly above 1,000.  However, that all ended in late 1982 when the stock market broke above 1,000 and never looked back.

Below is a chart of the Industrials, Transports and NYSE trading volume from March 1982 to November 1982:

image

The most important information to be gleaned from this chart is the fact that all three of the essential indicators for Dow Theory were confirming each other at a critical point in time.  They all achieved clear bull market indications by rising in unison.  The current divergence between the Dow indexes with the NYSE trading volume suggests that we will be witness to the greatest transition in the history of the stock market.

The above examination of trading volume, based on a what we believe to be reliable sources, has us concerned that a new secular bull market is not really what we’re witness to.

As William Peter Hamilton has said in The Stock Market Barometer:

“The professional speculator is no more superfluous than the pressure gauge of the steam-heating plant in your cellar. Wall Street is the great financial power house of the country, and it is indispensably necessary to know when the steam pressure is becoming more than the boilers can stand.”

The pressure in the market is building and we may be watching the beginning of the most spectacular stock market blow-off ever.  Just before an even more astonishing decline.