Category Archives: Interest Rate Monitor

Inverted Yield Curve Self-Fulfilling?

In the Crain’s Cleveland Business July 17, 2018 article titled “Fed chiefs look to yield curve for insights into inflation, state of economy,” Atlanta Fed President is quoted as saying that inversion [of yield curve] could be a self-fulfilling prophecy if investors believe it will bring recession.

image

When we looked at the yield curve chart that was provided in the article, it seemed that the either a recession coincided with inversion or inversion coincided with recessions.  However, there was little in the way of indicating that awareness of a pending inversion would lead the public to behave in a manner that would precipitate a recession.

image

It seems that there is enough coincidence of a narrowing of the yield curve and a recession to suggest that if it were a self-fulfilling prophecy then the period of 2010 was the beginning of that process.  The year 2010 happens to be the period when the recession was considered to have ended. Yet, at the time there was no discussion of inversion and self-fulfilling prophecies.

It seems odd for a Fed Bank president to suggest that if people don’t believe it then maybe it won’t happen.

Interest Rate Monitor: July 2018

Below is the updated trend in interest rates.

Continue reading →

Interest Rate Monitor: May 2018

Below are the revised downside targets base on the latest peak in interest rates.

Interest Rate Monitor: Targets

In this postings, we will present upside and downside targets for the 3-month Treasury based on the work of Edson Gould.

Interest Rate Monitor: March 2018

Will rates go up in today’s meeting at the Federal Reserve?

Continue reading →

Rates Up, Utilities Down? Nope!

In a Bloomberg article dated March 14, 2018, it cites a prevailing theme about utilities and interest rates.

“The popular ‘buy banks, sell utility stocks’ strategy, built in anticipation of higher interest rates, is unraveling.

“Utilities were the only gainers in the S&P 500 Index on Wednesday, with the industry that’s seen hurt most by rising Treasury yields heading for its longest rally since November. Financial shares, beneficiaries of higher borrowing costs, sank 1.4 percent for a third day of declines.”

image

While this is a small timeframe to measure the performance of any industry, it does shed some light on the popular interpretations about what a rising interest rate cycle will bring to the market.  One of the most pervasive claims is the interest rate sensitive utilities will suffer with the advent of rising interest rates.

As pointed out in our September 4, 2014 article titled “Utility Stocks and Rising Interest Rates”, we said the following:

“Investors anticipating a general rise in interest rates should feel some comfort in knowing that most manager in the utility sector are ready for what is to come.  Rising interest rates are not an automatic death sentence for utility stock prices or earnings.   In fact, the early stages of rising interest rates may see utility stocks match or exceed the returns of non-interest rate sensitive stocks, on a total return basis.  Only when the outlook is cloudy will it become difficult to offer projections that are in line with prior expectations.”

So far the market is in agreement with our long established thesis that utilities do well in the early stages of the secular rise in interest rates.

Continue reading →

Interest Rate Monitor: February 2018

In all of our postings on interest rates, we have made the claim that the Federal Reserve follows the markets when it comes to setting policy.

Recently there has been a low rumbling that rates might need to be increased faster than expected.  In a USA Today posting on February 19, 2018, it was suggested that faster hikes might be needed.

image

In a Reuters posting dated February 20, 2018, the Bank of Korea Governor Lee Ju-yeol said that  “If (the Fed moves) faster than expected, it will immediately impact international financial markets and also domestic markets as well, so we’re prepared to respond to such a scenario.”

image

If you’re wondering why there is any discussion of rapid rate increases then the story is all in the data that we’ve been tracking below.

The Hidden Story of Gold

Gold is currently languishing in a trading range between $1,366 to $1,049. This trading range is thought by many to be a pause before the eventual increase above the previous high at $1,895.  After all, the price of gold had managed to decline from $1,895 to the low of $1,049.40, a drop of –44.62%.  Part of the thinking of a new high in gold is predicated on the idea that we are entering a phase of rising inflation after years of decreasing inflation from the 1980 peak.

Introduction

If the thinking is that gold is on the cusp of new highs, there is one question that we need to answer.  The question is, “What happens with the price of gold in the early stages of an inflation cycle?”  What is amazing about this question is that in the early stages of the last inflation cycle from 1939 to 1942, gold was fixed at $35 until 1971.

Never in the history of the United States have investors seen the reaction of the price of gold to the early stages of rising interest rates.  In this posting, we’ll attempt to show a reasonable benchmark for gauging what would happen if there weren’t restriction on the  price of gold.

How are we going to explore the price of gold in a period when there was not a free floating price for the metal?  By examining what the price of silver has done in the period when interest rates rise in response to increasing inflation.

Silver is the perfect means to convey the message of what would have happened to the price of gold if it were allowed to navigate the whims of Mr. Market.  While silver is more volatile than gold and prone to extremes it still tells the story of gold when gold did not have a voice.

Interest Rate and Inflation Cycle

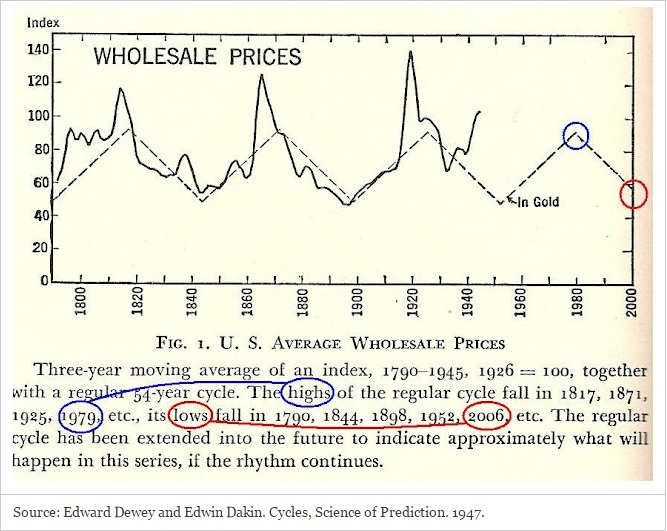
We start with the price of silver from the peak in 1925 because, according to Dewey and Dakin's in their 1947 book Cycles: The Science of Prediction, the last peak in wholesale prices, which generally corresponds to interest rates.  If you have a beat on interest rates, you can get a better sense of where we are and where we might be going as it relates to precious metals.

image

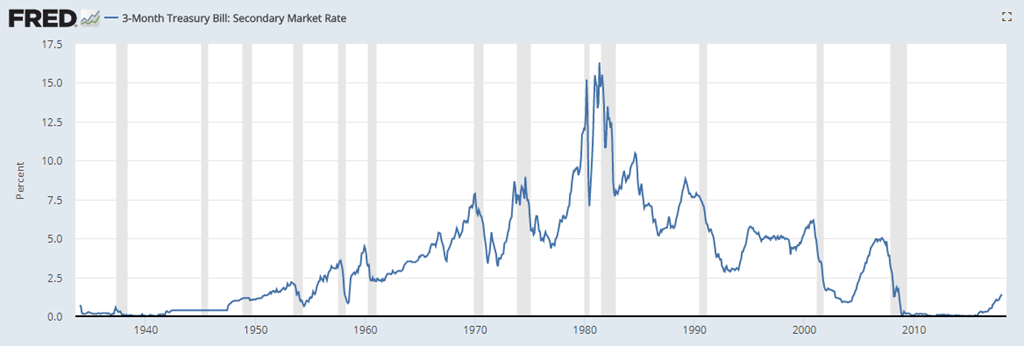
Remember, you don’t have to be a fan of cycle theory to appreciate the quality of analysis that reflects what has already happened from a book written in 1947.  Calling the peak in 1979 and the trough at 2006, while not exact, is the best way to learn from the past.  Looking at the 3-month Treasury, we can see the fulfillment of an entire cycle in rates from 1940 to 2009.

image

Just think, there is no official data that extends from prior to 1934 to the present.  Without this important continuous information, it is difficult to find data that we can compare like-for-like stages in the cycle.  However, we do have data from the price of silver in the previous cycle top to the low that corresponds to the low in interest rates and silver.  This will be our introduction to the secret history of gold.

Continue reading →
Interest Rate Monitor: January 2018

So what is the pattern to the Federal Reserve’s interest rate increases since December 2015?  Quite laughably, we think we have a clue.  Let’s see how this works with our ability to predict the next increase.

Stock Market and Inflation Risk

A reader of our Dow 130k article has raised an important question about the risks that the stock market faces when confronted with the prospect of rising interest rates.  The reader says, in part:

“…they say that interest rates are mean reverting and based on where we are today (historically low) I would think that the betting man would bet that it can only go up from here.  If that is the case, I can't see a bull market in the coming years.

“What if the scenario is that we have permanent low inflation (Secular stagnation). Productivity improvements through outsourcing and technology innovation may explain this paradigm shift.”

We don’t have much to go by other than the historical record.  In this case, the historical record says the following:

  • Interest rates will go up
  • Inflation is broadly bullish for the stock market
  • the period of “low inflation” is behind us

In this article, we will examine, from a historical perspective, whether this is a new era where all of our claims are false or history will repeat.

Continue reading →

Interest Rate Monitor: December 2017

So far, all indications are that interest rates are due to be increased by the Federal Reserve Bank.  There will be many explanations for why interest rates should be increased, however, we believe, as demonstrated by over 40 years of evidence, that the Fed follows market rates and gives an economic justification for their decision afterwards.

Interest Rate Monitor: October 2017

In our August 2017 Interest Rate Monitor, we said the following:

“…we’re holding to the idea that the current range in the trend will remain, until proven otherwise.”

As seen in the chart below, the range that we spoke of is holding strong, for now.

Interest Rate Monitor: August 2017

When it comes to financial markets, the trend is your friend.  In the case of interest rates, more specifically the 3-month Treasury, the trend is up.  Our position is that the free market movement of the 3-month Treasury is the lead for what we can reasonable expected from the Fed Funds Rate which is managed by the Federal Reserve.

Interest Rate Monitor: June 2017

In our last posting on March 13, 2017, we said that the financial markets were widely anticipating that interest rates would increase.  However, we persist in the belief that the leading indication of interest rate direction comes from watching the direction of the 3-month Treasury, which is a market driven instrument.  As reflected in the chart below, we’re in for a bumpy ride ahead.

Continue reading →

Interest Rate Monitor

The markets are anticipating an interest rate increase at the next Federal Reserve meeting on economic policy and many could legitimately say that this anticipation is what drives the short-term rates higher. 

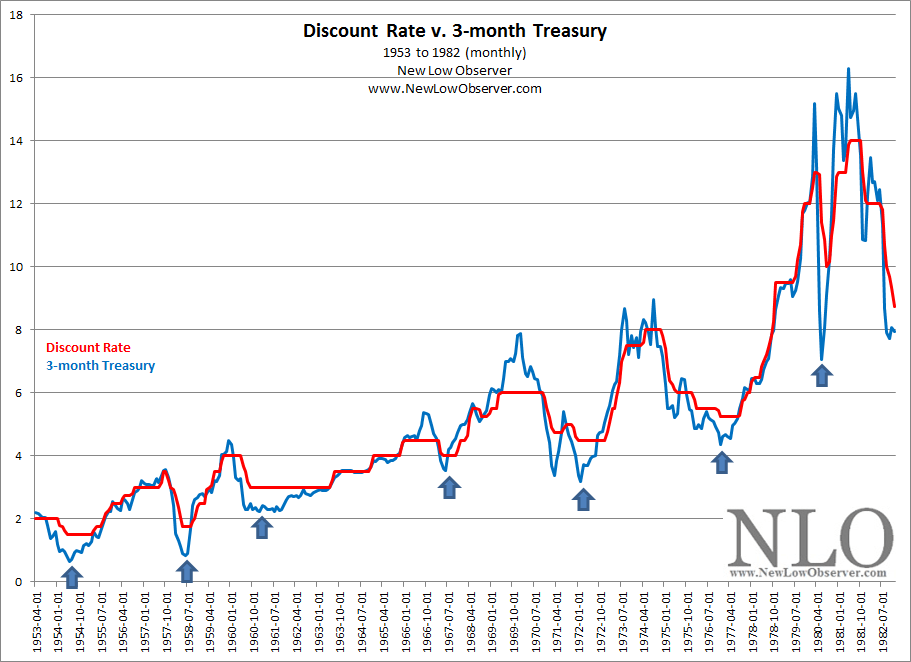
However, history is on our side on this matter.  As pointed out in previous postings, Federal Reserve rate policy always follows the actions of short-term rates as demonstrated in the last comparable cycle in interest rates from 1953 to 1980.

image