Category Archives: Interest Rate Monitor

Interest Rate Monitor: September 2020

Secular Trend Review

We have been consistent in our view that the secular trend in interest rates is up rather than down and that increasing interest rates are good for the market.  Our view preceded the Federal Reserve’s policy of rate increases starting December 15, 2015.

  • “A single rate increase by the Federal Reserve in no way makes for a trend.  However, markets often lead the way and what initially seems “bizarre” is only a natural change in regime, a change that we haven’t seen since the early 1940’s (December 16, 2015.).”

  • “We’ve only included the point in the interest rate cycle that corresponds to the phase that we are entering, coming from an all-time low to an eventual all-time high (November 15, 2015.).”

  • “Investors anticipating a general rise in interest rates should feel some comfort in knowing that most manager(s) in the utility sector are ready for what is to come.  Rising interest rates are not an automatic death sentence for utility stock prices or earnings.   In fact, the early stages of rising interest rates may see utility stocks match or exceed the returns of non-interest rate sensitive stocks, on a total return basis.  Only when the outlook is cloudy will it become difficult to offer projections that are in line with prior expectations (September 4, 2014.).”

Cyclical Trend Review

In spite of the secular trend, we have also called the rate decline based on “price action” irrespective of the talk about what the Fed should or shouldn’t do.

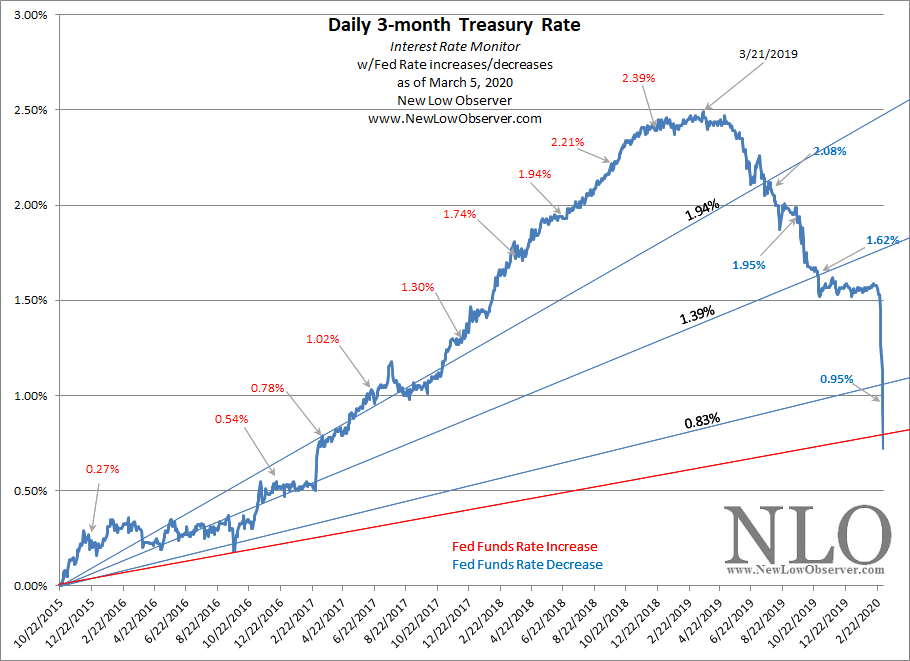
  • On January 23, 2019, we provided our first downside targets for interest rates.  At the time, we had the 3-month treasury slated for a potential downside (in the extreme) of 0.83% from the level of 2.45%.

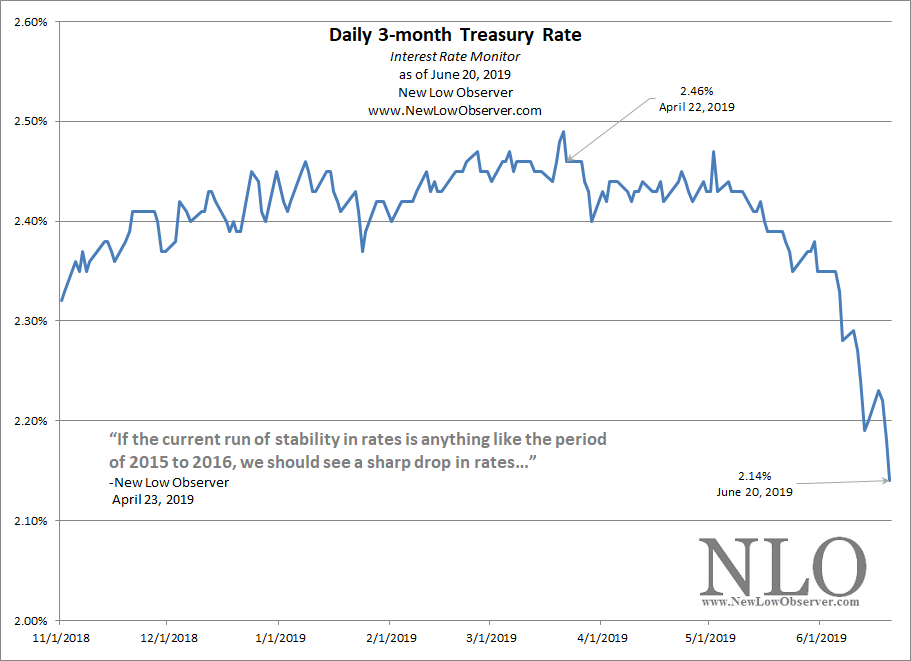
  • On April 23, 2019, with the 3-month Treasury at 2.45%, we said the following: “If the current run of stability in rates is anything like the period of 2015 to 2016, we should see a sharp drop in rates as was seen in the period from September 12, 2016 to September 22, 2016.  At that time, the 3-month treasury dropped from 0.37% to 0.18%, a decline of -51%.”

  • On December 6, 2019, with the 3-month Treasury at 1.53%, we said: “If the November 1, 2019 low, at 1.52%, is broken then we can reasonably expect at least another decline to the 1.30% level and maybe more before another rate cut by the Federal Reserve.”

  • On March 3, 2020, when the 3-month Treasury sat at 0.95%, the Fed decided to do an “emergency cut” in interest rates.

  • On March 16, 2020, when the 3-month Treasury sat at 0.24%, the Fed cut rates to zero.

All of the actions of the Fed were preceded by the change in the overall trend of the 3-month Treasury.  Our take on what is next is below. Continue reading →
Rising Secular Trend in Interest Rates

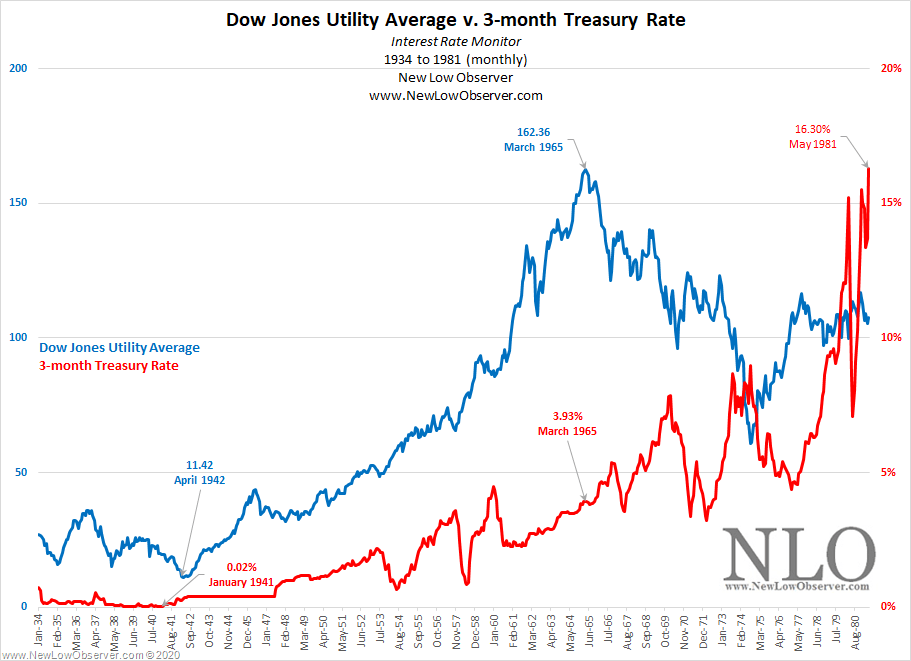
As we have long advocated, the declining trend in interest rates is coming to an end and the secular trend in rates is up.  To provide a decent level of analysis on what might happen going forward, we have a comparison of the Dow Jones Industrial Average to the 3-month Treasury from 1934 to the peak in May 1981.

image

Conventional wisdom says that as interest rates rise then stocks should underperform.  However, when contrasted to the interest rate sensitive Dow Jones Utility Average, we see that the index increased +1,321% from the April 1942 low to the March 1965 peak.

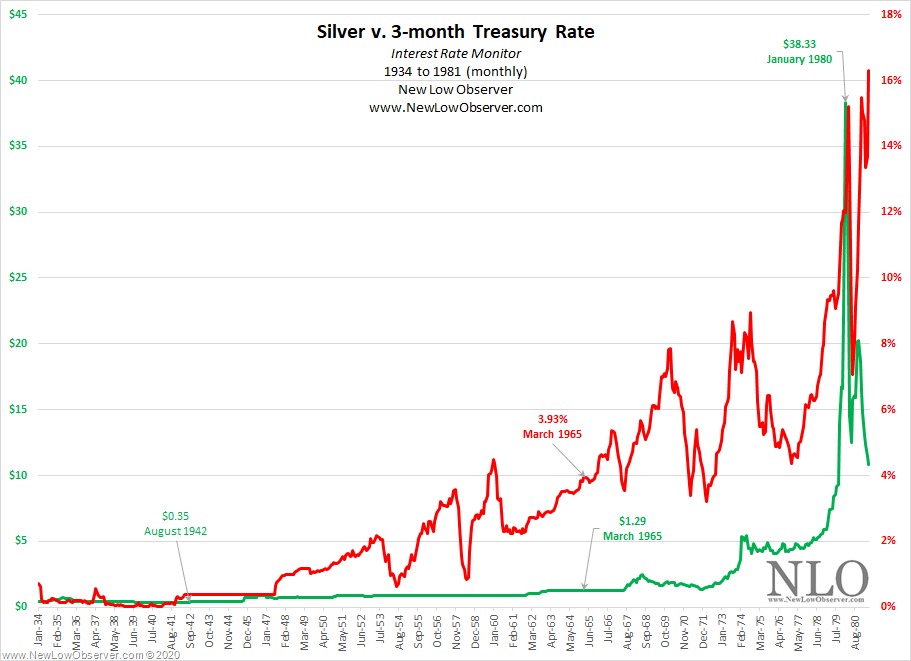
We contrast the change in the Dow Jones Utility Average to the 3-month Treasury to highlight what happened to the price of Silver in the same secular trend.

image

Historically, it is understood that rising interest rates mean rising commodity prices.  In the last secular trend, the price of silver increased modestly until, in the late stage of the cycle, all commodity prices go wild.  We believe that such a trend is likely to occur again.

Our general conclusion on the secular trend in rising interest rates is that the best alternative in the initial stages is stocks and commodities in late stage of the same trend.

“For the past 25 years the commodity market and the stock market have moved almost exactly together. The index number representing many commodities rose from 88 in 1878 to 120 in 1881. It dropped back to 90 in 1885, rose to 95 in 1891, dropped back to 73 in 1896, and recovered to 90 in 1900. Furthermore, index numbers kept in Europe and applied to quite different commodities had almost exactly the same movement in the same time. It is not necessary to say to anyone familiar with the course of the stock market that this has been exactly the course of stocks in the same period ( source: Dow, Charles H. Review and Outlook. Wall Street Journal.February 21, 1901.)”

Interest Rate Monitor: March 2020

For the last 40 years, interest rates have been in decline.  So people can be forgiven when they have the view that the trend is down, it should be down, and if it ever goes up and something goes wrong then the solution must be to cut interest rates.

Unfortunately, during a secular rising trend, cutting interest rates aren’t the solution. Worse still, falling rates ARE THE PROBLEM.  Adding QE and stimulus to rate cuts compounds an already bad situation.

Review

We have been unanimous in our view that the secular trend in interest rates is up rather than down and that increasing interest rates are good for the market.  Our view preceded the Federal Reserve’s policy of rate increases starting December 15, 2015.

  • “A single rate increase by the Federal Reserve in no way makes for a trend.  However, markets often lead the way and what initially seems “bizarre” is only a natural change in regime, a change that we haven’t seen since the early 1940’s (December 16, 2015.).”
  • “We’ve only included the point in the interest rate cycle that corresponds to the phase that we are entering, coming from an all-time low to an eventual all-time high (November 15, 2015.).”
  • “Investors anticipating a general rise in interest rates should feel some comfort in knowing that most manager(s) in the utility sector are ready for what is to come.  Rising interest rates are not an automatic death sentence for utility stock prices or earnings.   In fact, the early stages of rising interest rates may see utility stocks match or exceed the returns of non-interest rate sensitive stocks, on a total return basis.  Only when the outlook is cloudy will it become difficult to offer projections that are in line with prior expectations (September 4, 2014.).”

Current Rate Environment

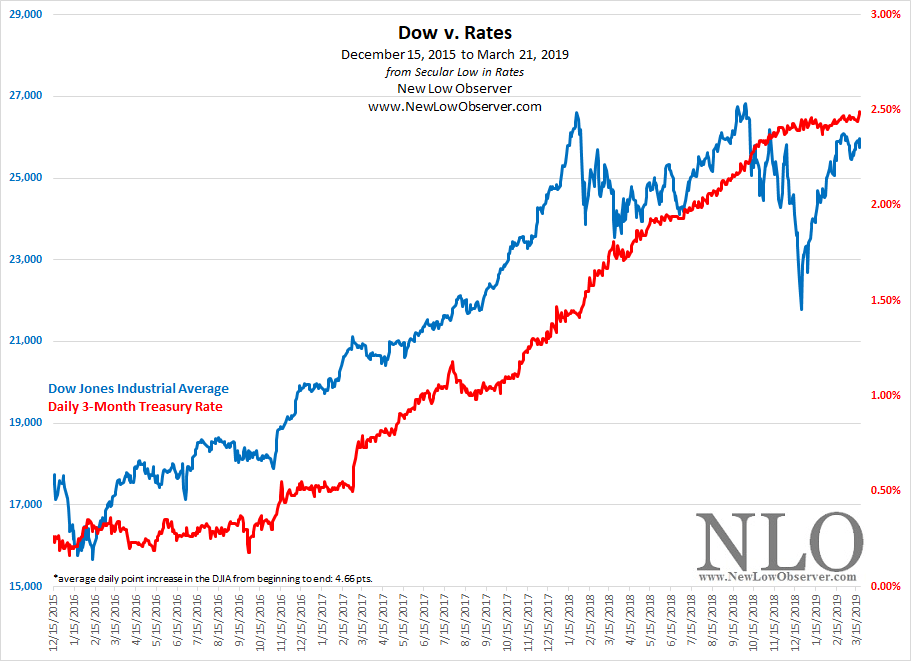
As we have stated well before rates started to increase, in a secular rising trend in interest rates, going up will be good for stocks and the economy.  What this also means is that in a secular rising trend in interest rates, going down will be bad for stocks and the economy.  We have depicted the change below.

Rates Going Up

image

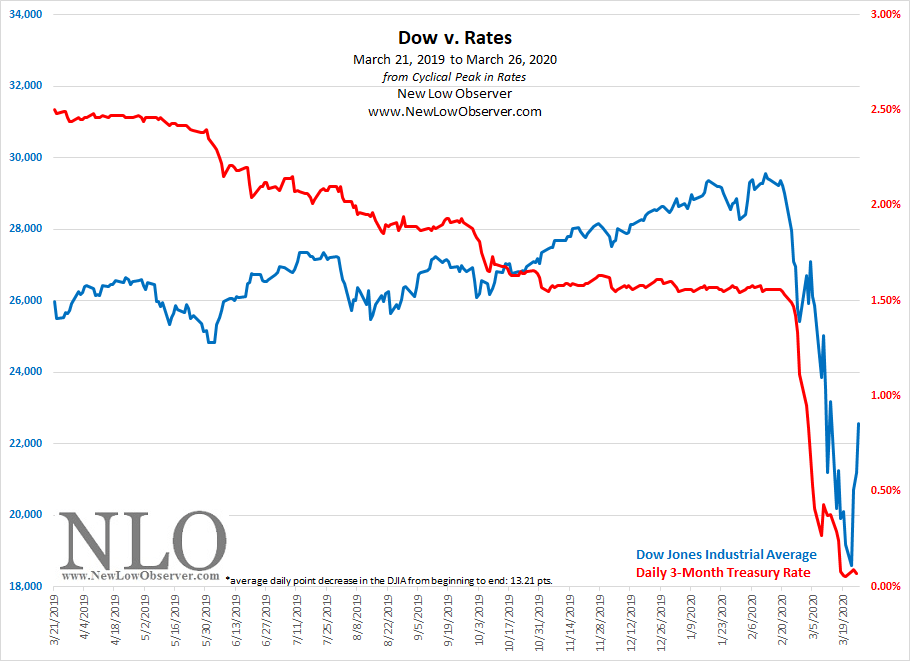
Rates Going Down

image

We have used the Daily 3-Month Treasury for one simple reason, when it goes up or down, the Federal Reserve ALWAYS follows.

Conclusion

The door has been closed on the rate cutting tool that the Federal Reserve has wielded like a force field against any perceived threat to the economy.  However, the reality is that we’re in a secular rising trend in interest rates. ANY additional stimulus (fiscal or monetary) should be looked upon as prolonging the problem rather than improving or fixing the problem.

Interest Rate Monitor: March 2020

Review

  • On January 23, 2019, we provided our first downside targets for interest rates.  At the time, we had the 3-month treasury slated for a potential downside (in the extreme) of 0.83% from the level of 2.45%.
  • On April 23, 2019, with the 3-month Treasury at 2.45%, we said the following: “If the current run of stability in rates is anything like the period of 2015 to 2016, we should see a sharp drop in rates as was seen in the period from September 12, 2016 to September 22, 2016.  At that time, the 3-month treasury dropped from 0.37% to 0.18%, a decline of -51%.”
  • On December 6, 2019, with the 3-month Treasury at 1.53%, we said: “If the November 1, 2019 low, at 1.52%, is broken then we can reasonably expect at least another decline to the 1.30% level and maybe more before another rate cut by the Federal Reserve.”
  • On March 3, 2020, when the 3-month Treasury sat at 0.95%, the Fed decided to do an “emergency cut” in interest rates.
  • On March 4, 2020, the 3-month Treasury sits at 0.72%.

Update

Slow and steady is the pace of our analysis.  So far, we’re on track.  The chart below says it all.

image

Interest Rate Monitor: December 2019

On October 7, 2019, when the 3-month treasury sat at 1.75%, we said the following:

“Tentatively, we expected the 3-month Treasury will decline into the range of 1.62% to 1.39%.”

By October 30, 2019, the Federal Reserve lowered rates when the daily 3-month Treasury was at 1.62%.  Since that time, a pattern has emerged which is worth a quick take. Continue reading →

Interest Rate Monitor: October 2019

On November 21, 2015, we said the following:

“While a Fed rate increase is what everyone is waiting for, history suggests that Fed policy  (government regulated) follows short-term Treasuries (market driven).”

We made the commentary because we saw that the 3-month Treasury rate was advancing higher.

Since that time, we’ve watched as the Federal Reserve Bank continues to followed the short-term market rates both up and down.  After the November 21, 2015 posting, we saw, in December 15, 2015, the Federal Reserve increase the Fed Funds Rate for the first time since June 29, 2006.  Again, the Fed Funds Rate increase followed the action of 3-month Treasury.

As with the rate increases in the 3-month Treasury followed by the Fed Funds Rate shortly thereafter, so too did we see the Fed Funds Rate decline after the 3-month Treasury reversed to the downside.  As we said in our April 23, 2019 posting:

“If the current run of stability in rates is anything like the period of 2015 to 2016, we should see a sharp drop in rates…”

image

The chart above highlights the point of our April 23, 2019 claim relative to the actual rate activity that has followed.  Most important is the fact that Fed Funds Rate policy did not take place until four months after the peak in the 3-month Treasury.  Even after the rate decreased in July 2019, it was clear that the Fed would have to catch up for lost ground which is reflected in the September 18, 2019 rate cut.

Below are the targets that we have set for the 3-month Treasury which will be reflected, in direction only, with the Fed Funds Rate. Continue reading →

Interest Rate Monitor: June 2019

On April 23, 2019, we said the following of interest rates:

“If the current run of stability in rates is anything like the period of 2015 to 2016, we should see a sharp drop in rates…”

At the time, rates had been in a trading range, as seen below.

image

The drop in the 3-month Treasury has been nothing short of phenomenal.  However, the question on everyone’s mind is, how far down?  We attempt to address this in the following commentary. Continue reading →

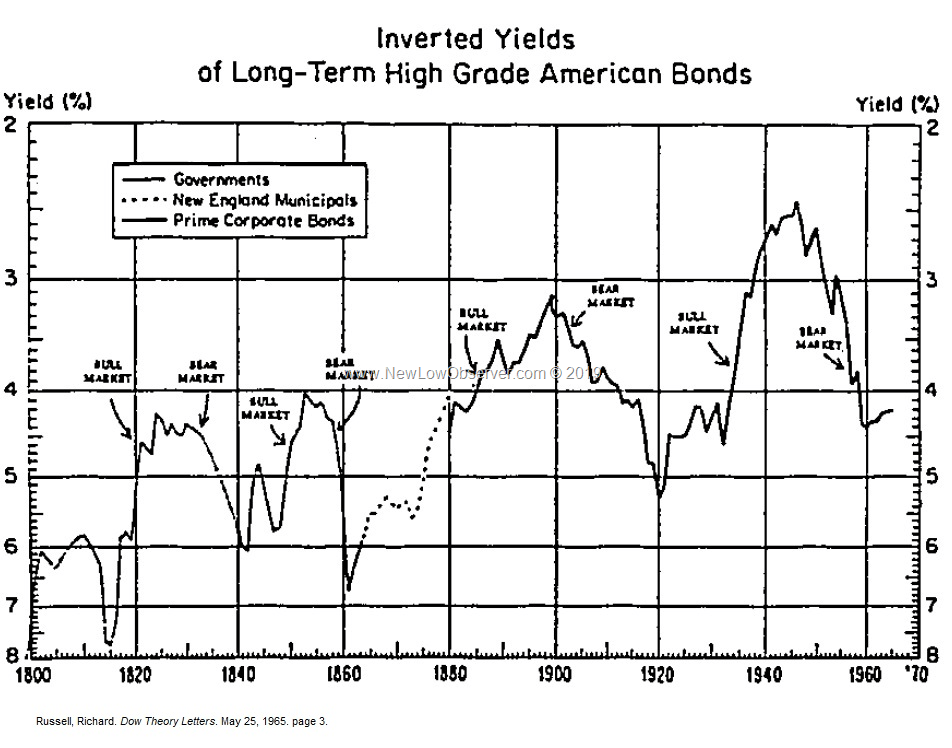
Chart of the Day: Inverted Yields from 1800 to 1965

Below is a chart of inverted yields of American bonds as published in Richard Russell’s Dow Theory Letters on May 25, 1965.  What is most conspicuous about this chart?  The overall trend of lower highs (yields) and lower lows (yields).

image

Interest Rate Monitor: April 2019

Below are the downside targets for the 3-month Treasury from the beginning of the Fed’s interest rate increasing campaign. Continue reading →

Interest Rate Monitor: January 2019

Below are the downside targets for the 3-month Treasury from the beginning of the Fed’s interest rate increasing campaign. Continue reading →

Interest Rate Monitor: November 2018

On November 21, 2015, we said the following:

“While a Fed rate increase is what everyone is waiting for, history suggests that Fed policy  (government regulated) follows short-term Treasuries (market driven).

image

“In a barely perceptible way, the chart above demonstrates that all Federal Reserve rate increases were preceded by a rise in the 3-month Treasury.  The blue arrows indicate the reversal in the declining trend before 3-month Treasuries increased.  From this point, we can easily see that the Federal Reserve’s discount rate follows to the upside not long after.  We’ve only included the point in the interest rate cycle that corresponds to the phase that we are entering, coming from an all-time low to an eventual all-time high.”

We are clearly in the early stages of a secular rising trend in interest rates.  As noted above, the direction is up for the foreseeable future.  What concerns us now, as always, is the cyclical declines which can be dramatic.   Below we trace out the first decline in the previous secular trend and see what that would look like in the current rate environment. Continue reading →

Interest Rate Monitor: October 2018

On September 26, 2018, the Federal Reserve Bank increased interest rates.

image

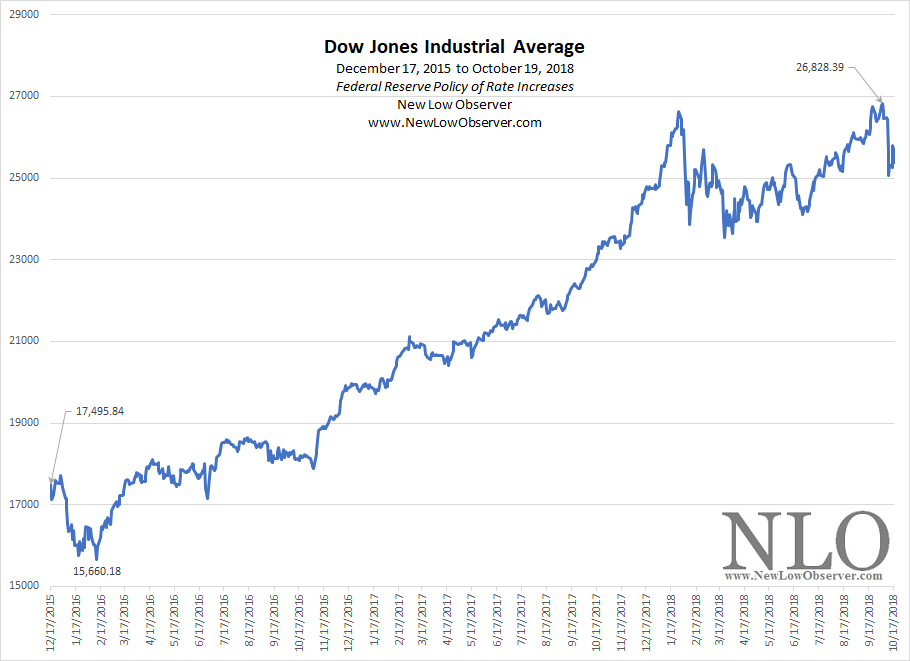
How has this policy of rate increases affected the stock market? Since the first rate increase after the “financial crisis” on December 17, 2015, the Dow Jones Industrial Average has defied the scaremongers who assert that rising rates will crash the market.

image

The Dow is up +45% since the rate increasing policy began.

How is it possible that the Dow Jones Industrial Average is up so much in spite of eight consecutive rate increases?  Why have the scaremongers been so wrong? Two key articles that we’ve written address this perplexing issue and anticipated much of what we’re seeing in the current rise of the market with rising interest rates.

The first article, published April 20, 2011 titled “The Myth of ‘Inflation Proof’ Stocks” highlighted the performance of the Dow Jones Industrial Average from 1940 to 1966 while the 3-month Treasury increased from 0.01% to as high as 4.59%.  In that period, the DJIA increased more than +900%.

The second article, published September 4, 2014 titled “Utility Stocks and Rising Interest Rates” flipped the script on the scaremongers by contrasting the performance of interest rate sensitive stocks against the backdrop of a rising rate environment.  Like the Dow Jones Industrial Average, the Dow Jones Utility Average increased more than +500% in the period from 1939 to 1966.  As a bonus, we included the earning and stock performance of seven regional utilities from 1949 to 1953.

Below is the 3-month Treasury and the upside resistance levels that we’re watching for a possible pullback from the rising trend. Continue reading →

Interest Rates and the Dow

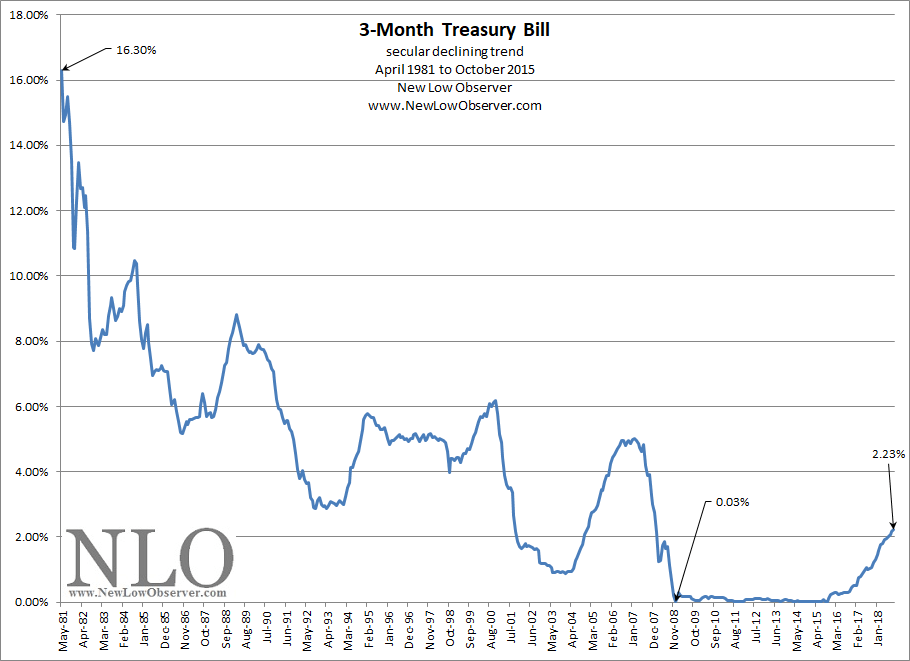
The secular trend for interest rates is clearly up after declining since April 1981.

image

There are “experts” on the topic of interest rates and the stock market claiming that the Federal Reserve policy of “artificially low” interest rates is the reason the stock market is up since the low of 2009 and as a supplemental proof of their lack of knowledge, the “experts” include the Dow increase from the 2001-2003 lows as the devil’s handiwork.  These same “experts” also claim that the stock market will crash if rates start to go up.

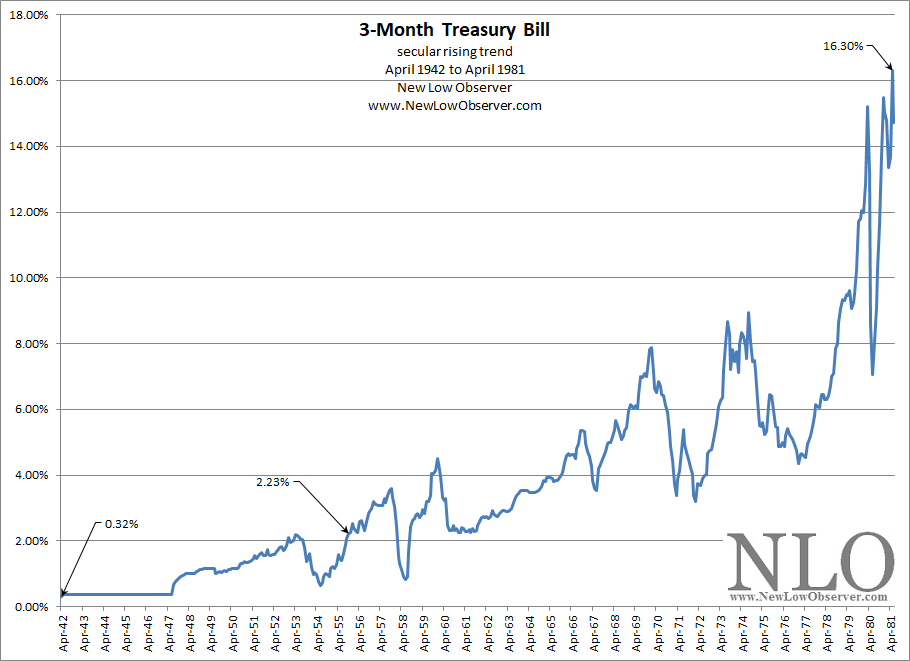
Yes, stocks can go down as a function of rising rates.  However, this needs to be put in context of the overall market.  As we start to emerge from a secular declining trend, from 1981 to 2008, to a secular rising trend, from 2008 to 2035,  the only comparisons of the current rising trend can only be done to the last secular rising trend from 1942 to 1981.

image

The “experts” claim this time is nothing like the postwar economy that led to the rate peak in 1981.  We’ll have to wait and see, for now the following data stands in opposition of the “experts.” Continue reading →

Interest Rate Monitor: September 2018

In this posting, we’ll continue on a theme that we’ve outlined since December 16, 2015, when we said:

“A single rate increase by the Federal Reserve in no way makes for a trend.  However, markets often lead the way and what initially seems ‘bizarre’ is only a natural change in regime, a change that we haven’t seen since the early 1940’s.”

The change “…that we haven’t seen since the 1940’s” is the secular trend in interest rates to go from an extremely low level to the opposite end of the spectrum, potentially to high double digit levels.  Our September 4,2014 posting suggested that:

“Investors anticipating a general rise in interest rates should feel some comfort in knowing that most manager in the utility sector are ready for what is to come.  Rising interest rates are not an automatic death sentence for utility stock prices or earnings.   In fact, the early stages of rising interest rates may see utility stocks match or exceed the returns of non-interest rate sensitive stocks, on a total return basis.  Only when the outlook is cloudy will it become difficult to offer projections that are in line with prior expectations.”

We have been consistent in the belief that the secular trend in interest rates is higher instead of lower.  With this in mind, we are presenting our upside targets (resistance levels) for the daily 3-month Treasury rates.  We use the daily 3-month Treasury rates simply because it precedes all Federal Reserve rate increases and decreases since 1934 (100%).

Continue reading →

Interest Rate Monitor: August 2018

Last year, we said the following of interest rates:

“When it comes to financial markets, the trend is your friend.  In the case of interest rates, more specifically the 3-month Treasury, the trend is up.”

At the time, the daily 3-month Treasury rate was at 0.98%.  Today, the 3-month Treasury sits at 2.05%, more than double the level from last year.

Continue reading →