Category Archives: 50% principle

Lam Research: Fighting Gravity

On September 27, 2017, we said the following of Lam Research (LRCX):

“Our view is that all parabolic moves are met with entropy.  This should bring a breakdown in the stock price to at least the conservative downside target of $90.43.  This isn’t a wish, it is based on the historical pattern in the price as previously indicated.”

Since September 2017, LRCX has increased from $177.12 to as high as $228.65, a change of +29%.  However, as of August 10, 2018, LRCX sits at $178.10, a change of +1% from the September 2017 posting.  Our belief is that the downside targets for LRCX are still in play based on the Speed Resistance Lines [SRL] that we propose.  Below is the updated SRL along with a Dow Theory consideration of upside targets.

Continue reading →

Bitcoin: April 2018

On February 17, 2018, we said of Bitcoin:

“…before a new high (substantially above the $19,343) is achieved, we expected a retest of the $6,914.26 level (or something close, like, $7,000-$7,200).”

We will continue to revisit the parts where we got the analysis right because this is where Dow Theory was correctly interpreted.  Below is the charting of the February 5, 2018 low and the subsequent rise and the retest of the low on April 1, 2018.

Bitcoin Upside Targets

Like Ethereum, Bitcoin is rebounding nicely from the February 5, 2018 low.  Below are the upside targets for Bitcoin:

Ethereum Upside Targets

As Ethereum recovers from the low set at $695.08 on February 5, 2018, the expected upside targets are as follows:

Mercury General: Targets and Perspective

On August 14, 2012, when Mercury General (MCY) was trading at a price of $37.30, we said the following:

According to Morningstar.com, MCY is considered a “buy” at $31 and at fair value at $45.  Our own model suggests that MCY is significantly undervalued at $39 and a “buy” at $45. Investment Quality Trends (www.iqtrends.com) indicates that when MCY is at a yield of 4.5% or higher, the stock should be considered for purchase.  Currently, MCY has a dividend yield of approximately 6.60%.  Keep in mind that we do not buy stocks for their dividend yield.  Instead, we use the company’s consistently increasing dividend as the only proof that the company management can:

  • increase earnings over time
  • reward current shareholders

Since that time, we’ve seen Mercury General increase from $37.30 to as high as $64.52.  Along with the increase in price, we’ve been forced to revise our perspective on the stock.  Below, we will outline the revisions to our perspective and provide target prices we think MCY should be considered for acquisition.

Details of the Ideal Transaction

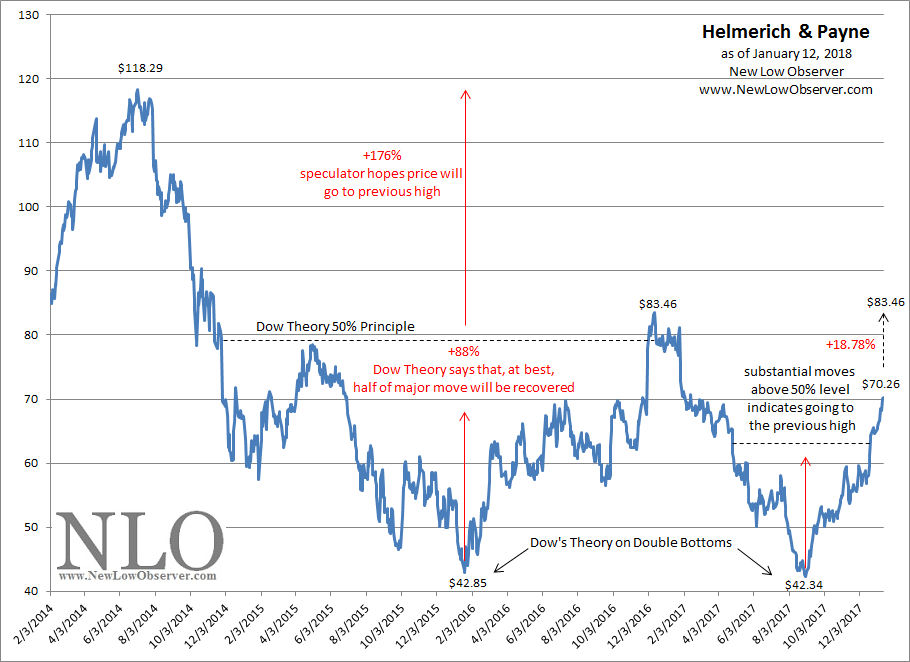
On January 12, 2016, we took a position in Helmerich & Payne (HP) at $47.41.  At the time, HP was coming off of a high of $118.29.

According to Dow Theory, an investor should only expect one half of the previous move.  With this in mind, we charted an upside target of approximately $79.16 as the likely point for selling the stock as outlined in our July 2, 2016 posting.

On January 13, 2017, we sold our holdings in HP at $78.31 for a gain of +74%. For reasons unknown, HP declined from $78.31 to $43.02 by September 1, 2017, a decline of –45%.  An outline of the change from February 3, 2014 to January 12, 2018 is charted below.

image

The Rationale

Naturally, this is the most ideal transaction that we could engage in.  Below we will lay out our observations on how we accomplished this task.

First and foremost, Helmerich & Payne is a high quality oil and gas driller that survived the crash that was experienced after the 1970’s.  In our view, if a company can increase their dividend over many years and survive a period that put a lot of competitors out of business, then you’re dealing with a good management team.  What follows are the details that we are looking at.

Continue reading →

The Definitive Dow Theory on Gold

Dow Theory attempts to define and identify major moves in markets referenced here as the “primary trend.”  In this piece, we will outline the price of gold according to Dow Theory.

We’re going to review and analyze the primary trend that extends from the September 2011 peak to the currently established low in the price of gold in December 2015.  We believe that this information is critical to understanding where we are and where we might be going.  This interpretation is based on the work of Charles H. Dow, co-founder of the Wall Street Journal and namesake to the longest continuous stock market indexes.

Keep in mind that all of the analysis that follows is done in generalities so that an individual who is curious about Dow Theory can refer to the technical manual on the topic titled The Dow Theory by Robert Rhea.  However, the true heart of Dow’s theory is found in his original writing which covered the topic of earnings, dividends, effect of dilution of shares and economic outlook AND NOT lines on a chart.  Two books that cover Charles H. Dow’s work as a fundamental analyst and an adept economist are titled Dow Theory: Unplugged and Charles H. Dow: Economist, respectively.

A Look Back

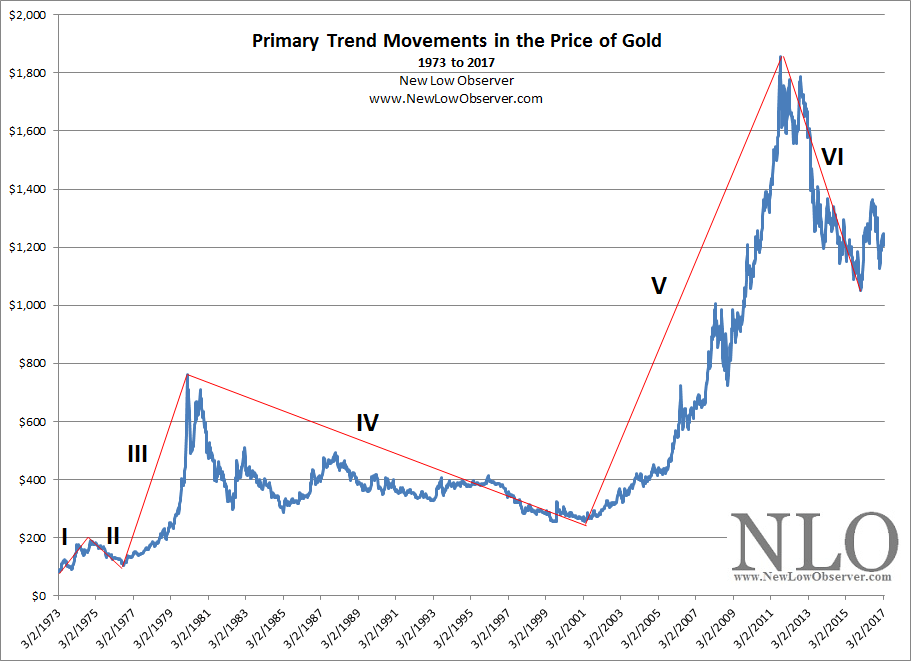
It is necessary to outline the history of primary trends in the price of gold to ensure clarity of where we are coming from and where we might be now.  Below is a graph of the price history of gold with the primary trends.

image

The dates for the primary trend indication are as follows:

  • December 1969 at $35.17
  • December 1974 at $188.25
  • August 1976 at $104.20
  • January 1980 at $760
  • August 1999 at $255.35
  • September 2011 at $1,895
  • December 2015 at $1,049.40

The percentage change for the primary trend indications above are as follows:

  • I: +435%
  • II: -45%
  • III: +629%
  • IV: -66%
  • V: +642%
  • VI: -45%

Dow Theory Primary Trend Analysis at VI

UNP: What to Watch

On January 26, 2016, we posted an article about Union Pacific Corporation (UNP).  In that article, we made the case for the stock based on the distinction between a parabola and stock cycles.  The basis for our claim lies in the work of Charles H. Dow’s view on how and when to use market data.  According to Charles Dow:

"The point of importance for those who deal in industrial stocks is whether the capitalization of the companies into which they propose to buy is moderate or excessive, when compared with the aggregate earnings of the various concerns forming the combination in a period of depression. It is probable that consolidated companies will be able to earn as much in the next period of low prices as the companies forming the combine were able to earn in the last one; hence the very foundation of investments in industrials should be knowledge of what these companies earned, say in 1893 to 1896, making, perhaps, reasonable allowances for economies under consolidation. Where the earnings so shown would have provided dividends for industrials now active, the fact must be regarded as a very strong point in favor of those stocks (George W. Bishop Jr., Charles H. Dow: Economist, Dow-Jones & Company,Princeton, 1967, page 11.)"

Essentially, Dow suggests that the most compelling data is derived from when the stock experiences its worst performance, generally during a prior recession or depression low.  Looking at UNP from 1980 to 2015, we determined that the six periods (from peak to trough) in the stock price was more instructive than taking into account the entire period as a whole.  Our conclusion:

“The repeated pattern of declines greater than –30% is no coincidence.  These are the apparent cycles that UNP happens to experience. Furthermore, the level of consistency for UNP to decline on average –48% over the period from 1980 to 2008 (7 data points) indicates that this is very useful in determining what is “normal” for the current decline in the stock price.  Already UNP has fallen –43.16% which is generally in the sweet spot as we believe that the 2008 and 1980 declines were outliers in especially painful recessions.”

Since our January 26, 2016 article, Union Pacific Corporation (UNP) has increased in price by +57%.  Now, it must be said that such astronomical returns by a hum drum railroad company should not be expected to be normal.  At some point, there will be a reversion to the mean which includes the possibility of the stock price stagnating while the Dow Jones Transportation Index increases or declines at a greater rate than the Dow Jones Transportation Index in the next bear market.  That being said, let’s look at what to watch going forward.

Dow Jones Downside Targets

Below are the downside targets for the Dow Jones Industrial Average applying Dow’s Theory and the Dow Jones Transportation Average applying Edson Gould’s Speed Resistance Lines.

Review: HP Achieves Downside Target and Rebounds

On September 14, 2015, we posted to our site an article about Helmerich & Payne (HP).  At the time we had the following investment conclusion:

“We advise that investors consider HP at the ascending $39.43 level or below.”

HP fell to the level indicated in our posting and has since increased +37% from the article date and +50% from the date of when the stock crossed below the ascending $39.43 level.  Below is the updated Speed Resistance Lines and our perspective on the potential for the stock going forward.

Dow Theory: Did Microsoft Overpay for LinkedIn?

The question has come up about whether or not Microsoft (MSFT) has overpaid for LinkedIn (LNKD).  We’re going to apply Dow Theory to determine what would have been considered the fair value for LNKD based on the stock price. Next, we're going to see how much or how little MSFT paid for LNKD.

First, we need to establish what Dow Theory considers the fair value.  According to S.A. Nelson, fair value is determined when…

"...stocks have recovered after artificial depression and relapsed after artificial advances to the middle point which represented value as it was understood by those who bought or held as investors."

The idea of “…bought or held as investors…” is very important as it reflects individual (or institutional) money that has decided to buy a stock with the expectation of holding for an extended period of time, usually 5 years or more.

Artificial Advance and Depression

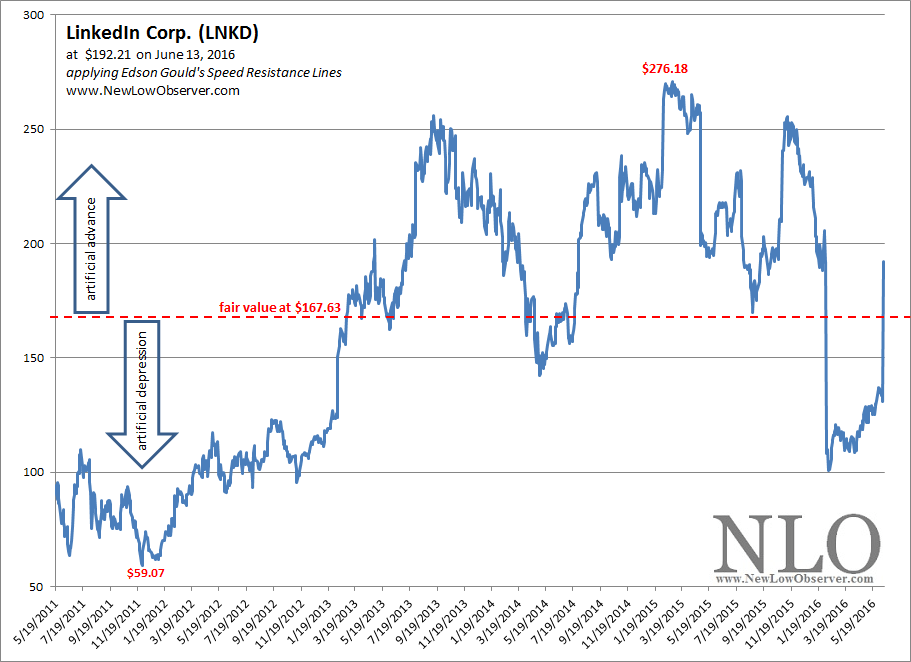
When looking at the price movement of LinkedIn, it is easy to identify the artificial advances and depressions.  However, to determine the fair value, a price which long-term holders of the stock have, on average, acquired the stock, we look to the middle point.

In order to determine the middle point (fair value), based on Dow Theory, we look at the previous major advance from the low to the high in the stock price.  The previous low was $59.07 and the previous high was $276.18.  The middle point (also know as the 50% principle) is $167.63.

image

LinkedIn Fair Value

If fair value for LinkedIn was actually $167.63 and Microsoft agrees to pay $196 per share, that would suggest a premium of 16.92%.  How does this crude methodology stack up against institutional analyst assessments of fair value for LNKD?  This from Morningstar.com:

“LinkedIn posted a better-than-expected start to 2016 as the firm beat both consensus estimates and management guidance for revenue and EBITDA, with strong performance across all three segments. We reaffirm the company's wide moat rating and our fair value estimate of $155. With shares trading just inside three-star territory in after-market trading, we would wait for a larger margin of safety before investing (source: Macker, Neil. “LinkedIn Starts 2016 By Beating Expectations, Management Remains Focused on Engagement”. Morningstar.com. 4/29/2016. accessed 6/14/2016.).”

Morningstar had $155 while Dow Theory assessed a $167.63 fair value.  Although the Dow Theory method seems arbitrary, it is based in sound reasoning which we have covered before on the topic of the 50% Principle.

So, the question becomes not “did Microsoft overpay for LinkedIn?” instead it should be viewed by “how much did Microsoft overpay for LinkedIn?”.  Based on Dow Theory, Microsoft didn’t pay much more than the company would have been worth to long term holders of the stock, in this case a premium of only 16.92%.

Richard Russell Review: Letter 859

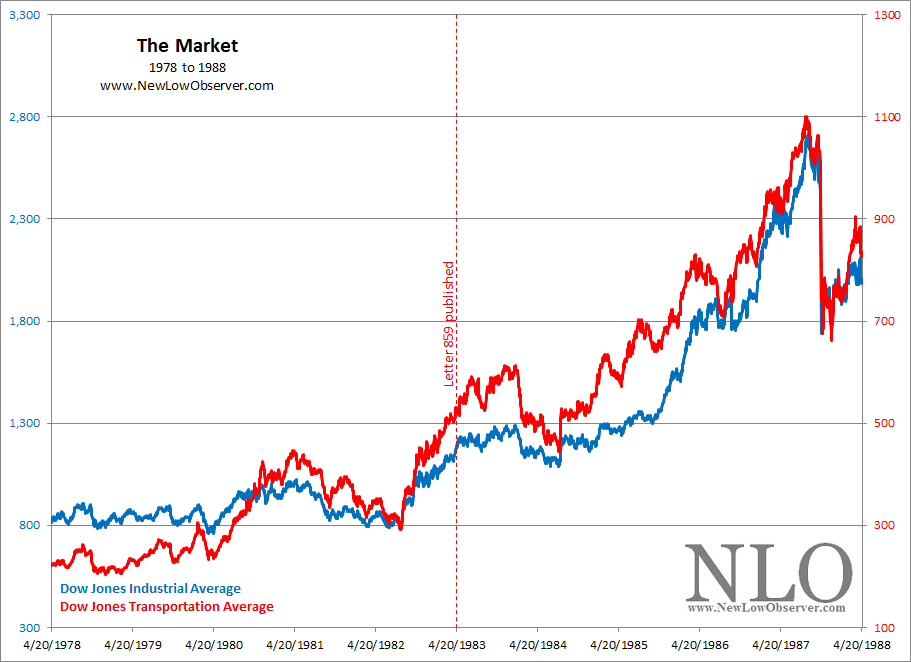
On this date in 1983, Richard Russell published Issue 859 of the Dow Theory Letter [526].  At the time, the Dow Jones Industrial Average was at the 1,191.47 level and the Transportation Average was at 531.53.

image

The following Richard Russell Review details the topics of the Elliott Wave and 50% Principles as outlined by A.J. Frost, Robert Prechter and Charles H. Dow.

Continue reading →

Gold Stock Indicator: August 14, 2015

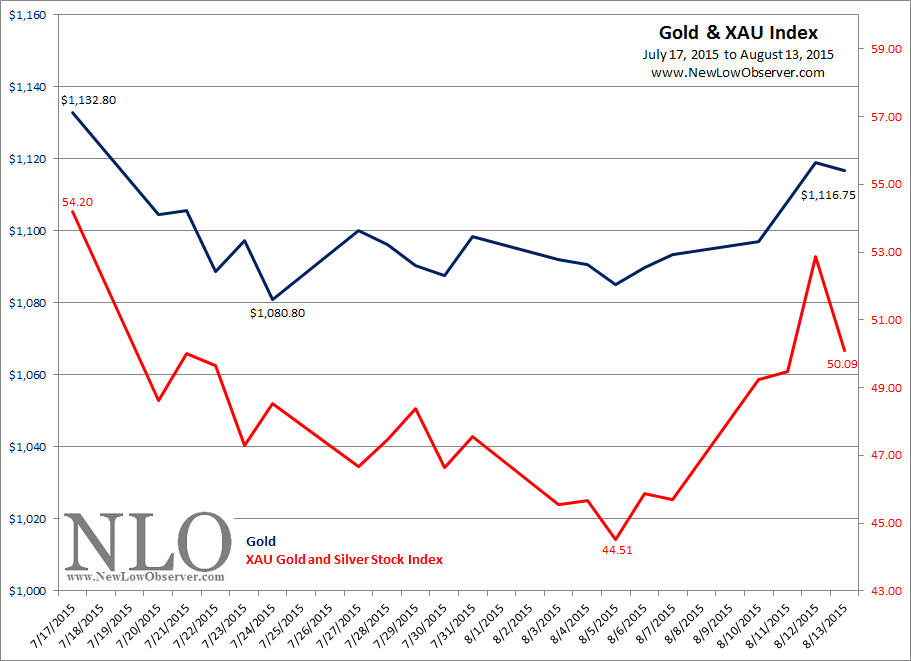
In the past month, gold and gold stocks have been on a rollercoaster ride.  Gold declined as much as –4.59% while gold stocks, as represented by the Philadelphia Gold and Silver Stock Index (XAU), declined –17.88%.

image

Although there has been a recovery of sorts, we cannot be sure that the decline is over.

Scary 1929 Chart Nearly One Year Later

In February of 2014, a widely publicized chart circulated about the similarity between a 1928-1929 stock chart and a 2012-2013 chart.  According to Tom McClellan of the McClellan Market Report:

“…between now [February 11, 2014] and May 2014, there is plenty of reason for caution.”

Since February 11, 2014, the Dow Jones Industrial Average has increased +11.06%.  In the period from February 11th to May 31st the index gained +4.52%.  So far, the scary 1929 chart has not held up to the lofty claim of presaging a bear market or a even a –10% decline.  We offered up our own interpretation regarding the chart and said the following:

“We love a declining stock market as much as the next value investor. However, implying that an -89% decline is in the works because the pattern appears similar to 1929 is ignoring the path to far more achievable downside targets.”

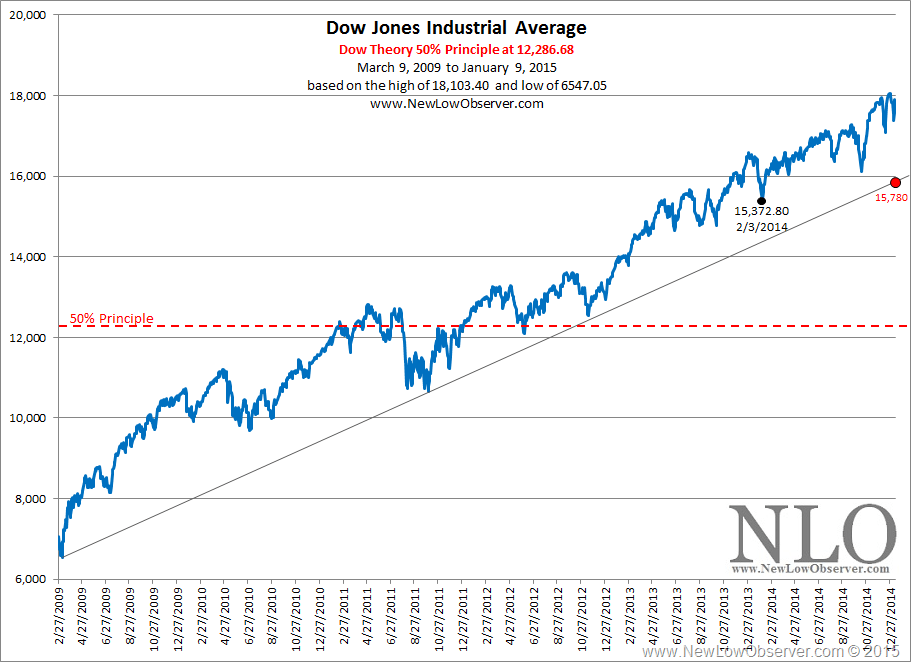
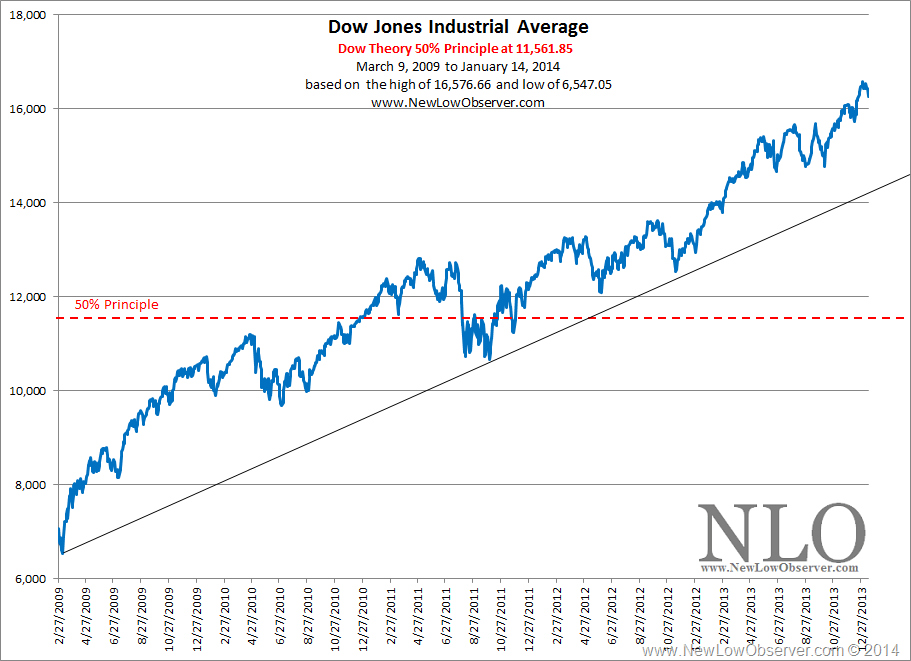
Our preliminary downside targets seemed reasonable at the time but were never achieved.  One downside target that we thought was important was the ascending trendline from the 2009 low.

image

We still think that investors should watch the ascending line in the chart above, which currently sits at the 15,780 level.  An additional downside target is the Dow Theory 50% Principle level of 12,286.68.

Dow Theory: The 50% Principle

The following from Richard Russell’s Dow Theory Letters is what we believe to be one of the most valuable examples of Charles Dow’s 50% Principle in action.   

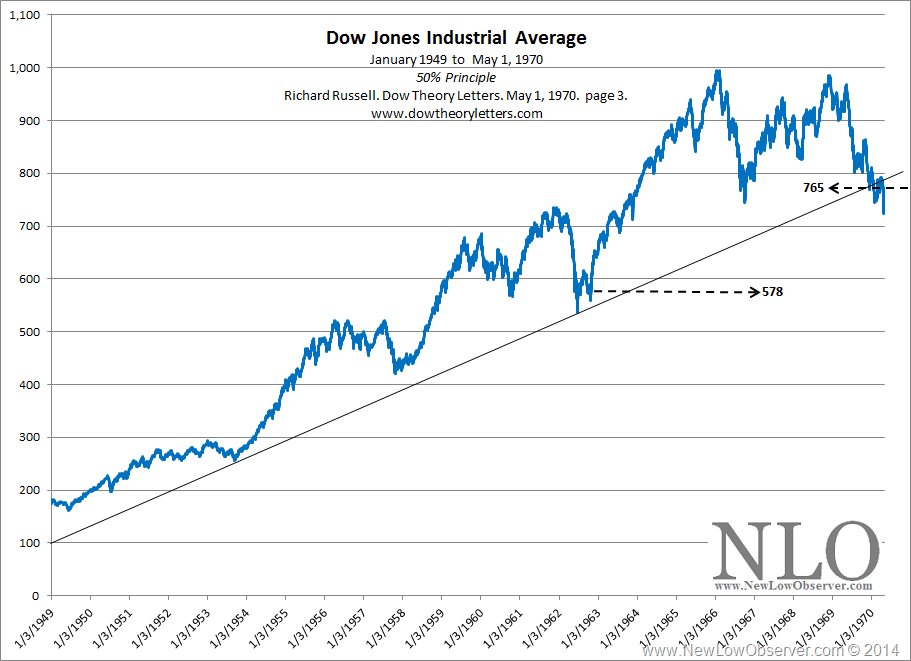
“I am publishing this arithmetic chart of the D-J Industrials (high and low monthly) from M.C. Honey, Salisbury, Md. 21801. I am using an arithmetic chart because I want to show distance or ground covered by the Dow, not percentages.

“The 50% Principle states the following: After an extended advance, the termination point of the ensuing correction should be watched carefully. If the correction can halt while retaining 50% or more of the previous advance, it is a positive indication, and there is a good chance that movement will rally to test the area of the high again. Conversely, if the correction wipes out more than 50% of the previous extended advance, it is a negative indication, and there is a good chance that the movement will continue down, ultimately testing the area from which the entire advance started.

“It should be remembered that this is a theory, and although it has worked many times in the past there is nothing immutable about this theory (or observation, if you wish to call it that). Second, the 50% Principle should not be applied to short-term movements; it should only be applied to major movements lasting six months to a year or many years.

image 

“There are two important applications of the 50% Principle which may be coming into prominence. First, referring to the chart, note that the Dow has broken the long-term trendline connecting the 1953 and 1962 bottoms. This is obviously a bearish indication, suggesting a reversal of the entire rising trend since 1949. The fact that this occurred within the framework of a primary bear markets makes the penetration of the trendline doubly significant. I do not believe, in other words, that this was a “false” penetration.

“If we measure advance, in the 1962 low of 535.76 on the Dow to the final 1966 peak of 995.15, we note that the movement carried 460 points. The halfway point of the 1962 to 1966 rise was thus 765. This means that during the 1966 and again during the most recent decline the Dow decisively broke the 50% level. The implication under the 50% Principle is that the Dow will probably test the area from which the movement began, or the 1962 area of 535. Whether this will happen remains to be seen, but at any rate that is the implication of the 50% Principle.

“The second important consideration is that the entire primary bull market covered a distance of 834 point; from the 161.60 of 1949 to 995.15 of 1966. The halfway point of the whole bull market rise is thus 578. I feel that if the Dow breaks to lower levels, it will be important to see what happens if and when 578 is approached.

“If a bottom can be formed at or above 578, particularly during a period which shows third phase characteristics, it will be a positive sign. Conversely, if 578 is decisively penetrated, I would take it as a most bearish and tragic sign. If 578 is broken decisively on the downside, my guess is that the final bottom of the bear market will arrive at an area far lower than anyone now thinks possible. (source: Russell, Richard. Dow Theory Letters. May 1, 1970. Page 3. www.dowtheoryletters.com)”

After the May 1, 1970 article by Richard Russell, the Dow Industrials had the following performance:

image

On December 6, 1974, the Dow Jones Industrial Average closed at 577.60.  After this point, the Dow Industrials never closed lower.  In the January 2, 1975 issue of the Dow Theory Letters, Russell said the following:

“Unless both Averages now break to new lows (Industrials below 577.60, Transports below 125.93) history will record October 3 as the bottom for the bear market (although December 6 will stand as the low day for the D-J Industrial Average alone).”

The 50% Principle is a necessary tool for all investors to gauge how much a decline is expected to run it’s course in the worst case scenario.  A conservative investor should make use of the 50% Principle as a means of determining downside risk.  With this in mind, the expectation is that at some point the stock (or index) will decline by nearly  –50%.  The 50% Principle sets the framework for how to interpret the price action from almost any prior peak.

In a roundabout way, even Charlie Munger, Warren Buffett’s long-time investment partner, considers the prospect of a decline by –50% in the following commentary:

“I think you can argue that if you’re not willing to react with equanimity to a market price decline of 50% two or three times a century you’re not fit to be a common shareholder and you deserve the mediocre result you’re going to get, compared to the people who do have the temperament who can be more philosophical about these market fluctuations.”

The 50% Principle Today

Below is the current 50% Principle for the Dow Jones Industrials Average.

image

While falling to 11,561.85 isn’t required, it doesn’t hurt to have a sense of the downside risk.  Additionally, as the Dow goes higher, the level for the 50% Principle will increase.  A retest of the ascending trendline should be expected at minimum.