-
Topics
Archives
-
-
Recent Posts
-
-
-
-
When, Not If, Dividends Matter
In a note on Barry Ritholtz’s The Big Picture there is an article dated October 3, 2010 that asks the age old question, “Do Dividends Matter?” The author of the article compares the performance of dividend paying stocks against non-dividend paying stocks that are constituents of the S&P 500. After selecting a period of time from December 31, 2009 to September 29, 2010, the author breaks down the analysis by separating the performance of the stocks into three distinct periods; 12/31/2009 to 9/29/10, 4/23/2010 to 9/29/2010 and 12/31/2009 to 4/23/2010.
The conclusion of the article is that whether a company pays a dividend isn’t as important as people think. However, the conclusion comes as no surprise since the period in question is less than a year and the goal was to determine the impact dividends play in the performance of a stock’s price. All measures within a year cannot reveal the same amount of impact of dividends over several decades. In a strange twist, the article proves exactly what the New Low Observer has been saying all along.
First, market performance is often measured in a year or less. As market observers, we don’t control this characteristic, we only make certain that our investment strategy reflects and caters to this fact. This “research” on Ritholtz’s site doesn’t hold up since it doesn’t even span a decade of continuous examination. An individual would do better to accept the mountains of buy-and-hold evidence; which indicates that dividends contribute more than half the total return when measured over a span of 40 years or more. Just be sure that you’ve got a 40-year investment time horizon before you act on such factual data.
Second, the performance of the dividend paying stocks in Tier 1, Tier 2 and Tier 3 over the December 31, 2009 to April 23, 2010 period, beat the non-dividend paying stocks resoundingly. Tier 3, the lowest performing of the dividend paying stocks, outperformed the non-dividend paying stocks by 2% over the given timeframe. As regular readers of our site know, we seek mediocre returns of 9%-12% from each investment. This means that we would have sold somewhere short of 20% and then moved on to the next stock. The worst performing group, Tier 5 of the dividend paying stocks, was only able to achieve 7.57% in the 4-month period. However, if Tier 5 stocks were bought and sold in the time selected, the annualized return would have been 24.41%.
Finally, low dividend yielding stocks easily outperform high yielding stocks. In the survey, Tier 1 had the lowest yielding stocks while Tier 5 had the highest yielding stocks. Tier 1, Tier 2 and Tier 3 of the dividend paying stocks in the “study” easily outperformed the market and the non-dividend paying stocks. Our article titled “Low Yielding Stocks Offer Exceptional Gains” outlined the importance of quality of dividends rather than dividend yield. We were specific in pointing out that what is lacking in yield is typically made up for in appreciation of the stock price. This is very important because most people who have been burned in their investments typically seek out alternatives that might seem to help make up for substantial losses. Unfortunately, this is the time when the markets are about to turn around and the high yielding stocks underperform on the upswing.
Again, we don’t attempt to explain why information on the markets comes in two incongruent varieties, focused in the short-term data with an inappropriate strategy or focused on long-term data that is incompatible with real world investment time frames. We only observe that, within any one-year time span a stock reaches a new low. If narrowed down to the number of companies that have a proven track record of dividend increases or are part of an index that most mutual funds are required to buy, then the odds are in your favor to obtain reasonable gains that exceed the historical market returns. This (il)logical thinking only works if you’re willing to sell in the same time frame that your analysis takes place. These factors are frequently left out of the “research” of whether dividend matter or not.
International Dividend High Fliers
Below are the top current and former international dividend high fliers that are within 20% of their 52-week low and trade as ADRs on the New York Stock Exchange. These are companies that have had a history of dividend increases over the last several years in a row according to MergentOnline.com.
| Symbol | Name | Trade | P/E | EPS | Yield | P/B | % from Low |
| IMO | Imperial Oil Ltd | 38.2 | 16.2 | 2.36 | 1.10% | 3.2 | 8.70% |
| DEG | Etablissements Delhaize Freres | 71.9 | 10.5 | 6.86 | 2.00% | 1.1 | 9.48% |
| ESLT | Elbit Systems Ltd. | 53.1 | 11.1 | 4.78 | 2.20% | 2.5 | 9.51% |
| SNN | Smith & Nephew SNATS, Inc. | 46.2 | 14.9 | 3.11 | 1.30% | 3.5 | 12.05% |
| CRH | CRH PLC | 16.7 | 16.2 | 1.03 | 2.80% | 0.8 | 13.35% |
| UL | Unilever PLC | 29.2 | 16.1 | 1.82 | 3.80% | 4.9 | 13.60% |
| TEVA | Teva Pharmaceutical Industries | 53.5 | 19 | 2.82 | 1.30% | 2.5 | 13.90% |
| UN | Unilever NV | 29.9 | 16.4 | 1.82 | 3.70% | 5 | 14.95% |
| CHL | China Mobile Ltd | 51.5 | 11.9 | 4.32 | 3.20% | 2.6 | 16.05% |
| PRE | PartnerRe Ltd | 80.5 | 5.26 | 15.28 | 2.50% | 0.9 | 16.37% |
| STO | Statoil ASA | 21.4 | 13.7 | 1.57 | 3.70% | 1.9 | 16.48% |
| TMX | Telefonos de Mexico | 15.2 | 9.61 | 1.58 | 5.10% | 4 | 16.77% |
| PBR | Petroleo Brasileiro | 36.5 | 9 | 4.05 | 0.40% | 1.6 | 16.82% |
| ALTE | Alterra Capital | 19.9 | 5.41 | 3.68 | 2.40% | 0.8 | 17.10% |
| SYT | Syngenta AG | 50.3 | 19.3 | 2.61 | 1.80% | 3.4 | 17.10% |
| NGG | National Grid Transco | 43.2 | 9.78 | 4.42 | 8.20% | 3.2 | 17.65% |
| RNR | RenaissanceRe | 59.5 | 4.28 | 13.9 | 1.70% | 1.1 | 17.84% |
| ASR | Grupo Aeroportuario del Sureste | 47.9 | 16.4 | 2.92 | 4.00% | 1.3 | 18.05% |
| SNY | Sanofi-Aventis | 33.1 | 10.6 | 3.12 | 3.30% | 1.2 | 18.24% |
| TLM | Talisman Energy Inc. | 17.5 | 24.6 | 0.71 | 1.40% | 1.6 | 18.98% |
| CWCO | Consolidated Water Co. Ltd. | 9.72 | 37.5 | 0.26 | 3.20% | 1.1 | 20.00% |
International Watch List Performance Review
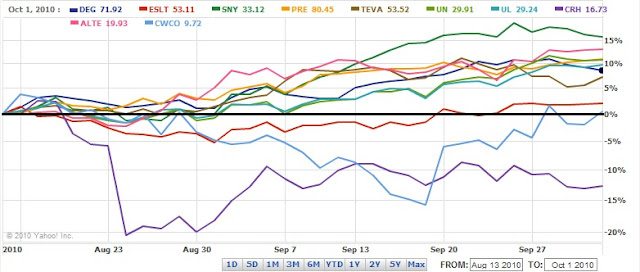
Below is the performance of the top ten companies on our International Dividend Achiever Watch List from August 13, 2010.
It is interesting to note that only two stocks, Consolidated Water (CWCO) and CRH (CRH), continued their declining trend. It remains to be seen whether or not we've witnessed the bottom for both stocks. However, the gains made from 7 of the 10 stocks has exceeded the average return for the group. If viewed from our short-sighted perspective of annualized return, the worst that could have been done would be 47.45%.
| Symbol | Name | 10/1/2010 | 8/13/2010 | % Change |
| SNY | Sanofi-Aventis SA | $33.12 | $28.64 | 15.64% |
| ALTE | Alterra Capital Holdings Ltd | $19.93 | $17.65 | 12.92% |
| PRE | PartnerRe Ltd. | $80.45 | $72.55 | 10.89% |
| UN | Unilever NV | $29.91 | $27.02 | 10.70% |
| UL | Unilever PLC | $29.24 | $26.66 | 9.68% |
| DEG | Etablissements Delhaize Freres | $71.92 | $66.30 | 8.48% |
| TEVA | Teva Pharmaceutical | $53.52 | $49.97 | 7.10% |
| ESLT | Elbit Systems Ltd. | $53.11 | $52.10 | 1.94% |
| CWCO | Consolidated Water Co. Ltd. | $9.72 | $9.68 | 0.41% |
| CRH | CRH PLC | $16.73 | $19.17 | -12.73% |
| Average: | 6.50% | |||
Investment Strategy and Timeline: Qualcomm (QCOM)
Current headlines are all about the latest and greatest gadgets like the Apple iPhone. With the news, traders flock into the stock as well as the derivatives for Apple (AAPL). Analysts recommended Verizon (VZ) over AT&T (T) because of the new growth component, the iPhone. Now the derivative traders are interested in the chip sector with companies like Qualcomm (QCOM). With the latest rumor that Apple will be dropping Infineon / Intel alliance for Qualcomm's CDMA technology, analysts and traders have suddenly fallen in love with QCOM. With this change in sentiment, Qualcomm has risen almost 18% since September 1st.
The New Low team hasn't always been right in timing the buy but we have been (somewhat) right in suggesting investors look at QCOM back in the March and April 2010 time frame. The stock appeared on our Nasdaq 100 Watch List on January 30, 2010 at $39.19. Although we didn't recommend the stock then, we tracked the stock for several months. In late March, a reader submitted a Research Request on Applied Material (AMAT) which put us to work.
At the end of that article, we came to a conclusion that AMAT was too rich for our blood and suggested QCOM as a better alternative. In addition, we offered a specific strategy on the purchase and how to allocate capital which panned out beautifully. On April 22, 2010 QCOM dropped like a rock after reporting earnings. With a recent dividend increase of 12% and a good entry point of $38, we took a position in QCOM.
For those that followed suit, they would be sitting on an 18% gain or 48% annualized gain. In addition to buying outright stock, we also incorporated an option strategy as a way to add extra cash. This strategy added 1.2% to our bottom line. In addition, QCOM paid 3 dividend payments during this time adding more to our bottom line.
Today, we have taken our gain. Although we didn't buy QCOM at the beginning of the rise in September, as we held the stock, we were paid for the wait as the dividend covered the commission. The option premiums were additional cash we took from speculators. The net return of 18% is more than enough for us to sit back, review our watch list, and wait for a better risk/reward alternative. While QCOM can certainly move to $50, an additional 10%, we can't hope or dream. We are happy to take our 18% gain and head back to the drawing board, our watch list.
Timeline:
1/30/10 - QCOM appeared on our watch list.
3/23/10 - Research Request on AMAT but we suggested QCOM.
4/22/10 - QCOM drop, possible entry point.
4/23/10 - we took position with option strategy.
7/16/10 - options expired, we sat on 3.5% loss.
9/30/10 - we have taken the 18% and go back to our drawing board, the watch list.
Email our team here.
October Ex-Dividend Dates
Below are the approximate ex-dividend dates for the month of October for companies that appear on our Dividend Achiever, Nasdaq 100, Dow Jones Transportation Index and International Dividend Achiever Watch Lists. All companies are ranked by ex-dividend dates.
Companies that show up on our Watch Lists could be considered the equivalent of the bargain bin of high quality blue chip stocks. Because these companies have increased their dividends every year for at least 10 years in a row or are part of the Nasdaq 100 and within 20% of their respective 52-week low, you know that you’re not overpaying for a company that has demonstrated profitability and the ability to rebound from challenging times.
| Symbol | Name | Price | % from low | Yield | Date |
| WFSL | Washington Fed | $14.99 | 7.30% | 1.30% | 10/5/2010 |
| ABM | ABM Industries Inc. | $21.43 | 19.45% | 2.50% | 10/5/2010 |
| MDT | Medtronic | $33.21 | 7.82% | 2.70% | 10/6/2010 |
| MAS | Masco Co. | $10.92 | 9.81% | 2.70% | 10/6/2010 |
| GD | General Dynamics | $62.50 | 12.69% | 2.70% | 10/6/2010 |
| LNC | Lincoln National Corp | $23.78 | 15.16% | 0.20% | 10/6/2010 |
| BANR | Banner Corp | $2.23 | 16.75% | 1.90% | 10/6/2010 |
| PDCO | Patterson Companies | $28.36 | 17.53% | 1.40% | 10/6/2010 |
| MMC | Marsh & McLennan | $24.02 | 18.85% | 3.50% | 10/6/2010 |
| UVV | Universal Corp | $40.03 | 13.21% | 4.80% | 10/7/2010 |
| GBCI | Glacier Bancorp, Inc. | $14.20 | 19.23% | 3.70% | 10/7/2010 |
| SNN | Smith & Nephew SNATS | $45.10 | 9.31% | 1.30% | 10/13/2010 |
| BBT | BB&T Corp. | $24.06 | 10.77% | 2.50% | 10/13/2010 |
| ABT | Abbott Labs | $52.37 | 17.45% | 3.40% | 10/13/2010 |
| WST | West Pharmaceutical | $33.82 | 3.30% | 1.90% | 10/17/2010 |
| FUL | H. B. Fuller | $19.89 | 7.69% | 1.40% | 10/18/2010 |
| LOW | Lowe's Co. | $22.38 | 16.86% | 2.00% | 10/18/2010 |
| LKFN | Lakeland Financial | $18.29 | 11.87% | 3.40% | 10/19/2010 |
| CL | Colgate-Palmolive | $78.59 | 7.48% | 2.70% | 10/20/2010 |
| BCR | C.R. Bard | $81.71 | 10.43% | 0.90% | 10/20/2010 |
| FARM | Farmer Brothers | $15.78 | 13.20% | 2.90% | 10/20/2010 |
| CLX | Clorox Co. | $67.29 | 19.39% | 3.30% | 10/25/2010 |
| EV | Eaton Vance Corp | $28.99 | 13.24% | 2.20% | 10/26/2010 |
| NWN | Northwest Natural Gas Co. | $46.68 | 14.33% | 3.50% | 10/26/2010 |
| PNR | Pentair, Inc. | $33.16 | 17.67% | 2.30% | 10/26/2010 |
| JBHT | J.B. Hunt Transport | $35.11 | 19.22% | 1.40% | 10/26/2010 |
| WL | Wilmington Trust | $8.76 | 4.91% | 0.40% | 10/27/2010 |
| CAG | ConAgra Foods | $21.95 | 6.81% | 4.20% | 10/27/2010 |
| PAYX | Paychex | $26.93 | 9.25% | 4.60% | 10/27/2010 |
| WABC | Westamerica Bancorporation | $53.82 | 14.32% | 2.70% | 10/27/2010 |
| TEVA | Teva Pharmaceutical | $52.78 | 12.32% | 1.20% | 10/31/2010 |
| PBR | Petroleo Brasileiro | $35.75 | 14.55% | 0.40% | 10/31/2010 |
If you happen to be researching these companies for potential investment, it would be advisable to consider the ex-dividend date prior to possible purchases. Owning the shares of the company that you're interested in before the ex-dividend date entitles you to the upcoming dividend payment.
Owning the shares on or after the ex-dividend date means that you would have to wait at least three months before receipt of the next dividend payment. Please verify the ex-dividend date and payout ratio before committing funds to these stocks. Additionally, do not base your next long or short-term purchase on the dividend payment or yield. Instead, get as much research in as you possibly can before the ex-dividend date "just in case" you're actually interested in buying the stock.
Articles of Interest:
- The New Low strategy applied in Bull Markets
- Shows how eight dividend paying stocks combined to beat all indexes in one year.
- The New Low strategy applied in Bear Markets
- Outlines a single transaction that best exemplifies why 2008 finished with total returns of 14% using dividend paying stocks. (all 2008 transactions)
- The New Low Strategy applied to Nasdaq 100 stocks
- Our method applied to select members of the Nasdaq 100 outperformed the same index by 7.92%
- Low Yields, Exceptional Gains
- This article demonstrates that low yields are made up for with exceptional return. At least this applies for the Dividend Achievers that concentrate on.
On the Brink of a Secular Bull Market in Precious Metals
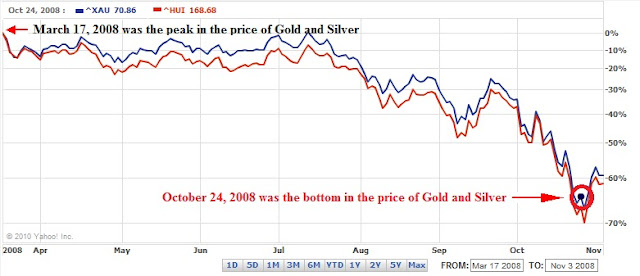
In our “Commentary on Gold” dated November 11, 2008, we made some outlandish claims about the lack of performance by three undisputed experts on gold. One claim that we made was that “…when the price of stocks fall so too does the price of gold, and to a greater degree, gold & silver stocks.” This was said after the precious metals and the XAU and HUI indexes had already hit their final lows on October 24, 2008 and October 27, 2008 respectively. We demonstrated our claim through research performed by David Marantette which showed that from 1975 to 2001, declines of 10% or more in the Dow Jones Industrial Average resulted in larger declines in the gold stock indexes and the price of gold. We completed the research by providing the data from 2001 to 2007.
The point of our December 9, 2008 article was best summed up in our closing paragraph:
“The long term trend in gold and silver stocks as demonstrated by the Philadelphia Gold Stock Index (XAU), which was initiated in November 2000, will eventually head permanently higher. The continuation of that trend will be among the key indicators that the bear market in stocks is at or near an end.”
Our overall assertion was, and is, if precious metals and their stocks continue heading higher so will the general stock market. If the stock market starts to collapse then so too will the price of gold and silver and to a greater degree gold and silver stocks.
When we wrote our earlier pieces on precious metals, gold enthusiasts argued that the physical metal and the gold stock indexes are completely unrelated and therefore it doesn’t make sense to compare the two, not realizing that we weren’t comparing them at all. Other gold enthusiasts countered that with the price of gold falling only -29% from the March 2008 high investment in that area was justified considering that the Dow and S&P 500 had fallen over -35% in 2008, not realizing that losing less money isn’t the reason why people invest. Not liking the outcome of the data, because it only covered the period from 1975 to 2007, some said that it didn’t go back far enough.To respond to the critics about our data, we gathered prices of gold and silver stocks from 1924 to 1933. That data demonstrated that gold and silver stocks got hammered during that period. Below we have included a previously unpublished Gold Stock Average of the 13 precious metal stocks (out of 21) with complete price history from 1924 to 1933.
As you can plainly see, when you exclude the performance of Homestake Mining, the value of the gold stocks fell 76.47% from their peak in 1925 to the bottom in 1932. This performance is in line with the decline of the Amex Gold Bug Index (HUI) from March 14, 2008 to October 27, 2008; which has 16 precious metal stocks in it. In the chart below, you can see that the HUI index and the Philadelphia Gold and Silver Index (XAU) fell 70.56% and 68.15% respectively, within the 8-month period.
Few people will readily agree that all the deflating of the financial system has been expunged from the markets. However, when compared to the deflation that took place from 1924 to 1932, first reflected in the gold stocks and later the entire stock market, it becomes very clear that the general stock market decline of over 50% and the eight month decline of the gold stock index on such a large scale signaled the end of the deflationary period. For investors, one area we think that holds the most promise is in silver.
On September 9, 2009 we wrote an article titled “Silver Should be the Focus.” We indicated that if there were a need to participate in the run in precious metals, silver would be the best investment/speculative choice. At the time, silver closed at $16.36 an ounce. On Friday September 24, 2010, silver closed at $21.46 with an increase of 31.17%. During the same period of time, the price of gold increased 30.61%. So far, the precious metals appear to be in lock step with each other since our last article on the topic. However, since the bottom in the market on October 24, 2008, the price of gold is up 82% with the price of silver is up 142%. Although these are considerably large increases in value in a very short period of time, compared to past price increases the current moves are in their infancy.
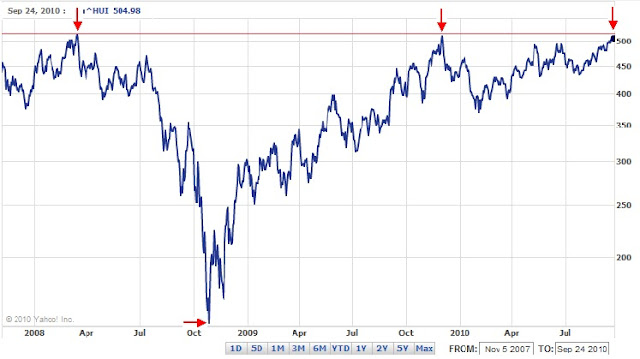
The most pressing matter for the precious metals market right now is confirmation. So far, the price of gold and silver has exceeded their respective 2008 highs. However, the corresponding stock indexes, the XAU and the HUI, have not yet confirmed the trend. If the trend is confirmed then we will have received the indication of the beginning of a secular bull market in gold and silver. In our Richard Russell Review posted on July 4, 2010, we outlined Russell’s significant detail on the importance of confirmations. Although our analysis shows how Russell got the interpretation incorrect, it is well worth re-examining this article since it outlines exactly how to utilize both indicators (price of gold and gold stock index) for confirmation of the trend.
Below is the HUI index with what appears to be the third attempt at the 514.89 level.
Although not likely, failure to breach the 2008 peaks for the XAU and the HUI index could mean very hard economic times ahead. Alternatively, going above the previous peak, which seems much more likelier, may mean that we’re entering the early stages of higher interest rates and inflation. It is necessary to keep in mind that higher inflation and higher interest rates won’t initially wreck havoc on the economy.
Most investors have the tendency to remember only the periods at the extremes, the real estate bust, the real estate bubble, the dot com bust, the dot com bubble, the gold bubble and the gold bust, skyrocketing interest rate, the current zero interest rate environment. In every instance, the recollection of such periods is rooted in the final stage. However, what is more important is the slow transition that takes place from trough to the next peak.
In the case of inflation, the slow transition was the innocuous period, saved for a world war, from 1932 to 1966. Unfortunately, most investor over concentrate on the period from 1973 to 1980 due to the exaggerated moves upward. The transitional period brought many cyclical and one secular bull market in the Dow Jones Industrial Average. It is possible that as our inflation rate climbs the Dow Jones Industrial Average could experience a bull market similar to the period form 1949 to 1966.
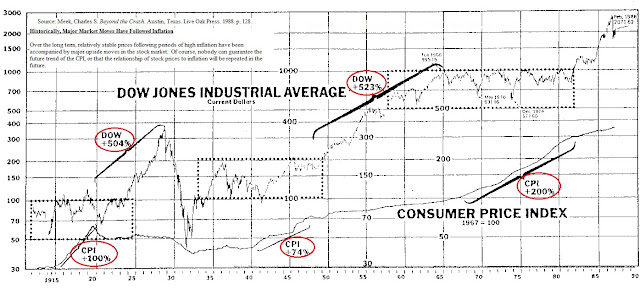
According to the chart below, periods of inflation coincided or preceded extremely large moves in the stock market. The period from 1940 to 1947 had a 74% increase in the CPI while at the same time the stock market doubled in value. Naturally the argument is that the stock market only managed to beat inflation by a small amount over that period. The reality is that the response by the Dow Industrials was to go from the 100 level in 1941 to the 1000 level in 1966.
Looking at the chart above, it is hard to believe that the CPI increase of 200% in the 1970's would follow the pattern of previous high inflation periods with stocks increasing 10 times in each instance.
While we watch and wait for the confirmation of the new high in the price of gold and silver with the XAU and HUI indexes by breaking above their 2008 highs, our overall assertion still is that if precious metals and their stocks continue heading higher so will the general stock market.
Posted in gold, gold bugs, Homestak Mining, HUI, Richard Russell, Silver, XAU
Tagged members
Seeking Ten Percent
A reader asks:
“I see that your Watch List performance for the past 12 months is no better than the Dow's. How is that possible when you focus on the Dividend Achievers that are close to their 52-wk lows and do so much in-depth research and analysis?
“Am I missing something? If not, then how do you argue against just investing in something like a Vanguard index fund? Or, better still, there are value-oriented funds like those run by Tweedy Browne, et al, that have substantial outperformance to the market.
“Should your approach be modified to take into account the macro view first and then selecting the right sectors (from among the S&P 500's ten sectors) based on where the economy is in its growth/decline cycle? Thus, should the cycle analysis be used along with your present criteria to achieve outperformance?”
Our response:
These are all great questions. First, we’ll address the question of why bother doing all the work of researching these company if the final result is simply to underperform the Dow Jones Industrial Average. As indicated in the book Investing: The Last Liberal Art there is an element of joy in learning new things. We love the process of understanding the research into cell apoptosis that a drug company is doing. We love finding a book like Taking Chances: The Psychology of Losing and how to Profit from it which helps us to understand more fully the benefits of failing. We love stumbling upon mathematical "quirks" like Benford’s Law whereby it can be proven that the order and frequency of the first digit in a set of numbers can reveal that there is accounting fraud. Simply put, our research of stocks fulfills our desire to understand the world around us while we attempt to pursue the profit motive.
In pursuit of the profit motive, the goal of the New Low Observer is to obtain mediocre gains of 9%-12% in each investment that we make. This means that when a stock rises to the level that we’re comfortable with, within the designated range, we find the next best alternative that is on any one of our new low lists.
As mentioned before, we consider selling a stock when it reaches a gain of 10% within a year. All of the stocks on our September 25, 2009 watch list accomplished our goal of 10% well before the end of the one-year period. The table below is the best demonstration of our approach in action.
|
Symbol
|
days to 10%
|
Annualized gain
|
|
WMT
|
54
|
67.59%
|
|
CAH
|
44
|
82.95%
|
|
WEYS
|
208
|
17.55%
|
|
ABT
|
44
|
82.95%
|
|
NWN
|
162
|
22.53%
|
|
BCR
|
182
|
20.05%
|
|
LLY
|
52
|
70.19%
|
|
BDX
|
68
|
53.68%
|
|
PNY
|
84
|
43.45%
|
|
*based on September 25, 2009 Dividend Watch List
|
||
As you can see from the stocks above, in some cases, accomplishing 10% occurred much earlier than we would have expected. We like to think of returns of 10% in less than a year as a form of accumulated time. This means that if we gain 10% in 5 months, we have at least 7 months to sit back and study the markets. This is seven months where we can detach ourselves from the noise and chaos that normally distorts rational thinking. Obviously, this is an option that we exercise from time to time when we’re not sure of the market prospects.
The example that we provided in our performance review of Dividend Achievers from September 25, 2009 was actually the worst case scenario if you decided, for some reason or another, to buy and hold all of the stocks that were on the list at the time (not recommended.) As far as we’re concerned, we were out of those stocks long before one year as has been demonstrated with the Sell Recommendation section of this site. Again, we seek mediocrity in our investment strategy knowing that if 10% can be accomplished within a year then we have been exceptionally fortunate. As mentioned in previous articles, we only expect 1/3 of the stocks to achieve 10% in one year during a bull market. However, if a stock that you purchase is on our Dividend Watch List, you can be assured that you can hold the stock for the “long term” if you choose to do so.
Finally, we are constantly trying to keep abreast of the macro view of the markets and the economy. However, our best experience has been with the use of Dow Theory. Although not infallible, Dow Theory is intended to be an all encompassing guide to not only what is going on right now but also what to expect in the future up to three to nine months ahead. We’re cognizant of the fact that Dow Theory is only a tool and not THE answer to what the future holds. Therefore, we only apply Dow Theory as a tool for determining asset allocation. Charles Dow himself has been specific on the point that investors can still have their money at work in a bear market (during a recession or depression). The only change that needs to take place during such hard economic times is the expectation of returns. As we at the New Low Observer seem insistent on getting 10% during the good times, we must be willing to accept 5% during the bad times.
Dividend Watch List
Watch List Summary
As always, we revisit the previous list for the best and worse performing stocks from our Dividend Watch List. The best performing stock was National Fuel Gas (NFG) which rose 12.9% in two weeks. The biggest decline was Carlisle (CSL) which fell 5.2%.
Of the top five companies, we particularly like Northern Trust (NTRS). Anyone interested can read our take of Northern Trust from September 1, 2010 article. Intel (INTC) bounced off the 52-week low and rose 5% in two weeks. ConAgra (CAG) got hit after lowering its guidance as investors overlooked the 15% hike in the dividend. ConAgra shares are approaching their historical undervalued range according to Investment Quality Trends (http://www.iqtrends.com/).
*Note: Price data as of market close on Thursday September 23, 2010*
September 24, 2010 Watch List
| Symbol | Name | Price | % Yr Low | P/E | EPS (ttm) | Div/Shr | Yield | Payout Ratio |
| WST | West Pharmaceutical Services | 33.04 | 0.89% | 14.43 | 2.29 | 0.64 | 1.94% | 28% |
| CSL | Carlisle Companies Inc. | 28.25 | 1.00% | 12.12 | 2.33 | 0.68 | 2.41% | 29% |
| NTRS | Northern Trust Corp. | 46.97 | 3.69% | 15.40 | 3.05 | 1.12 | 2.38% | 37% |
| TR | Tootsie Roll Industries Inc | 24.06 | 3.71% | 26.44 | 0.91 | 0.32 | 1.33% | 35% |
| FFIN | First Financial Bankshares, Inc. | 45.08 | 3.51% | 17.27 | 2.61 | 1.36 | 3.02% | 52% |
| MLM | Martin Marietta Materials, Inc. | 74.34 | 3.97% | 41.30 | 1.80 | 1.60 | 2.15% | 89% |
| CAG | ConAgra Foods, Inc. | 21.56 | 4.91% | 13.31 | 1.62 | 0.80 | 3.71% | 49% |
| LANC | Lancaster Colony Corp. | 45.47 | 5.06% | 11.17 | 4.07 | 1.20 | 2.64% | 29% |
| HGIC | Harleysville Group Inc. | 31.66 | 5.36% | 11.95 | 2.65 | 1.44 | 4.55% | 54% |
| FUL | HB Fuller Company | 19.49 | 5.52% | 10.71 | 1.82 | 0.28 | 1.44% | 15% |
| CWT | California Water Service Group | 35.78 | 5.83% | 19.34 | 1.85 | 1.19 | 3.33% | 64% |
| WFSL | Washington Federal, Inc. | 14.81 | 6.01% | 14.10 | 1.05 | 0.20 | 1.35% | 19% |
| SBSI | Southside Bancshares, Inc. | 18.44 | 6.03% | 6.98 | 2.64 | 0.68 | 3.69% | 26% |
| HRB | H&R Block, Inc. | 12.74 | 6.34% | 8.73 | 1.46 | 0.60 | 4.71% | 41% |
| BCR | CR Bard, Inc. | 78.75 | 6.43% | 16.04 | 4.91 | 0.72 | 0.91% | 15% |
| PAYX | Paychex, Inc. | 26.25 | 6.49% | 19.89 | 1.32 | 1.24 | 4.72% | 94% |
| USB | U.S. BanCorp. | 21.82 | 6.75% | 15.70 | 1.39 | 0.20 | 0.92% | 14% |
| CL | Colgate-Palmolive Co. | 78.06 | 6.76% | 18.63 | 4.19 | 2.12 | 2.72% | 51% |
| FFIC | Flushing Financial Corp. | 10.92 | 7.37% | 11.26 | 0.97 | 0.52 | 4.76% | 54% |
| OMI | Owens & Minor, Inc. | 27.48 | 7.68% | 13.95 | 1.97 | 0.71 | 2.58% | 36% |
| BEC | Beckman Coulter, Inc. | 47.33 | 7.69% | 22.54 | 2.10 | 0.72 | 1.52% | 34% |
| UMBF | UMB Financial Corp. | 34.24 | 7.77% | 14.27 | 2.40 | 0.74 | 2.16% | 31% |
| HCC | HCC Insurance Holdings, Inc. | 25.71 | 7.80% | 8.84 | 2.91 | 0.58 | 2.26% | 20% |
| INTC | Intel Corp. | 18.98 | 7.84% | 11.37 | 1.67 | 0.63 | 3.32% | 38% |
| MDT | Medtronic, Inc. | 33.25 | 7.95% | 10.52 | 3.16 | 0.90 | 2.71% | 28% |
| AWR | American States Water Co. | 33.74 | 8.14% | 20.70 | 1.63 | 1.04 | 3.08% | 64% |
| UFPI | Universal Forest Products, Inc. | 27.95 | 8.50% | 22.72 | 1.23 | 0.40 | 1.43% | 33% |
| JNJ | Johnson & Johnson | 61.81 | 8.71% | 12.77 | 4.84 | 2.16 | 3.49% | 45% |
| WFC | Wells Fargo & Co. | 25.04 | 8.77% | 15.08 | 1.66 | 0.20 | 0.80% | 12% |
| DNB | Dun & Bradstreet Corp. | 71.08 | 8.78% | 15.29 | 4.65 | 1.40 | 1.97% | 30% |
| XOM | Exxon Mobil Corp. | 61.15 | 9.31% | 11.81 | 5.18 | 1.76 | 2.88% | 34% |
| FRS | Frisch's Restaurants, Inc | 19.85 | 9.73% | 10.28 | 1.93 | 0.60 | 3.02% | 31% |
| 32 Companies | ||||||||
For anyone who hasn't seen our performance review of the Dividend Watch List from last year, we urged you to take a look. Our assessment is a worst case look at how our list beat the S&P 500.
On our current list, we excluded companies that have no earnings and payout ratios in excess of 100%. Stocks that appear on our watch lists are not recommendations to buy. Instead, they are the starting point for doing your research and determining the best company to buy. Ideally, a stock that is purchased from this list is done after a considerable decline in the price and extensive due diligence.
Because our list has many great companies, we urged investors to filter for companies with less than 50% payout ratio. This should minimized the risk of dividend reductions if earnings are to fall by half. If you understand the companies' history and their ability to pay the dividend, then payout ratios in excess of 50% may be considered. We suggest readers use the March 2009 low (or companies' most distressed level in the last 2 years) as the downside projection for investing. Our view is to embrace the worse case scenario prior to investing. The November 2008 to March 2009 time frame fits that description. It is important to place these companies on your own watch list so that when the opportunity arises, you can purchase them with a greater margin of safety.
Email our team here.
The Staggering Heights of Annualized Returns
A reader comments:
“Perhaps your ideas have evolved further, matured, but I'm not sure what the fair profit is from reading this article (“Seeking Fair Profits”). Is it 5%, 16% or your current strategy of 10 percent?
"I hold treasuries from 1 - 20 year in exchanged traded funds and about 10 different dividend paying equities. One has capital gains of 19%. That same stock, Suburban Propane (SPH) has beat the S&P by 60% over the last three years. I wonder why the 60% would not be a fair profit. To be "fair" would one have sold when there was a 10% profit three years ago or a 10% profit this year? What is wrong with the 19% gain my stock now has? How does one figure companies like Apple (AAPL)?"
Our response:
The literal interpretation of “fair profit”, according to Charles H. Dow, is between 5% to 10% per transaction. Personally, our benchmark is what you can obtain compared to the historical returns that the market can provide, something in the range of 9%-12%. You could be right that fair profit is more and the NLO team has been known to accept higher amounts when possible.
Unfortunately, the longer you hold a position the less you’re getting out of it unless the stock pays a dividend. Apple (AAPL) is the perfect example. Unless you believe that trees can grow to the sky, the stock has to revert to the mean at the very least. In doing so, each year, month and day that passes dilutes the gains that have been made. This is not a wish, it just happens to be the nature of the time value of money. All the while, there are alternative investments that are waiting to be obtained, like on our Dividend Achiever and Nasdaq 100 Watch Lists, that are waiting to set a torrid pace that few are willing to pay attention to.
The best approximation at an answer to your question as it relates to Suburban Propane (SPH) is found in our March 18, 2010 article titled "Gaining More by Limiting Our Gains." That article points out that sitting on a single position for an extended period of time could result in a complete reversal of gains. In that same article we pointed out the alternative investments that were accrued after we issued a sell recommendation for Meridian Biosciences (VIVO). Individually, we were able to take advantage of the gains provided by the alternative opportunities made available at or near a new low. Therefore, 60% gains in one year with any amount of our portfolio beats 20% a year with the same representative portion of the portfolio.
In order to achieve a 20% annualized gain when selling a stock at 10%, you only need the stock to reach 10% on day 183 of your investment. If you take the time to review our Sell Recommendations, 75% of the names on our list achieved 10% or more in less than 183 days. The secret is to view investment performance is viewing it from an annualized basis.
Suffice to say, when we invest our funds, during Dow Theory bull markets, we allocate at least 25% of our portfolio to each position we enter (during bear markets we allocate 12%) therefore, our initial investment has a greater impact on the entire portfolio. On a $100 portfolio, a ten percent gain on 25% of the portfolio equals a gain of $2.50 or 2.5%. In the same portfolio, a ten percent gain on 3% of the portfolio equals a gain of $0.30 or 0.003%.
-
$25 x .10= $2.50 $2.50/$100= 2.50% (based on 10% gain)
-
$3 x .10= $0.30 $0.30/$100= 0.003% (based on 10% gain)
Under the 3% of portfolio scenario, it would take a gain of 83% before the $3 position could match a 10% increase in a 25% allocation. Because we don’t subscribe to the mantra of diversification as described in our article “Diversification Doesn’t Matter,” we’re more flexible with what we acquire and vigilant about how long we hold each position.
Upon final analysis, the point of our New Low Watch List is that you can investigate quality companies at relatively undervalued levels. Once an acquisition is made you can selectively choose the time to sell with a significantly lower risk adjusted basis. Being cognizant of annualized returns as opposed to absolute returns will change any reasonable person’s mind about whether or not it is worth holding a stock longer than necessary.
Posted in Annualized return
A Summary of the Risks of ETFs
NLO Commentary:
It is only a matter of time before this situation ends badly. We've been chronicling this matter for over a year. We also believe that the "flash crash" of May 6, 2010 has its origins in ETFs. Below are the article links to our contribution to this topic
Performance Review: Dividend Achiever Watch List of September 25, 2009
We’ve decided to revisit our watch list from one year ago to see if we can extract any valuable lessons from our "research of quality stocks at a new low" approach. The table below shows our watch list from 9/25/09 against 9/21/10.
| September 25, 2009 | September 21, 2010 | ||||||||||
| Symbol | Name | Price | Div/Shr | Yield | Price | Div/Shr | Yield | % Gain w/o Dividend | % Gain w/ Dividend | ||
| WMT | WAL MART STORES | 49.47 | 1.09 | 2.20% | 53.57 | 1.18 | 2.20% | 8.3% | 10.5% | ||
| CAH | CARDINAL HEALTH | 27.32 | 0.70 | 2.56% | 33.11 | 0.72 | 2.17% | 21.2% | 23.8% | ||
| WEYS | Weyco Group, Inc. | 22.51 | 0.60 | 2.67% | 23.97 | 0.62 | 2.59% | 6.5% | 9.2% | ||
| BCR | BARD C R INC | 78.06 | 0.68 | 0.87% | 80.48 | 0.69 | 0.86% | 3.1% | 4.0% | ||
| NWN | NORTHWEST NAT | 41.91 | 1.58 | 3.77% | 46.44 | 1.66 | 3.57% | 10.8% | 14.6% | ||
| ABT | ABBOTT LAB | 47.33 | 1.60 | 3.38% | 52.15 | 1.68 | 3.22% | 10.2% | 13.6% | ||
| PNY | PIEDMONT NAT GAS | 23.84 | 1.08 | 4.53% | 28.20 | 1.38 | 4.89% | 18.3% | 22.8% | ||
| BDX | BECTON DICKINSON | 68.50 | 1.32 | 1.93% | 73.71 | 1.48 | 2.01% | 7.6% | 9.5% | ||
| LLY | ELI LILLY | 32.68 | 1.96 | 6.00% | 36.33 | 1.96 | 5.39% | 11.2% | 17.2% | ||
| Watch List Avg. | 10.8% | 13.9% | |||||||||
| S&P 500 | 1,044.38 | 21.58 | 2.07% | 1,139.78 | 21.84 | 1.92% | 9.1% | 11.2% | |||
| Dow 30 | 9,665.19 | 281.71 | 2.91% | 10,761.03 | 282.03 | 2.62% | 11.3% | 14.3% | |||
As you can see, none of the companies on this list experienced any loss. However, not all high quality dividend-paying stocks are created equal. The gains ranged from 4% to 23.8% with dividend included. Overall, the average gain was 10.8% without dividends and 13.9% with dividends, which is a little better than the S&P 500 but lagged the Dow Jones Industrial average.
There are several interesting things we found. The first thing is that some companies on the list have virtually gone nowhere based on valuation. Wal-mart was and is yielding 2.2% and Bard still yields 0.86%. On one extreme of the spectrum, two companies are now cheaper than they were a year ago, on valuation basis. For example, Piedmont Natural Gas (PNY) is now yielding 4.89% compared to 4.53% a year ago. Yet, the shares of PNY have risen 22.8%. Also in the category is Becton Dickinson (BDX) which is yielding more today than it did last year.
The second finding is that, on average, these companies raised dividend by 7%. This should come as no surprise to those who know the Dividend Achiever list.
Another observation that can be made is the sectors that were at a new lows at the time. From this list, we can assume that the medical/pharmaceutical sectors were out of favor. Of the companies on the list, 5 of 9 belonged to that sector.
The next thing we noticed is that high dividend yields didn't necessarily mean higher returns. Although Eli Lilly (LLY) sported the highest dividend yield, which pushed LLY’s total return from 11% to 17%, it didn't out perform Cardinal Health’s (CAH) total return of 23.8% and Piedmont Natural Gas’ (PNY) total return of 22.8%. As we’ve indicated in our articles and commentary, among high quality dividend paying stocks, the yield isn’t as important quality of the company. Furthermore, what you lack in yield is often made up for in capital appreciation.
The final point is that, although BCR returned just 4% over one year, the shares had risen as high as $90, or 15.30%, in late April 2010. Conservative investors would do well to consider such performance exceptional since the historical return of the market over an extended period of time seldom exceeds 12% especially in less than a year. Similar intra-period performance can be demonstrated in many of the stocks on our list. This is the reason the New Low team is so focused on "seeking fair profits" as described by Charles H. Dow.
In summary, our watch list from one year ago beat the S&P by 270-basis points but fell short against the Dow Industrials by 40-basis points. Naturally, the spread widened without the dividend.
Going forward, as our watch list expands, we expect to show example of only the top five or ten on our list to simplify the examination process. It is our expectation that only 1/3 of the companies that are part of our list will outperform the market over a one year period. However, when the market of 5,000 investment options is winnowed down to what we believe are the best starting points, we think that selecting three out of ten high quality dividend stocks at a new low is reasonable approach.
Email our team here.
The Anatomy of a Bear Market Trade
One Investment Observation that we made is worth reviewing because it encompasses many fundamental techniques necessary for accounting for risk in bear markets. Our recommendation of Bank of Hawaii (BOH) on January 12, 2009 at the price of $37.76 is a prime example of risk adjusted investing. We’d like to think that this was among the boldest and well-planned recommendations that we’ve done. In this analysis, we’ll point out the specific elements that made this Investment Observation so unique.
First and foremost, the recommendation of a bank would seem to be completely out of left field for us since we have always intentionally shied away from the banking sector. Making our recommendation more usual was the fact that we were in the midst of a literal and figurative collapse in the banking industry. In January of 2009, it was hard to tell where the fire wasn’t going to spread next. After all, if you’d seen Fannie Mae, Freddie Mac, AIG, Merrill Lynch, Bear Stearns, Washington Mutual, and Lehman go off the deep end, who is to say that other regional banks weren’t next? However, to see such a well-run institution like BOH closing in on a new low was very hard to resist.
A favorite default reaction for a stock that is near a new low is to look at Value Line Investment Survey for a specific piece of information. In the legend box provided by Value Line, it indicates the most reliable measure of historical mean price that the stock trades at. Sometimes that measure is based on cash flow, earnings, earnings divided by interest rate, book value etc. Regardless of the measure, Value Line’s estimated mean value is quite reliable. If the stock is above or below the mean figure it helps provide a target that we can expect the price to revert to at some point in the future. The quality of the mean figure hinges on the quality of the stock. If for some reason there doesn’t seem to be any consistency in the Value Line estimate then we discard it outright and only use Dow Theory’s fair value as the substitute mean. However, we have found the Value Line estimate to be reasonably reliable for the majority of stocks that we track.
In our assessment of Bank of Hawaii, Value Line indicated that the mean price for BOH was 14 times earnings. At the time, full year 2008 trailing earnings were at $4.06. We only use full year trailing earnings; estimates of the future are not accepted unless they are lower than the previous full year’s data. The figures provided by Value Line gave us a mean price of $56.84 for where we could expect the price of Bank of Hawaii to eventually revert to. Depending on the quality of the company, our dreams are fulfilled if the stock in question goes back to the mean. This is also in accordance with Dow’s Theory that all stocks tend to gravitate to their fair value.
In terms of Dow Theory, we indicated that there were three downside targets. From our analysis of previous Dow Theory moves, we indicated that Bank of Hawaii demonstrated the capacity to retrace “…from the peak to between the 2nd and 3rd retracement levels…” This led us to believe that a purchase of the stock might be required “…between $30.70 and $20.87.” The actual lowest point reached on a closing basis for Bank of Hawaii on March 9, 2009 was $25.70. This was $0.08 less than the exact middle of $30.70 and $20.87.
Our next point of reference was if we were forced to hold the stock for “the long term.” Using this perspective, we surmised that Bank of Hawaii would have to be held for 15 years “...to recoup all [or some] that you have initially invested if you reinvest the dividends.” This is a big leap of faith considering that the dividend could be cut at any time. However, because BOH had demonstrated a consistent history of increasing dividends for over 30 years, it warranted the benefit of the doubt on this matter.
Since the stock price of Bank of Hawaii had been in a rising trend for an extended period of time it was difficult to gain new insight from looking at the chart. However, what we did notice was the surge in volume of shares traded when the stock was nearing a low. Given this pattern, we said:
“All we need now is a good collapse in the price to reassure us of the opportunity to buy. That opportunity might come in the wake of BOH falling below the 52-week low of $36.32 reached on November 21, 2008.”
Shortly afterwards, the stock price experienced an even greater surge in the volume which was accompanied by a steep decline. As mentioned before, Bank of Hawaii (BOH) had a closing low price of $25.70. Being tepid on the idea of holding a stock longer than necessary, we issued a sell recommendation on August 6, 2009.
Under the following scenarios, investor gains would have varied greatly if:
- bought at the observed price of $37.76 and sold on the recommended sell date, the gain would have been 19.47% on an annualized basis.
- bought at the low of $25.70 and sold at the top, the annualized gain would be 54%
- bought at the observed price of $37.76 and held to the present, the approximate gain would be 10.40% on an annualized basis.
Although we outlined exactly what eventually happened, we could never take credit for actually buying at the bottom and selling at the exact top. However, we can show that our ballpark estimates for Bank of Hawaii (BOH) reaching the mean price was fairly accurate. The peak in the price at $53.53 was within 6.18% of our price target of $56.84. Our estimated time to buy the stock between $30.70 and $20.87 was met with a closing low of $25.70 or $0.08 off of the exact middle of the two price points. Finally, we were able to usurp the 4.80% dividend yield by selling the stock with an annualized gain of 19%. We didn’t have to hold the stock “for the long term” to realize such opportunities.
Naturally, there are some critics who suggest that hiding behind “quality” stocks is only a ruse to speculate rather than invest. We understand and grapple with this consideration constantly. We know that most market commentators in the media lionize “The Warren Buffett Way” and vilify traders. Other critics might argue that if we “knew” so much then why didn’t we recommend Citigroup (C) or Bank of America (BAC)? However, our goal was, and always will be, to determine the lowest risk way to invest in the stock market with the widest margin for error with an annualized gain of 10% on each investment.
New Low Team Beats NBER to the Punch
The New Low Observer (NLO) team has done it again on the economy, stock market and our “guess” of when the National Bureau of Economic Research (NBER) would declare the end of the recession that began in October of 2007.
First and foremost, the NLO team announced on July 24, 2009 (the initiation of the NLO site) that Dow Theory had indicated that we were definitely in a cyclical bull market. This ignores our article on February 11, 2009 titled “Convergence of Extraordinary Forces” that indicated that there would be a bottom in the market around June 2009. According to Dow Theory, a bottom in the stock market implies a trough in the economy as well.
Second, on August 22, 2009, the NLO team indicated that based on the Industrial Production Index (IPI) and the Dow Theory bull market indication the stock market and the economy were headed high.
Finally, along with our call to the end of the recession on August 22, 2009, we predicted that the NBER would “…proclaim June 2009 as the official end to the recession.” The headline out of the NBER today, September 20, 2010, is that “…a trough in business activity occurred in the U.S. economy in June 2009.”
Some of the articles can be verified with the postings on Seeking Alpha.com; which we cannot alter once published. Just look at the approximate date that the article was published since Seeking Alpha does not publish exactly when submitted.
Seeking Alpha Articles:
Subscribers to our site have received all indicated articles with any revisions of our view as appropriate. Anyone interested in subscribing by email can use the following link.
Posted in bull market, Dow Theory, NBER, recessions
Nasdaq 100 Watch List
Watch List Summary
At the end of the week for September 17, 2010, the top performing stocks from our Nasdaq 100 list for August 15, 2010 are Oracle (ORCL) with a gain of 21.27%, Qualcomm (QCOM) with a gain of 12.07% and Computer Associates (CA) with a gain of 11.57%.
The worst performing stocks from our August 15th watch list are Intel (INTC) down –1.78%, Applied Materials (AMAT) down –1.34% and Activision (ATVI) down –0.46%.
The average gain for the watch list was 6.33%. Of the two stocks that we pointed out as being standouts from August 15th, Garmin (GRMN) exceeded the average return by climbing 9.57% while Paychex (PAYX) underperformed the average gain by rising 3.92%.
A distinction that needs to be made between this week’s list and our August 15th list is that we’ve ranking the companies on this list by those stocks nearest their 52-week low. Our previous list was ranked by those stocks that had the highest dividend yield and within 20% of their respective 52-week low.
Performance Review
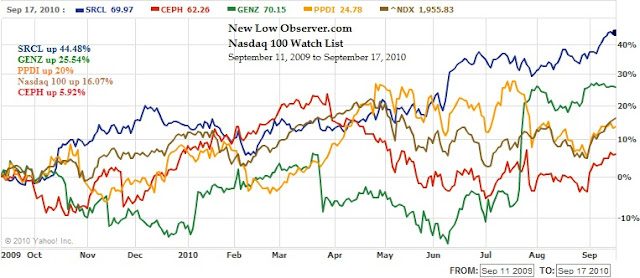
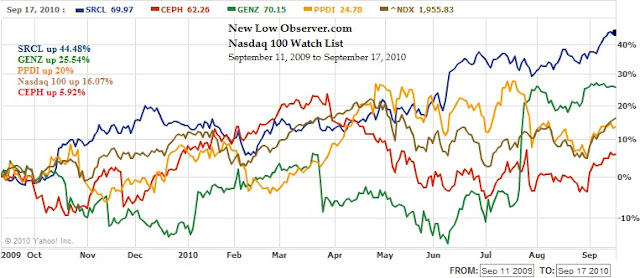
The following is a total return (appreciation plus dividends) performance review of our Nasdaq 100 Watch List from September 11, 2009:
- Stericycle (SRCL) up 44.48%
- Genzyme (GENZ) up 25.54%
- Pharmaceutical Product Development (PPDI) up 20%
- Cephalon (CEPH) up 5.92%
As a group, the average gain for the stocks mentioned was 23.99%. This is contrasted by the Nasdaq 100 gain of 16.07% in the same period of time.
![]() |
| *chart does not reflect dividend reinvestment for PPDI |
Nasdaq 100 Watch List
Below are the Nasdaq 100 companies that are within 20% of their respective 52-week lows. Stocks that appear on our watch lists are not recommendations to buy. Instead, they are the starting point for doing your research and determining the best company to buy. Ideally, a stock that is purchased from this list is done after a considerable decline in the price and rigorous due diligence.
| Symbol | Name | Price | P/E | EPS | Yield | P/B | % from Low |
| PAYX | Paychex, Inc. | 25.95 | 19.67 | 1.32 | 4.80% | 6.67 | 5.27% |
| INTC | Intel Corporation | 18.81 | 11.26 | 1.67 | 3.40% | 2.3 | 6.87% |
| AMAT | Applied Materials, Inc. | 11.02 | 24.44 | 0.45 | 2.50% | 2.03 | 7.33% |
| YHOO | Yahoo! Inc. | 13.89 | 22.77 | 0.61 | N/A | 1.59 | 7.34% |
| MXIM | Maxim Integrated Products, Inc. | 16.91 | 41.86 | 0.4 | 5.00% | 2.15 | 7.91% |
| GILD | Gilead Sciences, Inc. | 34.56 | 10.47 | 3.3 | N/A | 4.58 | 8.93% |
| ATVI | Activision Blizzard, Inc | 10.82 | 41.94 | 0.26 | 1.30% | 1.21 | 8.96% |
| DELL | Dell Inc. | 12.45 | 15.74 | 0.79 | N/A | 3.92 | 9.80% |
| RIMM | Research In Motion Limited | 46.72 | 10.24 | 4.56 | N/A | 3.2 | 9.85% |
| AMGN | Amgen Inc. | 55.22 | 11.73 | 4.71 | N/A | 2.28 | 9.87% |
| DISH | DISH Network Corporation | 18.77 | 11.26 | 1.67 | N/A | N/A | 10.02% |
| CSCO | Cisco Systems, Inc. | 21.86 | 16.46 | 1.33 | N/A | 2.82 | 10.31% |
| XRAY | DENTSPLY International Inc. | 30.66 | 16.55 | 1.85 | 0.70% | 2.6 | 10.45% |
| MSFT | Microsoft Corporation | 25.22 | 12 | 2.1 | 2.10% | 4.76 | 10.95% |
| SPLS | Staples, Inc. | 19.49 | 17.26 | 1.13 | 1.80% | 2.2 | 11.69% |
| PDCO | Patterson Companies Inc. | 27.15 | 14.67 | 1.85 | 1.50% | 2.3 | 12.52% |
| SHLD | Sears Holdings Corporation | 66.83 | 27.38 | 2.44 | N/A | 0.9 | 12.87% |
| GOOG | Google Inc. | 490.15 | 21.29 | 23.03 | N/A | 3.77 | 13.03% |
| LIFE | Life Technologies Corporation | 46.51 | 29.91 | 1.56 | N/A | 1.97 | 13.16% |
| STX | Seagate Technology. | 11.16 | 3.55 | 3.14 | N/A | 1.95 | 13.41% |
| FLIR | FLIR Systems, Inc. | 27.24 | 18.52 | 1.47 | N/A | 3.25 | 13.50% |
| GRMN | Garmin Ltd. | 29.64 | 8.95 | 3.31 | 5.10% | 2.21 | 13.52% |
| TEVA | Teva Pharmaceutical Industries | 53.48 | 19 | 2.82 | 1.20% | 2.48 | 13.81% |
| FLEX | Flextronics International Ltd. | 5.55 | 15.72 | 0.35 | N/A | 2.26 | 14.20% |
| COST | Costco Wholesale Corporation | 61.29 | 21.93 | 2.8 | 1.30% | 2.43 | 14.75% |
| HSIC | Henry Schein, Inc. | 56.35 | 15.82 | 3.56 | N/A | 2.31 | 14.77% |
| CERN | Cerner Corporation | 79.18 | 31.31 | 2.53 | N/A | 3.83 | 14.85% |
| CELG | Celgene Corporation | 55.25 | 29.99 | 1.84 | N/A | 5.11 | 15.06% |
| CA | CA Inc. | 20.44 | 13.43 | 1.52 | 0.80% | 2.02 | 15.48% |
| ERTS | Electronic Arts Inc. | 16.26 | N/A | -1.06 | N/A | 1.96 | 15.63% |
| VRTX | Vertex Pharmaceuticals Incorpor | 36.25 | N/A | -3.53 | N/A | 9.01 | 16.00% |
| KLAC | KLA-Tencor Corporation | 31.05 | 25.31 | 1.23 | 3.30% | 2.32 | 16.34% |
| STLD | Steel Dynamics, Inc. | 15.01 | 15.73 | 0.95 | 2.00% | 1.58 | 16.45% |
| WCRX | Warner Chilcott plc | 22.75 | 11.2 | 2.03 | N/A | 2.82 | 16.55% |
| LOGI | Logitech International S.A. | 15.39 | 22.57 | 0.68 | N/A | 2.68 | 16.86% |
| CEPH | Cephalon, Inc. | 62.26 | 12.48 | 4.99 | N/A | 2.09 | 17.36% |
| URBN | Urban Outfitters, Inc. | 34.11 | 22.19 | 1.54 | N/A | 4.26 | 18.85% |
| FWLT | Foster Wheeler AG. | 24.19 | 10.8 | 2.24 | N/A | 3.46 | 18.99% |
| FISV | Fiserv, Inc. | 53.56 | 17.16 | 3.12 | N/A | 2.57 | 19.55% |
| JBHT | J.B. Hunt Transport Services, I | 35.26 | 26.73 | 1.32 | 1.40% | 7.56 | 19.73% |
| CTAS | Cintas Corporation | 27.71 | 19.64 | 1.41 | 1.70% | 1.67 | 19.96% |
Beckman Coulter (BEC): Pondering the Imponderable
A reader asks:
Will Beckman Coulter (BEC) stock bounce back to $70 in a few months?
Our Response:
To attempt to respond to this question, for the sheer joy of pondering the thought, we first need to define the parameters. First, we need to refine the question by asking, “Will Beckman Coulter (BEC) get to $70 by December 13, 2010?”
Addressing the issue of whether Beckman Coulter (BEC) will get to $70 by December 13th requires an acceptance of the probability this will occur. The last time BEC was at a similar stock price of $45.24 (prior to reaching the $70 level) was on March 17, 2009. From that time, it took 125 trading days to reach $70.03 by September 11, 2009. This means that the stock of Beckman Coulter could reach $70 by March 9, 2011. If the stock were to match the previous trajectory from March 17, 2009 to September 11, 2009, by December 13, 2010, BEC would be at the $57.51 level in the stock price.
However, to put Beckman Coulter’s 2009 rise in perspective, we must remember that the period from March 17, 2009 to September 11, 2009 was the most rampant stock market reaction to the prior 2007 to 2009 collapse. This means that extraordinary forces that were behind the rise in all stocks. It is highly unlikely we’ll have the same forces at play this time around for both the stock market in general and BEC in particular.
According to Dow Theory, BEC is considered to be at fair value when the price is at $56.99. The upside targets are as follows:
-
$52.64
-
$61.33
-
$70.03
At each indicated level, the price of Beckman Coulter would experience major resistance to the upside. This means that the price could just as easily revert to the prior support level.
The great Dow Theorist Richard Russell has indicated on many occasions that a stock’s decline typically lasts 1/3 of the rise. Being selective in our analysis, the peak in BEC on August 18, 2008 at $75 was reconciled on December 12, 2008 when the stock closed at $39.44. This transition from $75 to $39.44 took 83 days. The subsequent peak in BEC took place on or near September 14, 2009; which was a full 270 days from the previous peak on August 18, 2008. In this example, selective as it is, the decline lasted 31%, or 1/3, of the complete cycle.
Now, if we apply the same flawed logic to Beckman Coulter (BEC) going forward, we arrive at a date of September 13, 2011 for the time when the stock reaches the next peak. This does not necessarily mean that the price will be at the same level it once was. In fact, it could be much lower or much higher. The point is, the next peak in the price, whatever it may be, would occur somewhere around September 13, 2011. We’ll throw in the possibility that BEC revisits $70 at the same time next year.
As shareholders of Beckman Coulter (BEC), we expect that the stock should fall at least 50% from the level the stock was purchased at. Naturally, we have the expectation that the stock price will fall between now and December 13, 2010. If the stock price rises to $52.64 then we would be pleasantly surprise. If the stock price rises to $56.99 by the proposed date then we’d be shocked beyond belief. The mere suggestion that the stock could reach $70 in such a short period of time is almost out of our capacity to fathom. We don’t think BEC will reach $70 by December 13, 2010.
Our Summary on Beckman Coulter reaching $70:
-
$70 by March 11, 2011 based on previous $45-$70 cycle(rosy scenario)
-
$57 by December 13, 2010 using $45-$70 trajectory (rosy scenario)
-
Price accomplishes $70 by September 13, 2011 (plausible scenario)
-
Price falls further (likely scenario)
Posted in BEC, Beckman Coulter, cycle analysis, Market cycles, Richard Russell
Tagged members
Dividend Watch List
Watch List Summary
On this week's list, the best performing stock from the previous list was a steel and iron supplier, Harsco (HSC) which rose 13.6%. The worst performing stock was H&R Block (HRB) which fell 5%.
Johnson & Johnson (JNJ) is slowly moving away from the top of the list. Taking JNJ's place is Intel (INTC) which fell 2% since our last update. Intel is trading at just 10x trailing earnings, 9x next year's estimated earnings. The reduction in price was triggered when INTC lowered its guidance and UBS downgraded the stock due to weak PC demand. This might be a good time to start looking at Intel which currently yields 3.5%. With a target return of 10% annually, Intel only needs to increase 6.5% for investors to obtain the historical average market return. Intel's current valuation is also very close to the 2008-2009 market bottom. Read more about Intel's low valuation here.
Several notable companies on the list are Toosie Roll (TR), Colgate-Palmolive (CL), Beckman Coulter (BEC), Paychex (PAYX), and Norther Trust (NTRS).
September 10, 2010 Watch List
| Symbol | Name | Price | % Yr Low | P/E | EPS (ttm) | Div/Shr | Yield | Payout Ratio |
| INTC | Intel Corp. | 17.97 | 2.10% | 10.76 | 1.67 | 0.63 | 3.51% | 38% |
| WST | West Pharmaceutical Services | 33.65 | 2.75% | 14.69 | 2.29 | 0.64 | 1.90% | 28% |
| TR | Tootsie Roll Industries Inc | 23.87 | 2.89% | 26.23 | 0.91 | 0.32 | 1.34% | 35% |
| OMI | Owens & Minor, Inc. | 26.44 | 3.61% | 13.42 | 1.97 | 0.71 | 2.69% | 36% |
| BEC | Beckman Coulter, Inc. | 45.71 | 4.00% | 21.77 | 2.10 | 0.72 | 1.58% | 34% |
| BCR | CR Bard, Inc. | 77.31 | 4.49% | 15.75 | 4.91 | 0.72 | 0.93% | 15% |
| CL | Colgate-Palmolive Co. | 75.18 | 4.50% | 17.94 | 4.19 | 2.12 | 2.82% | 51% |
| DNB | Dun & Bradstreet Corp. | 68.45 | 4.76% | 14.72 | 4.65 | 1.40 | 2.05% | 30% |
| PAYX | Paychex, Inc. | 25.85 | 4.87% | 19.58 | 1.32 | 1.24 | 4.80% | 94% |
| NTRS | Northern Trust Corp. | 47.70 | 5.30% | 15.64 | 3.05 | 1.12 | 2.35% | 37% |
| PBI | Pitney Bowes Inc | 20.10 | 5.46% | 12.18 | 1.65 | 1.46 | 7.26% | 88% |
| JNJ | Johnson & Johnson | 59.98 | 5.49% | 12.39 | 4.84 | 2.16 | 3.60% | 45% |
| NFG | National Fuel Gas Co. | 45.21 | 5.56% | 17.32 | 2.61 | 1.38 | 3.05% | 53% |
| FFIN | First Financial Bankshares, Inc. | 45.97 | 5.56% | 17.61 | 2.61 | 1.36 | 2.96% | 52% |
| CWT | California Water Service Group | 35.80 | 5.89% | 19.35 | 1.85 | 1.19 | 3.32% | 64% |
| LANC | Lancaster Colony Corp. | 45.86 | 5.96% | 11.27 | 4.07 | 1.20 | 2.62% | 29% |
| MSA | Mine Safety Appliances Co | 23.74 | 5.98% | 21.20 | 1.12 | 1.00 | 4.21% | 89% |
| RNST | Renasant Corp. | 13.58 | 6.01% | 18.35 | 0.74 | 0.68 | 5.01% | 92% |
| UVV | Universal Corp. | 37.57 | 6.25% | 7.40 | 5.08 | 1.88 | 5.00% | 37% |
| SBSI | Southside Bancshares, Inc. | 18.53 | 6.55% | 7.02 | 2.64 | 0.68 | 3.67% | 26% |
| CSL | Carlisle Companies Inc. | 29.81 | 6.58% | 12.79 | 2.33 | 0.68 | 2.28% | 29% |
| CAG | ConAgra Foods, Inc. | 21.95 | 6.81% | 13.55 | 1.62 | 0.80 | 3.64% | 49% |
| AWR | American States Water Co. | 33.35 | 6.89% | 20.46 | 1.63 | 1.04 | 3.12% | 64% |
| UMBF | UMB Financial Corp. | 33.97 | 6.92% | 14.15 | 2.40 | 0.74 | 2.18% | 31% |
| WFSL | Washington Federal, Inc. | 15.01 | 7.44% | 14.30 | 1.05 | 0.20 | 1.33% | 19% |
| XRAY | DENTSPLY International Inc. | 29.87 | 7.60% | 16.15 | 1.85 | 0.20 | 0.67% | 11% |
| HGIC | Harleysville Group Inc. | 32.34 | 7.62% | 12.20 | 2.65 | 1.44 | 4.45% | 54% |
| BDX | Becton, Dickinson and Co. | 71.27 | 7.66% | 13.95 | 5.11 | 1.48 | 2.08% | 29% |
| UFPI | Universal Forest Products, Inc. | 27.78 | 7.84% | 22.59 | 1.23 | 0.40 | 1.44% | 33% |
| HRB | H&R Block, Inc. | 12.93 | 7.93% | 8.86 | 1.46 | 0.60 | 4.64% | 41% |
| MLM | Martin Marietta Materials, Inc. | 77.35 | 8.18% | 42.97 | 1.80 | 1.60 | 2.07% | 89% |
| MDT | Medtronic, Inc. | 33.34 | 8.25% | 10.55 | 3.16 | 0.90 | 2.70% | 28% |
| FRS | Frisch's Restaurants, Inc | 19.65 | 8.62% | 10.18 | 1.93 | 0.52 | 2.65% | 27% |
| BANF | BancFirst Corp. | 37.89 | 8.66% | 14.98 | 2.53 | 1.00 | 2.64% | 40% |
| FFIC | Flushing Financial Corp. | 11.06 | 8.75% | 11.40 | 0.97 | 0.52 | 4.70% | 54% |
| WMT | Wal-Mart Stores, Inc. | 51.97 | 8.79% | 13.36 | 3.89 | 1.21 | 2.33% | 31% |
| AROW | Arrow Financial Corp. | 23.86 | 8.80% | 12.30 | 1.94 | 1.00 | 4.19% | 52% |
| HCC | HCC Insurance Holdings, Inc. | 25.95 | 8.81% | 8.92 | 2.91 | 0.58 | 2.24% | 20% |
| BBT | BB&T Corp. | 23.65 | 8.89% | 22.31 | 1.06 | 0.60 | 2.54% | 57% |
| SYK | Stryker Corp. | 46.67 | 9.20% | 15.87 | 2.94 | 0.60 | 1.29% | 20% |
| MSEX | Middlesex Water Company | 16.12 | 9.36% | 19.19 | 0.84 | 0.72 | 4.47% | 86% |
| XOM | Exxon Mobil Corp. | 61.20 | 9.40% | 11.81 | 5.18 | 1.76 | 2.88% | 34% |
| CBSH | Commerce Bancshares, Inc. | 37.52 | 9.74% | 15.25 | 2.46 | 0.94 | 2.51% | 38% |
| SVU | SUPERVALU INC | 10.63 | 9.93% | 6.52 | 1.63 | 0.35 | 3.29% | 21% |
| VFC | VF Corp. | 75.51 | 10.07% | 15.07 | 5.01 | 2.40 | 3.18% | 48% |
| GD | General Dynamics Corp. | 61.13 | 10.22% | 9.78 | 6.25 | 1.68 | 2.75% | 27% |
| BRC | Brady Corp. | 26.70 | 10.24% | 17.68 | 1.51 | 0.70 | 2.62% | 46% |
| WAG | Walgreen Co. | 28.96 | 10.28% | 13.92 | 2.08 | 0.70 | 2.42% | 34% |
| TRH | Transatlantic Holdings, Inc. | 48.62 | 10.30% | 7.74 | 6.28 | 0.84 | 1.73% | 13% |
| IBM | International Business Machines | 127.99 | 10.34% | 12.10 | 10.58 | 2.60 | 2.03% | 25% |
| RLI | RLI Corp. | 54.47 | 10.42% | 9.69 | 5.62 | 1.16 | 2.13% | 21% |
| 51 Companies | ||||||||
We excluded companies that have no earnings and payout ratios in excess of 100%. Stocks that appear on our watch lists are not recommendations to buy. Instead, they are the starting point for doing your research and determining the best company to buy. Ideally, a stock that is purchased from this list is done after a considerable decline in the price and extensive due diligence.
Because our list has many great companies, we urged investors to filter for companies with less than 50% payout ratio. This should minimized the risk of dividend reductions if earnings are to fall by half. If you understand the companies' history and their ability to pay the dividend, then payout ratios in excess of 50% may be considered. We suggest readers use the March 2009 low (or companies' most distressed level in the last 2 years) as the downside projection for investing. Our view is to embrace the worse case scenario prior to investing. The November 2008 to March 2009 time frame fits that description. It is important to place these companies in your own watch list so that when the opportunity arises, you can purchase them with a greater margin of safety.
Related Article
10-for-the-Money... Really?
Email our team here.