Freddie Mac (FRE) Trading Notes

When it comes to the cornering of a stock there are two kinds, those that fail and those that succeed. The essential element that causes the failure is the inability to get the public to "buy in" to the market action. The movement of Freddie Mac (FRE) today appears to be on the side of those who are behind the cornering of the stock.

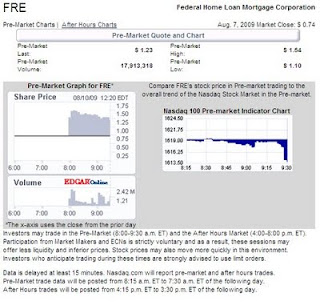
Market activity for Freddie Mac (FRE) was off the charts today, rising $0.49 or 66% in the pre-market session on almost 18 million shares and rising another 37% on 391 million in the regular hours of trading. This equals a combined increase, from Friday's closing price of $0.74, of 128%. (pre-market data below)

Chart Source: Nasdaq.com

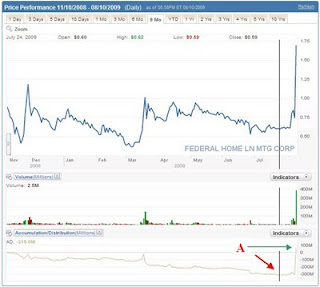
There is a distinction between the price movement of FRE and AIG. Although both are moving on syndicates' pre-market prompting, the FRE cornering of the stock may have the ability to succeed at keeping the price high for an extended period of time. Notice in the chart below that the accumulation/distribution of the stock had gone from the extremely negative low of -319 million (red arrow at point A) to a positive figure (green arrow at point A) based on the activity of today's trading.

Chart Source: Schwab.com
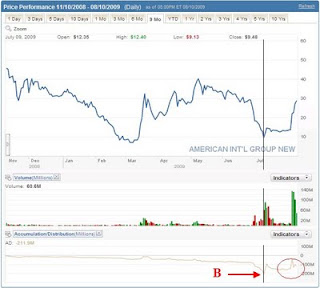
Contrast the movement of FRE's accumulation/distribution with the that of AIG. While both accumulation lines hit their lowest point on July 24th, the day after the Dow Theory bull market confirmation, AIG has not yet broken above the accumulation line (red circle.) Additionally, as AIG has gone up in price the volume has trended down.

Chart Source: Schwab.com
The AIG run does not look "sustainable" over the long term unless the accumulation/distribution improves along with a rising price and rising volume. For traders, it is expected that FRE will have a pullback, however there may be legs on this speculation as compared to AIG.
Because we're in a cyclical bull market within an even larger bear market I would consider these stocks as pure speculation regardless of the "potential" upside. Let's see which of the syndicates that are running these stocks up in pre/post market activity comes out the winner. From what I can tell, the FRE gang is miles ahead of the AIG crew in this race. This should be interesting to watch. Touc.

related articles:

Please revisit Dividend Inc. for editing and revisions to this post.

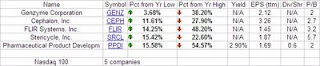
Nasdaq 100 Watch List

Dividend Achiever Watch List

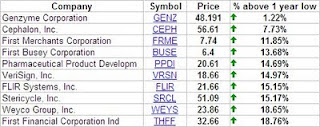
An amazing company came on my watch list this week. That company is Proctor & Gamble (PG). After reporting a bad quarter, the stock fell 3% on Wednesday and followed by another 4.5% drop on Thursday. Here are the companies on my watch list as of August 7, 2009.
In addition to PG, another great name is Becton Dickinson (BDX) which raised its fiscal 2009 profit outlook on 7/30/09.

AIG Trading Notes

Today, AIG traded up a whopping 20.46% on volume of 101,064,355 shares. On the surface of it this seems like a resounding vote of confidence for a company that is 80% owned by U.S. taxpayers. However, beneath the surface lies a murky story waiting to be told.

The story waiting to come out is that on Thurday August 6, 2009, AIG had a closing price of $22.53. During "Pre-market" trading Friday August 7th, AIG went from $22.53 to $27.37, a gain of 21.48%. The volume of shares traded during the "Pre-market" was 5,785,607 (after hour thumbnail.)
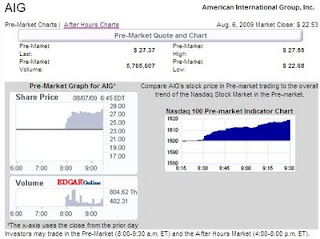
Once the regular hours of trading began on Friday August 7, 2009 the price of AIG actually fell from the $27.37 pre-market level to finally close at $27.14. Again, the regular hours of trading volume was 101,064,355.

What does all this mean? Over 5 million shares moved the price from $22.53 to $27.37. Once the regular market opened the public battled it out to come to the conclusion that the $27.37 wasn't the right price. Over 100 million only impacted the price by $0.23 lower than what 5 million was able to do by increasing the price over 20%.

My conclusion is that the public has less confidence in the future prospects for this company, and possibly the stock market, than the pre-market participants would have us believe. I also noticed that in after-hours trading the price rose an additional $0.08 on volume of 244,363 shares. Ain't it funny, 244,363 shares can raise the stock $0.08 while 100 million results in a loss of $0.23. The pre-market and after-market traders are gaming the system.

It appears that if you want to be a "trader" then you need to be entering and exiting the market before or after regular market hours. Otherwise, I would be cautious about dealing in this stock and any other stocks that are so easily managed based on so few participants. Conversely, if you're a "long term" investor then be ready to sell on a moments notice using market orders only. If you use a stop order to sell at the price of $27 then it is likely that you could get stopped out at $24 instead of $26.99 or thereabout if the stock trades down in the pre-market on Monday (wouldn't be surprised if this happens.) Touc.

Source:

Related Articles:

Please revisit Dividend Inc. for editing and revisions to this post.

This blog is being featured on www.condron.us, I hope you find this useful
Sell Bank of Hawaii (BOH) at the Market

It is now time to recommend that Bank of Hawaii (BOH) be sold at the market. The stock has performed modestly since the research recommendation was issued on January 12, 2009. It is highly recommended that anyone who bought the stock based on my research should re-read the posting. The stock took a huge dive in early March, it is hoped that shares of BOH were bought somewhere below the recommendation price.

From the current level, BOH is likely to continue higher as the current deflationary spiral ends and an inflationary environment begins. If you believe that inflation is coming down the road then the Japanese economy has typically performed better during inflation. Growth in the Japanese economy has typically meant growth in the Hawaiian economy. Additionally, BOH has held up very well in the banking crisis that just past and is poised to reach the $45 level, especially because we just got a Dow Theory cyclical bull market signal (within a larger secular bear market.) In the pursuit of "seeking fair profits" the returns that this stock has provided within the last 207 days say that it is worthwhile considering alternative opportunities.
BOH was recommended when it was trading at $37.76. As of August 6, 2009, BOH was quoted at $40.98. This equals a total return (dividends plus appreciation) of 11.36% in a little over 7 months. Conservatively, on an annualized basis this would equal approximately 19.47% return. Selling this stock now also generates a return 4 times greater than the amount of the dividend yield if the stock was held for a whole year.

It is always recommended that when selling a stock, one should not place an order after hours or when the market is closed. This leaves the seller in the position of being vulnerable to the whims of the market makers. Instead, place your sell orders only as a market order during market hours. Some would complain that a market order during market hours might leave some profits on the table. However, I would rather leave some money on the table rather than have it taken away from me by the trades that are placed by institutions and market makers. Touc.


Please revisit Dividend Inc. for editing and revisions to this post.

After-Hour Conundrum

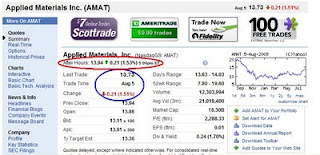
The first after-hour profile is Applied Material (AMAT). In the screen shot below we see that AMAT has a market capitalization of $18.3 billion. During market hours on August 5th, we see that the stock traded down by 1.51% or $0.21. Over the last 3 months, AMAT has had average daily volume of 21 million shares.

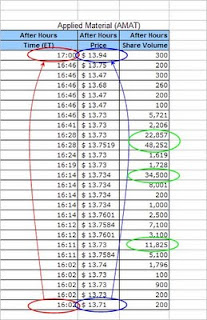
In the screen shot below, we see that in after-hour trading AMAT traded up by exactly $0.21 bringing the price right back to where it started in the beginning of the day. Notice that during the after-hour trading it took only 160,000 shares to offset 12,303,994 shares traded during regular hours. Also notice that four trades equaled 73% of the total after-hour volume.
What I'd like to know is this, who is holding 48,252 worth of AMAT shares valued at $663,465? Why does anyone who owns so many shares try to sell them at a time when they wouldn't likely get the best price available? Who is matching up these trades?
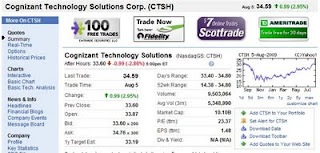
Next up is Cognizant Technology Solutions (CTSH). Below we see that CTSH traded up by $0.99 on trading volume of 9,503,064. However, during after-hour session we can see that CTSH trades back down by $0.99. It only took 99,202 shares to get the price exactly back to where it started earlier in the day.
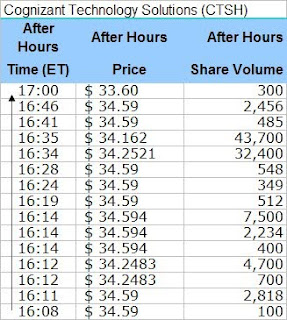
Again, notice that someone with 43,700 shares worth $1,468,966 decided that after-hours was the best time to unload the shares. Not to be outdone, someone else with 32,400 shares valued at $1,109,768 feels like getting rid of their shares.
Conclusion

From my experience routing trades to the floor of the NYSE in the mid-90's, these transactions are suspect. After all, who would try to unload so many shares without disrupting the market price. In the case of Cognizant Solutions, the 43,700 shares sold was 44% of all after-hour trading. such a large proportion of trading volume would normally spike the price up or down dramatically. Strangely, there was someone willing to obtain the odd number of shares after-hours. This is a highly unusual transaction for so many shares at a time when the market is so illiquid. In fact, most of the After Hours Activity that I have posted show similar patterns.
My suspicion is that institution(s) are accumulating short/long positions as the price of the stock rises during the regular hours. Once the market closes, the same institution sell/buy the shares to/from themselves or a related party. Additionally, options for the stock could have been purchased, sold or written in anticipation of the expected change in price after-hours. This is definitely something that is worth investigating further to determine how these transactions are being carried out. Not to mention the fact that the shares are rising and falling by exactly the opposite amount that took place during regular market hours.
Sources:
 

Sell Matthews International (MATW) at the Market

It is now time to recommend that Matthews International (MATW) be sold at the market. The stock has performed reasonably since the research recommendation was issued on March 31, 2009. It is highly recommended that anyone who bought the stock based on my research should re-read the posting. The stock took a tiny dip in mid-April, however the recommendation was essentially at the low for the stock price. From the current level, MATW is poised to reach the second upside target of $40.77, especially because we just got a Dow Theory cyclical bull market signal (within a larger secular bear market.) In the pursuit of "seeking fair profits" the returns that this stock has provided within the last 126 days say that it is worthwhile considering alternative opportunities .
MATW was recommended when it was trading at $29.04. As of August 3, 2009, MATW was quoted at $31.95. This equals a return of 10.25% in a little over 4 months. Conservatively, on an annualized basis this would equal approximately 29% return. Selling this stock now also generates a return 11 times greater than the amount of the dividend yield if the stock was held for a whole year.

It is always recommended that when selling a stock, one should not place an order after hours or when the market is closed. This leaves the seller in the position of being vulnerable to the whims of the market makers. Instead, place your sell orders only as a market order during market hours. Some would complain that a market order during market hours might leave some profits on the table. However, I would rather leave some money on the table rather than have it taken away from me by the trades that are placed by institutions and market makers. Touc.


Please revisit Dividend Inc. for editing and revisions to this post.

Another Market Anomaly

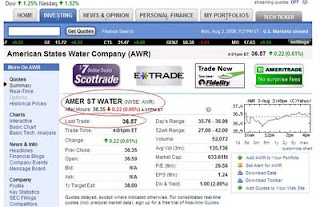
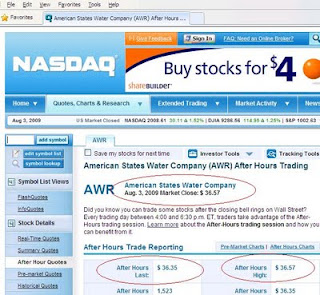
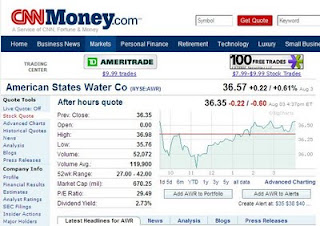
As strange as it might seem, the following companies (excel format) traded down or up in after-hours trading in the exact dollar amount that they traded up or down during the regular hours of trading. This is exactly what I mentioned took place August 29, 2008.

These aren't small cap companies that we're talking about. These are large companies with reasonable amounts of market volume during the regular hours. How is it that all the activity of the masses can be so easily off-set by marginal volume after hours to go back from whence they came? Since the article on the same topic was posted last year, it was posited that maybe traders were balancing their books and therefore it really wasn't all that significant after all. Others said that because all of these sources get their data from the same place it really didn't matter how many sources I procured.

First, the balancing of market maker books needs to take place during market hours unless there is a crash in the market and the volume cannot be handle in the normal fashion. Second, after hour balancing of the books in this fashion should be considered market manipulation to the ordinary citizens who bought or sold their stock during the regular trading hours. Third, I chose to confirm the data from as many sources as possible to verify that it is accurate.

At best this should be considered manipulation and at worst it should be considered stealing, especially since the records of these after-hour transactions are lost in the normal course of market trading. When everybody wakes up tomorrow there will be no record of what happened during after hours trading.

After hours trading needs to be stopped or the records of these transactions should be widely available to the public in a fashion that can be tracked over time. Touc.

  • AMER ST WATER AWR
  • Autodesk, Inc. ADSK
  • BancFirst Corporation BANF
  • BRADY CP CL A BRC
  • BRIGGS STRATTON DC BGG
  • C.H. Robinson Worldwide, Inc. CHRW
  • CIMAREX ENERGY CO XEC
  • Cintas Corporation CTAS
  • CITIGROUP INC C
  • COMMUNITY BK SYS INC CBU
  • EMERSON ELEC CO EMR
  • Expeditors International of Was EXPD
  • FIRST COMMONWLTH FIN FCF
  • Fulton Financial Corporation FULT
  • Harleysville Group Inc. HGIC
  • HARSCO CP HSC
  • HEINZ H J CO HNZ
  • HILL-ROM HOLDINGS IN HRC
  • IBERIABANK Corporation IBKC
  • ILL TOOL WORKS INC ITW
  • INTEGRYS ENERGY GRP TEG
  • MERCK CO INC MRK
  • Meridian Bioscience Inc. VIVO
  • MINE SAFETY APPL MSA
  • MYERS INDS INC MYE
  • Otter Tail Corporation OTTR
  • OWENS AND MINOR INC OMI
  • PENTAIR INC PNR
  • PITNEY BOWES INC PBI
  • QUESTAR CP STR
  • S J W CP SJW
  • S&T Bancorp, Inc. STBA
  • Sigma-Aldrich Corporation SIAL
  • SMITH A O CORP AOS
  • STEPAN CO. SCL
  • SUPERIOR IND INTL SUP
  • TAUBMAN CENTERS INC TCO
  • TELEFLEX INC TFX
  • TENNANT CO TNC
  • TOTAL SYSTEM SVC INC TSS
  • Universal Forest Products, Inc. UFPI
  • Urban Outfitters, Inc. URBN
  • Vertex Pharmaceuticals Incorpor VRTX
  • Warner Chilcott Limited WCRX

Sample Data Sources:


Please revisit Dividend Inc. for editing and revisions to this post.
This blog is being featured on www.condron.us, I hope you find this useful.

Q & A

Q: Do you really think we get through this crisis without ever having an undervalued market?

A: First, the crisis is past us and now we're faced with sorting through the wreckage which is more painful than the actual crisis itself. The general public now has the taste of bitterness necessary to feel that maybe there is a difference between saving and investing or the distinction between investing and speculating. The public now knows, by force of nature, that a home is a place where you live and not an investment. These realities, which faded after the Dow first hit 10,000, are in the recesses of the collective subconscious. While the lessons will be quickly forgotten, reminders will reappear in stark contrast to the hopes of the ever optimistic public.

In many of my postings and in the right hand column of my site you'll see that I expect this to be a bear market for at least the next 7 to 9 years. My 2016 date (based on cycle analysis) is the approximate year that I expect that either the market will hit its ultimate low or the point when valuations are expected to be at the most extreme low levels. Even after the year 2016 I do not expect the market to immediately go to new highs. Instead I expect that the market will meander for another 6-8 years before exceeding the previous high for good.

Within the context of a secular bear market there will be cyclical bull markets or bear market rallies. Great examples of the kind of market action that I expect are years from 1906-1924 or 1966-1982. Remember, a secular bull market has the ability to exceed the previous market high by at least 16.5%.

We will see a period when valuation are at historical low levels. Unfortunately, it will be very difficult to convince the retail investor that buying stocks en mass is the right thing to do. As an example, 1982 was a great year to buy stocks but with treasuries yielding 12% there was no way to convince the public that the Dow with a yield of 5.5% was worth it. Guaranteed money at 10-12% versus stocks at 5% seemed like a no-brainer.

Q: Do corporate earnings just recover from here while the market moves sideways to allow P/E and dividend yields to catch up?

A: I believe that we'll see earnings remain flat as corporations continue to cut costs but the shocker will be that we'll see earnings. The problem will be that corporations will cut costs too much which will lead to a general rise in prices and an increase in the value of corporate assets. Chapter 2 of the book Dow 3000 by Thomas Blamer and Richard Shulman clearly explains what most investors forget at the end of a bear market. Essentially, companies will become more valuable even though the stock price and earnings don't go anywhere.


"Men, it has been well said, think in herds; it will be seen that they go mad in herds, while they only recover their senses slowly, and one by one."


Mackay, Charles. Extraordinary Popular Delusions and the Madness of Crowds. preface. 1852.


Dividend Achiever Watch List

The market continued to march higher this week. The Dow gained 78 points, a gain of 0.86%. My watch list now contains 9 companies compare to 11 of last week. Important introduction to this list is Pitney Bowes(PBI). The company fell 12% on Friday after announced earning of $0.55/share and the consensus was for $60/share. A missed of 8%. Read this post for some detail on the stock. Here are the companies on my watch list as of July 31, 2009.

Nasdaq 100 Watch List

Coppock Curve Review

Today is the end of the month which means that we can now review the Coppock Curve(also known as the Coppock Index) to determine if the direction for stocks is indicated to be moving higher overall. Since the last bottom in the Coppock Curve back in April the index has had the following monthly figures:

  • April 2009:-388
  • May 2009:-383
  • June 2009:-378
  • July 2009: -359

From what I can tell we need another 3 months of rising numbers along with an increase above -260 for the Coppock Curve to establish a clear signal that a sustainable market reversal is at hand. I know that asking for 3 more months of rising figures seems like a lot. However, I just don't want to get faked out like what occurred in May of 2002. The actual turn in the index took place in March of 2003, almost a full year later. Would I be missing a lot of market "action" by taking this stance? Absolutely. However, the risk to your hard earned principal is what is at stake. It is always best to take the cautious stance on these matters.


Remember, The Coppock Curve is a relative strength index. In almost every instance that this index rises from a negative number to a positive number it has coincided with a relatively risk-free time to invest in stocks. In turn, an improvement in the stock market is a reflection of the better times in the U.S. economy overall. Let us hope that the trend continues. Touc.


Please revisit Dividend Inc. for editing and revisions to this post.

Achiever Alert: Pitney Bowes (PBI)

Yesterday (July 30th) in after-hour trading, Pitney Bowes (PBI) fell by $1.89 or 8.04% to close at $21.61 due to downward revisions of future earnings. This may be the situation where the stock becomes severely underpriced by the markets.After a quick read, I found out that PBI normally trades around 7.5 times cash flow according to Valueline Investment Survey. If we use full year 2008 cash flow of $4.66 then we'd arrive at a mean price of $34.95. This suggests that PBI is trading 38% (a nice Fibonacci and Dow Theory number) below the mean price. As a Dividend Achiver, PBI has increased the dividend every year for 25 years in a row at a 10-year CAGR of 5.5%. According to Investment Quality Trends, PBI is undervalued at a price of $29 with a yield of 5%.

PBI has many issues that cannot be ignored. The debt situation is not very favorable to the company, especially since PBI provides the financing for their consumers. PBI could have overextended credit on the upswing of the previous cycle and is now getting hit by the double whammy of companies having difficulty paying back their debt as well as a stalled economy that has reduced the demand for their postal equipment. PBI also has a high dividend payout ratio of 73% based on trailing twelve months earnings.

My expectation is that PBI will fall further when the market opens. As long as the Dow Theory bull market indication isn't reversed and depending on the extent of the decline, I would consider buying PBI. Of course, I'm hoping for a situation where the price goes all the way down to the $14 or $15 level established in 1992. I strongly recommend that you watch this stock and do your research. Touc.


Please revisit Dividend Inc. for editing and revisions to this post.

Congrats to Terry

The winner of my reader appreciation day book giveaway is Terry Rumpza of Newport, Minnesota. The book Dow's Theory Applied to Business and Banking by Robert Rhea is now bound for L'Etoile du Nord. Thanks to everyone who responded and please keep reading. I hope to entertain and possibly enlighten on matters related to the economy and the stock market. Touc.


Please revisit Dividend Inc. for editing and revisions to this post.

Concerned About Market Manipulation?

Lately there has been a lot of news about high frequency trading, flash trading, and "alleged" market manipulation by Goldman Sachs and others. However, in my March 16, 2009 posting, I covered the issue of short selling bans, market manipulation and their true effect on the market. It should be noticed that in the high frequency trading article there is a discussion of the issue of stocks priced in pennies. The article states:

"U.S. equity exchanges have catered to such clients since at least 1997, when the NYSE ended its century-old practice of quoting stocks in eighths of a dollar. It shifted to penny increments in 2000. That eroded earnings for NYSE and Nasdaq market makers, who profit from the difference between bids and offers. For investors, it helped reduce trading costs.
The exchanges sought to compensate for the lost business by paying rebates to high-frequency brokerages that buy shares at the best public prices. Exchanges have also overhauled their trading systems to cut transactions times and rent space in data centers so it takes less time to transmit information to buyers and sellers. Bats Global Markets processes orders in less than 400 microseconds, or 0.0004 second, which is about 1,000 times faster than humans blink their eyes."
Edgar Ortega, Jeff Kearns and Eric Martin. "High-Frequency Traders Say Speed Works for Everyone." Bloomberg.com. July 28, 2009. accessed July 29, 2009.

This issue of stocks trading in pennies instead of eighths is critical to the increased manipulation of the stock market. This was a specific matter that I raised in my March 16th posting.

Also, in the comment section of the same March 16th posting, I got a great question about the effectiveness of limit orders and stop loss orders. As I said at the time, your only tool for avoiding the maximum amount of market manipulation is to place market orders. As early as August 12, 2008 in my sell recommendation of Helmerich and Payne, I stated that only market orders should be used to avoid manipulation. Any individual investor who uses automatic orders as a form of "protection" is really subjecting themselves to greater losses and diminished gains. You heard it here first. Touc.


Please revisit Dividend Inc. for editing and revisions to this post.